• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Personal Finance

Strategic Retirement Planning: Integrating Home Care Packages Into Your Future

January 11, 2024 by Susan Paige Leave a Comment

Hand putting Coins in glass jar with retro alarm clock for time to money saving for retirement concept

As you approach retirement, it’s crucial to think about your finances, future living arrangements, and health care needs. Integrating home care packages into your retirement plan is a smart move, one that ensures comfort and security in your later years. 

This article will explore the significant role of in-home services in your retirement. You’ll discover various service types, how to budget for them, and why they’re essential for a well-rounded retirement strategy. 

The Rising Need For Home Care In Retirement

As the population ages and life expectancy increases, the demand for in-home care during retirement is on the rise. In the U.S., the majority of home care recipients are over 65, with approximately 91% needing help moving in and out of bed. These figures underscore the growing necessity of factoring in this type of care when planning for retirement.

Additionally, the trend of aging in place, preferring home over institutional settings, is gaining popularity. This choice reflects a desire for a familiar and independent retirement lifestyle.

Types Of Home Care

Understanding the types of home care packages available is crucial to retirement planning. These packages support your living and health care needs at home, adapting as your requirements change.

  • Basic Care Packages: These are designed for individuals who need minimal assistance. Services might include help with housekeeping, basic meal preparation, and occasional transportation for errands or appointments.
  • Intermediate Care Packages: For those requiring regular assistance, intermediate packages offer more comprehensive services. This could include regular help with personal care, medication management, and more frequent transportation services.
  • Advanced Care Packages: Tailored for individuals with significant health care needs, these packages provide extensive assistance. Services include daily personal care, skilled nursing, physical therapy, and potentially even 24-hour care.
  • Specialized Care Packages: These are specific to certain conditions, like Alzheimer’s or other forms of dementia. Specialized care packages focus on providing tailored support, ensuring safety, and maintaining quality of life with condition-specific expertise.

Choosing the right home care package is essential for a comfortable retirement, ensuring you receive suitable support and can budget effectively for future care.

Financial Planning For Home Care

Effective financial planning for in-home support is vital in ensuring your retirement years are both comfortable and financially manageable. Here are the important considerations:

  • Assessing Costs

Start by getting a clear understanding of the costs associated with different levels of home care. Basic care packages are generally less expensive, while advanced or specialized care can significantly increase costs. 

For example, a basic care package might cost a few hundred dollars a month, whereas specialized care for conditions like Alzheimer’s can run into thousands.

  • Budgeting For Home Care

Incorporate home care expenses into your retirement budget. Consider factors like inflation, potential increases in healthcare costs, and the possibility of needing more intensive care in the future. 

For instance, setting aside an additional 10% to 20% of your estimated healthcare budget can help cushion against unforeseen increases in costs.
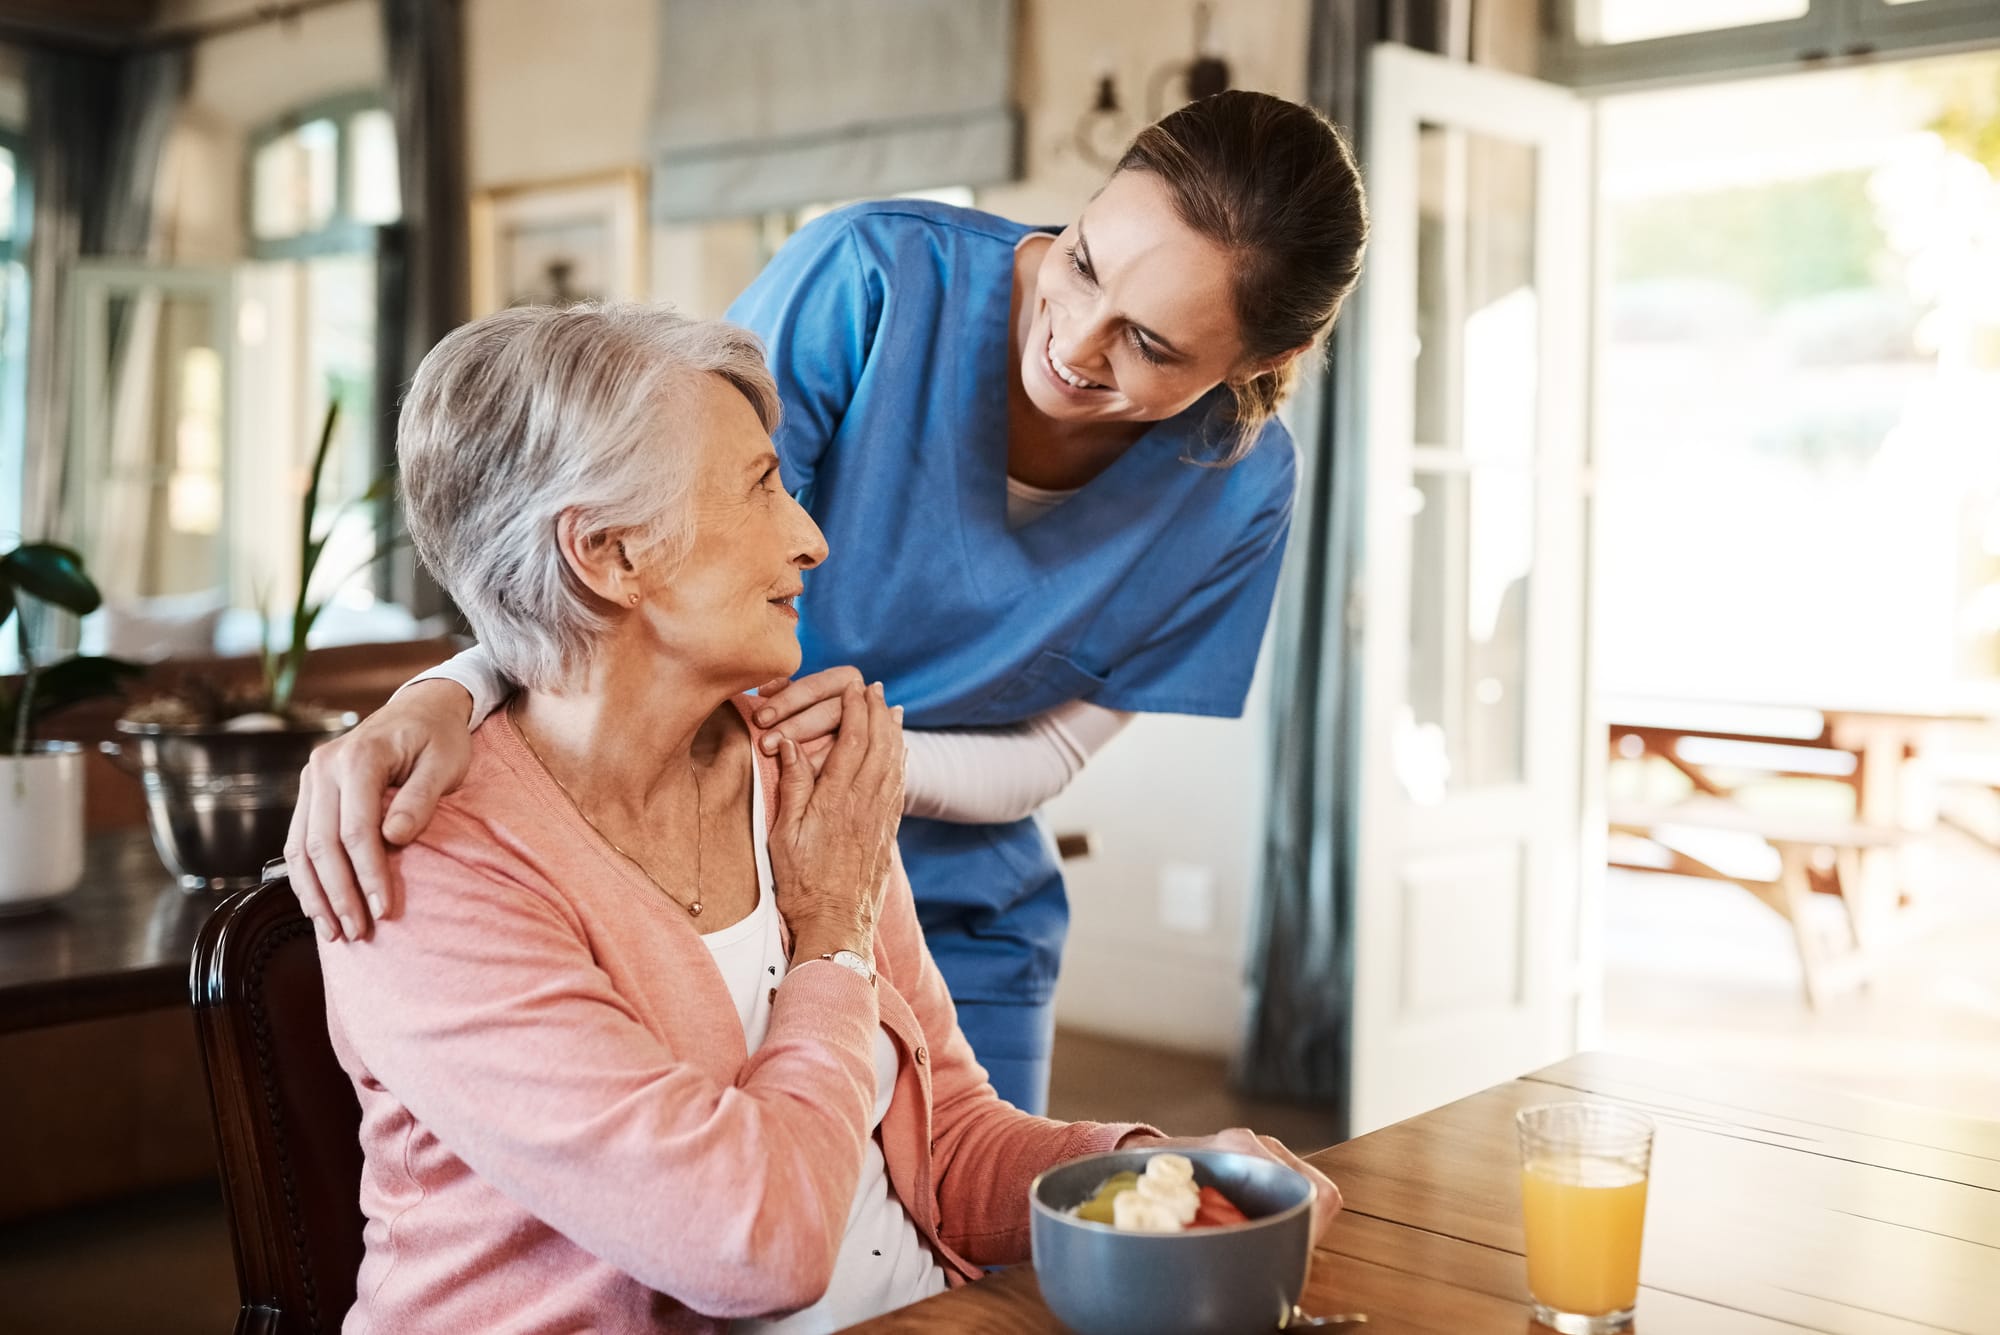
Healthcare, elderly woman with nurse with breakfast at her home and at the table in living room. Support or communication, caregiver and conversation with medical person with senior or old female
  • Exploring Insurance And Government Aid

Investigate long-term care insurance, which can cover some costs of in-home care services. Additionally, look into government programs like Medicare and Medicaid, which may offer financial assistance for certain services. 

Medicare often covers short-term home health care, while Medicaid may assist with long-term care for eligible individuals.

  • Planning For The Long Term

Consider the potential for long-term needs. This might involve setting aside a portion of savings specifically for home care or looking into financial products like annuities that can provide a steady income stream for future care expenses. 

For example, some retirees choose deferred annuities that begin payouts at a later age when in-home care services are more likely needed.

Incorporating these financial strategies into your retirement planning will help ensure you can afford the care you need without compromising your financial security.

Legal And Health Considerations In Home Care

When planning for home care in retirement, it’s important to understand legal agreements and anticipate health changes. Clear contracts with providers ensure your care aligns with expectations and needs. A flexible care plan, adaptable to evolving health conditions, is crucial for long-term comfort and security.

Involving family in decision-making can also provide support and peace of mind. Open discussions about personal wishes and practical healthcare needs are essential. This collaborative approach ensures that your home care solutions are both effective and respectful of your preferences.

By proactively addressing legal and health considerations, you can facilitate a smoother transition into a home care setup, making it an integral part of your retirement plan.

Final Thoughts

As you plan for retirement, including home care packages is a practical step towards ensuring a comfortable and secure future. By understanding the different types of care available, assessing costs, budgeting effectively, and being aware of insurance and legal considerations, you’re setting yourself up for a retirement that’s not only manageable but also dignified and fulfilling. 

Remember, advance planning can make all the difference in enjoying your retirement years with peace of mind and independence. It’s never too early to start building a retirement plan that truly meets your future needs.
 

Filed Under: Personal Finance

Understanding Life Insurance: Key Facts and Insights

January 9, 2024 by Susan Paige Leave a Comment

Life insurance is a vital financial tool that offers a safety net for individuals and their families, providing financial security and peace of mind in times of uncertainty. To make well-informed decisions about life insurance, it is essential to comprehend its various aspects fully. In this comprehensive guide, we will delve into the key facts and insights about life insurance, helping you gain a deeper understanding of this critical component of financial planning. Life insurance is a contractual agreement between an individual (the policyholder) and an insurance company. In exchange for regular premium payments, the insurance company pledges to provide a death benefit to the policyholder’s beneficiaries upon their passing. This financial protection ensures that loved ones are taken care of in the event of the policyholder’s death.

Types of Life Insurance

Term Life Insurance

Term life insurance offers coverage for a specific period, typically 10, 20, or 30 years. It provides a death benefit but does not accumulate cash value. Term policies are affordable and ideal for individuals seeking temporary coverage, such as to protect their family during their working years.

Whole Life Insurance

Whole life insurance, often referred to as permanent insurance, is a comprehensive financial tool that offers lifelong protection to policyholders. It stands out from term life insurance in that it combines a death benefit with a unique cash value component that has the potential to grow over time. One notable aspect of whole life policies is their ability to provide not only a safety net for your loved ones in the event of your passing but also an opportunity to accumulate wealth gradually.

When exploring insurance options, it’s crucial to consider local providers, such as a Scottsdale Insurance agency, or those in other cities, to guarantee a policy that’s perfectly adapted to the regional nuances and your personal needs.

Universal Life Insurance

Universal life insurance is a flexible policy that allows policyholders to adjust their premium payments and death benefits within certain limits. It also accumulates cash value and provides greater control over the policy’s terms. This flexibility makes it suitable for those who anticipate changes in their financial situation.

Benefits of Life Insurance

Life insurance offers several key benefits:

Financial Security for Loved Ones

The primary purpose of life insurance is to provide financial security to your loved ones in the event of your passing. The death benefit can help cover living expenses, pay off debts, and ensure your family’s well-being.

Debt and Mortgage Protection

Life insurance can be used to pay off outstanding debts, including mortgages, car loans, and credit card balances, relieving your family of these financial burdens.

Estate Planning

Life insurance plays a vital role in estate planning, helping to preserve and transfer wealth to heirs efficiently. It can cover estate taxes, ensuring that your assets are passed down as intended.

Tax Advantages

Life insurance proceeds are generally tax-free to beneficiaries. Additionally, certain policies offer tax-deferred growth on the cash value component, making them attractive for long-term financial planning.

Peace of Mind

Knowing that you have life insurance coverage in place provides peace of mind, knowing that your loved ones will be financially protected no matter what the future holds.

How Does Life Insurance Work?

Life insurance operates on a straightforward premise: you pay regular premiums, and in return, your beneficiaries receive a tax-free death benefit when you pass away. The coverage amount and premiums depend on the type of policy and your individual circumstances. It’s essential to select a coverage amount that adequately meets your family’s financial needs.

Determining Your Coverage Needs

Calculating the right amount of coverage is essential. Factors like your age, income, debts, and family’s financial needs should be considered. An insurance agent or online calculators can help determine your coverage needs accurately. Remember that your needs may change over time, so it’s crucial to review your policy periodically.

Factors Affecting Premiums

Several factors influence your life insurance premiums, including:

  • Age: Younger individuals typically pay lower premiums than older individuals.
  • Health: Your health status and medical history play a significant role in determining your premiums. Those with pre-existing conditions may face higher costs.
  • Lifestyle: Risky behaviors, such as smoking or engaging in hazardous activities, can lead to higher premiums.
  • Type of Policy: The type of life insurance policy you choose will impact your premiums. Term policies are generally more affordable than whole or universal life policies.

Cash Value in Life Insurance

Whole and universal life insurance policies accumulate cash value over time, which can be accessed through loans or withdrawals. This feature can be a valuable source of funds in emergencies or supplement your retirement income. Keep in mind that any loans or withdrawals may affect the death benefit.

Tax Implications of Life Insurance

Life insurance proceeds are generally tax-free to beneficiaries. However, there are exceptions, such as when the policy is considered part of your estate for estate tax purposes. Consulting with a tax advisor or financial planner can help you navigate the tax implications effectively.

Choosing the Right Life Insurance Company

Selecting a reputable insurance company is a critical step in obtaining the right life insurance policy. Consider the following factors when choosing a company:

  • Financial Stability: Ensure that the company is financially stable and capable of fulfilling its obligations to policyholders.
  • Customer Reviews: Research customer reviews and ratings to gauge the company’s reputation and customer service.
  • Types of Policies: Look at the types of life insurance policies offered by the company and choose one that aligns with your needs and goals.

Common Myths About Life Insurance

Dispelling myths about life insurance is essential. Some misconceptions include it being too expensive or unnecessary for young individuals. In reality, life insurance can be affordable and beneficial for all age groups. It’s essential to base your decisions on accurate information rather than misconceptions.

Who Needs Life Insurance?

Anyone with financial dependents or obligations should consider life insurance. It provides financial protection and ensures your loved ones are taken care of in your absence. Whether you’re a young parent, a homeowner, or a retiree, life insurance can play a crucial role in your financial planning.

Life Insurance as an Investment

Some types of life insurance, such as whole life, can serve as an investment vehicle. They offer a combination of protection and a way to build cash value over time. While they may not provide the same returns as traditional investments, they offer stability and tax advantages that can be appealing.

Reviewing and Updating Your Policy

Life changes, and so should your insurance policy. Regularly reviewing and updating your coverage to reflect your evolving financial needs and circumstances is crucial. Life events such as marriage, the birth of a child, or changes in income should trigger a review of your life insurance coverage.

Conclusion

Understanding life insurance is crucial for making informed financial decisions. It offers financial security, peace of mind, and a way to protect your loved ones. By considering the factors discussed in this guide, you can choose the right life insurance policy that suits your needs and provides a solid foundation for your family’s future financial well-being. Life insurance is not just a financial product; it’s a promise to provide for your loved ones when they need it most.

Filed Under: Personal Finance

Evaluating Today’s Financial Tools for Kids: What Works in 2024

January 8, 2024 by Susan Paige Leave a Comment

Evaluating Today’s Financial Tools for Kids: What Works in 2024?

In 2024, the world of financial education for kids has transformed dramatically, integrating technology and interactive learning methods. This evolution is not just a trend but a necessity, as financial literacy has become an essential skill for the younger generation. In this article, we explore various financial tools designed for kids, assessing their effectiveness in imparting crucial money management skills.

Understanding Financial Literacy for Kids

Financial literacy for children is more than just understanding money; it’s about making informed and effective decisions regarding financial resources. Traditionally, financial education was limited to piggy banks and allowance management. However, as we progress in the digital age, the approach has shifted to include apps, games, and online platforms, making learning both fun and relevant.

Digital Piggy Banks: A Modern Twist on Saving

Digital piggy banks have revolutionized the way kids save money. Unlike traditional piggy banks, these digital versions often come with interactive features like goal setting, tracking progress, and even financial rewards for achieving targets. This gamification of saving not only makes the process engaging but also instills a sense of accomplishment in kids.

Educational Apps and Games: Learning Through Play

The power of play in learning cannot be overstated, especially when it comes to financial education. Numerous apps and games are now available that teach kids about budgeting, saving, and investing in an interactive and enjoyable manner. These tools are designed to be intuitive and engaging, ensuring that kids remain interested and motivated to learn.

Prepaid Debit Cards for Kids: Teaching Spending Responsibility

A prepaid debit card for kids is a practical tool for teaching money management. These cards allow kids to make real purchases, but within set limits controlled by parents. This hands-on approach gives children a taste of financial responsibility while ensuring they don’t overspend.

Investment Simulators: Preparing for the Future

Investment simulators are an innovative way to introduce kids to the world of investing. These platforms use virtual money, allowing children to experiment with stocks and learn about market dynamics without any real financial risk. This early exposure can demystify investing and encourage a more financially savvy mindset.

Parental Control and Monitoring: Ensuring Safety

Safety is a paramount concern when it comes to financial tools for kids. Most modern tools come equipped with robust parental control features, allowing parents to monitor and guide their children’s financial activities. This oversight ensures that kids learn in a safe and controlled environment.

Real-Life Financial Challenges: Preparing Kids for the Real World

Simulating real-life financial scenarios is an effective way to prepare kids for future financial challenges. These simulations can range from managing a budget to dealing with unexpected expenses, providing practical lessons in money management.

Collaborative Learning: Parents and Kids Learning Together

The role of parents in financial education is irreplaceable. Tools that facilitate collaborative learning between parents and children can lead to more meaningful and lasting financial understanding. This partnership in learning helps in building a strong financial foundation for kids.

Impact of Social Media on Kids’ Financial Habits

In today’s digital age, social media has a significant impact on kids’ financial habits. It’s crucial to teach children to critically assess the financial information and trends they encounter on these platforms. This critical thinking is essential in developing a healthy and informed approach to money management.

Savings Goals and Rewards: Motivating Young Savers

Setting savings goals and providing rewards can be a powerful motivator for kids. Financial tools that incorporate these elements can make the process of saving more tangible and rewarding, encouraging kids to continue their financial journey.

Financial Tools for Different Age Groups

It’s important to recognize that financial tools need to be tailored to different age groups. Younger children might benefit from simple saving apps, while teenagers might be ready for more complex tools like investment simulators. Choosing the right tool for the right age group is crucial in ensuring effective learning.

The Role of Schools in Financial Education

Schools play a vital role in providing structured financial education. While home learning is important, schools can offer a more formal and comprehensive approach to financial literacy. The integration of financial education into school curricula is an essential step in preparing children for financial independence.

Future Trends in Financial Tools for Kids

Looking ahead, we can expect to see continued innovation in financial tools for kids. These future tools will likely be more integrated with real-world financial systems, providing even more practical learning experiences. Staying updated with these trends is important for parents and educators alike.

Conclusion

In conclusion, the array of financial tools available for kids in 2024 offers diverse and effective ways to teach financial literacy. From digital piggy banks to investment simulators, each tool brings a unique approach to learning about money. As parents and educators, it’s our responsibility to guide our children through these tools, ensuring they acquire the necessary skills to navigate the financial world confidently.

FAQs

  1. What is the best age to start teaching kids about financial literacy?
    • Financial education can start as early as preschool, with simple concepts like saving and spending.
  2. Are digital financial tools safe for kids to use?
    • Yes, most digital financial tools designed for kids come with robust security and parental control features.
  3. How can parents ensure that their kids are not overwhelmed by these financial tools?
    • Parents should choose age-appropriate tools and be involved in the learning process, guiding their kids gradually.
  4. Can these financial tools replace traditional money management methods?
    • While they can’t entirely replace traditional methods, they are effective supplements that cater to the digital generation.
  5. What is the role of schools in teaching financial literacy?
    • Schools can provide a structured curriculum and a formal environment for teaching financial literacy, complementing what is learned at home.


Filed Under: Personal Finance

4 Tips to Help Increase Approval Odds for a Personal Loan When Bad Credit Haunts You

January 3, 2024 by Susan Paige Leave a Comment


Emergencies requiring cash tend to happen at the most inconvenient time – right after you’ve rebuilt savings for a previous emergency or at a time of year when spending tends to drift upwards, like back-to-school time, summer vacations, and the holidays. While there’s no stopping those pesky situations that pop up, getting a personal loan can help buy new tires or replace your broken fridge.

Getting personal loans for bad credit is possible, but before you do it, you can do a few things to help you improve your chances of being approved. 

1. Check Your Credit Report

Every American is entitled to free weekly credit reports through AnnualCreditReport.com. If you’re not checking this already, you should so that you can find potential errors or red flags. Human data entry errors are unfortunately common on credit reports, so look for things that can be easily fixed. It may take time, but removing incorrect information will ultimately boost your credit score. Second, look for items that can be easily fixed. Is there a small debt that you can write a check for and pay off today? Did you miss a payment last month? If so, pay that now so you are up to date on your bills. 

2. Add Up All of your income

When you apply for a loan, lenders ask for your income to determine how much they’ll lend you. They need to know your income so they don’t loan you too much, thus making it harder for you to repay the loan. However, your income isn’t limited to the amount on your paycheck. You can also include non-employee income like child support and Social Security payments, alimony, or retirement income. The higher your monthly income is, the more likely you are to be approved for a loan of any amount. 

3. Get a Cosigner Who Has Excellent Credit

Find a relative or friend who has good credit to be your cosigner. This needs to be someone who trusts you since they will be on the hook for your debt. However, if they’re willing to “lend” you their good credit, it could help you get the loans and maybe even a higher amount or lower interest rate. Alternatively, you could ask to be made an authorized user on someone else’s account, like a credit card. This is helpful because some of their good credit history passes on to you once you’re added. They will need your Social Security number and, ideally, not give you an extra credit card or access to the account. 

4. Ask for a Small Loan

Only ask for what you need once you’re ready to apply for a loan. Lenders generally like to start with smaller amounts since it’s less risky for them. Once they see that you pay the loan back on time and in full, they will likely lend to you another time, possibly for a more significant amount. 

Take Action Today!

Even if you don’t need a bad credit loan today, take some time to work through these action steps now. If you are suffering from bad credit, being added as an authorized user or taking a small loan and repaying it quickly can significantly impact your credit report and credit score. Ultimately, this will make it easier to be approved for bad credit loans. 


Filed Under: Personal Finance

A Guide to Gold Investment for Retirement Planning

January 2, 2024 by Susan Paige Leave a Comment

Having a secure future is a huge priority for most individuals, which means planning for your retirement early, such as through investments. Over 75% of non-retired adults have some retirement savings. 

Gold has been one of the most popular retirement investment options due to its history of preserving wealth and providing a hedge against economic uncertainties. Its unique properties and performance during market volatility make it an attractive addition to a retirement portfolio. This article explores the various ways to invest in gold for retirement, highlighting its benefits and considerations for those seeking to secure their financial future.

Advantages of Gold 

Gold is a reliable investment option, especially for retirement, due to its historical stability. It has served as a haven during economic and political uncertainty, retaining its value when other assets struggle. Gold often performs well when the U.S. dollar is weak, acting as a hedge against inflation. 

Additionally, its low correlation with stocks and bonds makes it a valuable diversification tool in a portfolio. While higher-risk assets can offer greater returns, balancing them with gold can help safeguard against potential losses. Visit Learn About Gold to know more about the benefits of owning gold and how it proves to be a better investment than platinum.  

Gold Investment Options

There are various ways to invest in gold for retirement, each suited to different goals and preferences.

1.Gold ETFs

Gold ETFs, or exchange-traded funds, are pooled funds that contain a variety of gold investments mirroring the price of gold. They offer exposure to gold with lower minimum investment requirements, reduced costs, and greater control than alternative gold investments.

2.Gold IRAs 

Gold IRAs are ideal for retirement investing because they are tailored to serve as retirement savings accounts. You contribute funds before retirement and receive distributions after reaching a specified age, ensuring a dependable retirement income source. Gold IRAs also offer tax advantages that can reduce your tax liability immediately or in the future.

3.Gold Stocks

You also have the option to directly invest in gold stocks, which represent shares in companies within the gold mining industry. Owning these stocks allows you to earn a portion of the companies’ profits. While stocks generally carry more risk than other investment types, they can provide higher returns, particularly in the early stages.

4.Physical Gold 

For investors who appreciate tangible assets they can physically handle, physical gold (or bullion), like gold bars and coins, might be preferable. However, it’s important to note that holding physical gold entails secure storage requirements and insurance costs, so consider these factors when making investment decisions.

5.Gold Futures 

Gold futures are speculative bets on the future price of gold on a specific date. Due to their speculative nature, they are more suitable for experienced investors and are not typically recommended for those focused on retirement savings.

6.Gold Mutual Funds 

Gold mutual funds are a form of pooled investment fund that holds shares in companies involved in gold mining. Managed by professionals, they have the potential for greater returns than gold ETFs. However, investors should know that higher returns also entail higher risks.

Endnote 

Planning for a secure retirement is crucial, and gold is one of the popular retirement investment choices due to its stability, acting as a hedge against economic uncertainty and inflation. Investment options include Gold ETFs with low entry costs, Gold IRAs tailored for retirement, direct investment in Gold Stocks, physically owning gold, and speculative Gold Futures. Each option offers unique benefits and considerations for retirement planning.


Filed Under: Personal Finance

Here’s How to Counteroffer and Win When Negotiating Your Salary

December 28, 2023 by Tamila McDonald 1 Comment

How to Counter Offer Salary

Receiving a job offer is exciting, but it also leads to one of the more daunting parts of the hiring process: salary negotiations. If the initial number presented by the company doesn’t meet your needs, having a strategy for managing the counteroffer is essential. If you’re not sure where to begin, here’s a look at how to counter offer a salary and win.

How to Counteroffer a Salary and Win

1. Ask for Time

Before you respond to a salary offer, request a reasonable amount of time to consider it. Start by thanking the hiring manager for their consideration thus far, allowing you to start on a positive and gracious note. Then, ask if there is a deadline for a decision. In some cases, the hiring manager will let you know how long the company can wait. If they don’t have a set timeline, request two business days to respond.

Generally, two business days are enough to prepare a counteroffer. Plus, the request isn’t so long as to make it seem like you’re trying to string the company along.

If the hiring manager expects a decision in less time, that doesn’t mean you can’t make a strong counteroffer. However, anything less than 24 hours could indicate the business is trying to rush you, potentially making it harder to handle any research before beginning negotiations. While that’s not inherently a red flag, do make a note of whether the hiring manager is putting a lot of pressure on you and keep it in mind during future conversations.

2. Know Your Value

Figuring out a fair salary to present as a counteroffer generally requires some research. You’ll want to spend time learning about the average compensation for similar positions in your area. Additionally, you’ll need to factor in the value of the skills and experience you bring to the table.

Typically, you’ll want to use several resources to determine what pay rate is appropriate, as each one may be accessing data from different sources. Additionally, make sure your research is location specific, as compensation can vary from state to state or even city to city.

The goal here is to identify a figure that feels competitive to you but also leaves space for the company to counter your offer. Often, the easiest way is to identify a salary range that seems appropriate. Then, you can present a number that’s on the higher end, giving the company room to negotiate down while still remaining in your target range.

3. Examine the Offer

After finishing your research, take a close look at the initial job offer provided by the hiring manager. Along with the salary information, make sure to review the benefits, perks, and bonuses listed. In some cases, a lower pay rate is offset by benefits, perks, or bonus structures that exceed what’s found with competitors. As a result, you need to factor in the value of them when determining whether your potential salary counteroffer is fair.

Additionally, benefits and perks are points you can potentially negotiate, too. Knowing that option is available is helpful if a company doesn’t have much room to negotiate regarding pay rates but can make adjustments to other parts of the offer. For example, you may be able to request more paid time off in lieu of an increased salary.

Knowing that’s an option allows you to see where your counteroffer can potentially go if you encounter resistance during the discussion. That way, you don’t feel stuck either accepting the offer as-is or walking away. Instead, you can pivot, focusing on other points that provide you with value.

4. Prepare Several Paths

Once your research is complete and you’ve reviewed the benefits package, it’s time to prepare for several different paths. First, you’ll design your initial salary counteroffer, as that’s likely what you’ll present first. After that, consider other points you’d potentially negotiate and what you’d request, giving you additional pathways to a fair offer if a higher pay rate isn’t an option.

Essentially, this process is about being prepared for any response the hiring manager may give. That helps keep the conversation rolling while leaving you confident and collected along the way.

5. Present Facts

When you present your counteroffer, remain focused on the facts. After highlighting your ongoing interest in the role, tell the hiring manager the salary you think is fair and provide some details regarding why you came to that conclusion. For example, you can cite your salary research as the basis for your counteroffer.

The goal here is to ensure you’re backing up your requests with solid data. That not only helps you remove emotion from the equation, but it also makes your case more compelling overall. As a result, you may have a higher chance of getting a pay rate that leaves you satisfied.

6. Listen

After you present your initial counteroffer, it’s time to listen. How the hiring manager responds can help you determine where you may need to focus your energies next. Plus, using active listening skills ensures that you don’t miss a critical point.

Again, it’s critical to set emotions aside while the hiring manager speaks. By concentrating on the details they’re sharing, you’ll have a better chance of continuing the conversation in a positive manner.

7. Compromise

After the hiring manager shares their perspective, it’s time to find a compromise that leaves everyone feeling satisfied. For example, you can attempt to balance off a lower salary with improvements in the benefits package, as mentioned above. Just make sure that you remain fact-focused throughout, using data or highlighting your value to show why you’re making various requests.

Additionally, you want to listen carefully to any input from the hiring manager. Not only will that help you determine with points of the offer are negotiable and which aren’t, but it can also give you a lot of insights into the hiring manager’s mindset, the company’s culture, and more. At times, that information is incredibly revealing and may even show that a job you thought was a great fit isn’t necessarily the match it seemed to be on the surface.

8. Make a Decision

Once the negotiations show that there’s no more room for adjustment, it’s time to make a decision. Ideally, you’ll have found some middle ground between the initial offer and your first counter offer. If that’s the case, request the new offer in writing, and review it to ensure it matches what was covered in the discussion before signing.

If you and the hiring manager aren’t able to find a happy medium, then it’s time to determine if the job is genuinely right for you. In some cases, the negotiation process can reveal culture issues or other challenges that could make the position a poor fit. At times, it may simply demonstrate that the company either can’t afford reasonable compensation or isn’t willing to try. If that happens, then walking away may actually be a win, as it lets you focus your efforts on other opportunities that can pay you what you’re worth.

Do you have any other tips that can help someone figure out how to counter offer a salary successfully? Have you tried any of the recommended strategies above and want to tell others about your experience? Share your thoughts in the comments below.

Read More:

  • Just Lost Your Job? Here’s 10 Things Not to Do with Your Severance Pay
  • When It’s Better to Follow Your Dreams Than to Follow Your Salary
  • Why Stress Relief and Work-life Balance Is Critical for Career Success
  • Is a $60,000 Salary Good – Get the facts here
Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance Tagged With: Ask for Time, Compromise, Examine the Offer, How to Counter Offer a Salary and Win, Know Your Value, Listen, Make a Decision, Prepare Several Paths, Present Facts

If You Can’t Pay Your Rent-Use These 6 Tips to Stop An Eviction

December 19, 2023 by Tamila McDonald 1 Comment

late rent notice

Getting a late rent notice is stressful, particularly if you don’t have the money available to pay your landlord. While it may seem like an eviction is inevitable if keeping up with your rent is proving difficult, that isn’t necessarily the case. There are things you can do to help avoid being told to leave the property. If you can’t pay your rent, here are some tips to stop an eviction worth trying.

Talk to Your Landlord or the Property Management Company

One of the first steps you should take if you’ve received a late rent notice – or even if you haven’t but know you’re going to be late with the rent – is to talk to your landlord or the property management company. Speaking with them directly gives you a chance to explain the situation, which is potentially wise if you’re experiencing a temporary hardship.

Your landlord or the property management company may be able to work with you during the short term, giving you the ability to get back on your feet and pay what you owe. For example, some may be able to arrange a payment plan for any past-due rent, allowing you to catch up over time. However, you’ll only know what’s available if you ask, which is why reaching out is worth considering.

Pay What You Can on Time (or as Soon as Possible)

Even if you can’t pay your rent in full on time, sending your landlord or the property management company what you can as soon as possible can help. This is especially true if you’re asking for a little leeway or want to explore options like payment plans to catch up on your rent. It’s considered an act of good faith, as you’re showing you want to pay your rent; you’re just having trouble making it happen.

Plus, paying what you can may help reduce any late fees you’ll owe. In many cases, late fees are based on the amount you haven’t paid, so paying what you can may lead to a smaller charge.

Look for Housing Assistance Programs (or Other Financial Assistance Options)

Many people who are dealing with a low income may qualify for some type of housing assistance, allowing them to get some financial help until they regain financial stability. The types of programs can vary by location. There may be government agencies in your area that can help, as well as a variety of non-profit organizations. Some religious institutions may have programs for people in their area, too.

If you’re not sure where to turn, look for a HUD-approved housing counseling agency in your region. You can use the search tool on the US Consumer Financial Protection Bureau (CFPB) website as a starting point, though doing your research is also an option.

Alternatively, you can explore financial assistance programs that may help handle other household costs, allowing you to direct more of your income toward rent. For example, many areas have utility assistance to help low-income households pay for electricity, water, and more. You may be able to use a local food bank for groceries, allowing you to spend less on food. Essentially, programs like these may help free up room in your budget, giving you a way to catch up on your rent quickly.

Find Ways to Boost Your Income

If rent is going to be a continuing problem, then increasing your income might be your best bet. You could ask for a raise at your current job, get a second job, start a side hustle, or sell off items you don’t need to give yourself a quick cash boost.

If you’re open to an alternative approach, you could also explore getting a roommate who can split the cost of rent with you. Just make sure that bringing someone into the property won’t violate the lease or that you take proper steps to get the contract updated to add your roommate. That way, you’re still following the lease, making it easier to avoid eviction.

Look at Loans to Cover the Difference

As a last resort, you could see if you can qualify for a loan to get enough money to cover any back-due rent. Generally, this only works if you have a reasonable credit score and suitable income to show you’re trustworthy and can handle repayment.

However, this is usually an option you want to explore last. After all, it does involve taking on debt, and giving you another bill to handle every month. But if your financial situation is only going to be challenging for a little while and you’ll be back on your feet before the first payment (and next month’s rent) is due, it’s worth considering.

A similar option here would be to see if you can borrow the money from a family member or friend. Again, treat this as a last resort. Owing money to someone in your life can be awkward, and if you struggle to repay what you borrow, it can significantly harm the relationship. Still, it’s an avenue worth considering if you’re in a short-term bind, so keep it in mind.

Do you have any other tips that can help people facing a late rent notice or possible eviction? Did you manage to stop an eviction and want to tell others about your experience? Share your thoughts in the comments below.

Read More:

  • When Are Manufactured Homes a Good Investment?
  • Why Did I Buy That House? Home Buyer’s Remorse
  • Penny Pinchers’ Paradise: The Crème de la Crème of Budget Planners
Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance Tagged With: boost your income, housing assistance, loan options, pay what you can, talk to landlord

Bankruptcy Blues: 14 Financial Mistakes We Can’t Believe People Still Make

December 19, 2023 by Tamila McDonald Leave a Comment

financial mistakes

In today’s fast-paced financial world, managing personal finances effectively is more important than ever. With a myriad of options and pitfalls, it’s easy to fall into common traps that can lead to financial distress or even bankruptcy.

Below are 14 critical financial mistakes that are surprisingly common yet entirely avoidable. By understanding these pitfalls and learning how to steer clear of them, you can take control of your financial health and secure a more stable and prosperous future.

1. Ignoring a Budget

Surprisingly, many people still navigate their finances without a budget. A budget isn’t just a tool; it’s a crucial part of financial planning, helping you understand where your money goes. Without it, overspending becomes a silent financial killer, often leading to debt accumulation.

2. Relying on Credit Cards for Emergencies

Using credit cards as a safety net is a risky move. While they offer immediate relief, the high interest rates can quickly turn a manageable situation into a debt crisis. It’s wiser to create a dedicated emergency fund for unexpected expenses.

3. Not Saving for Retirement Early

Starting late on retirement savings is a common error with significant consequences. The power of compound interest means that starting early can significantly boost your retirement funds. Delaying this only increases the financial burden and reduces potential gains.

4. Living Beyond Your Means

Living a lifestyle that exceeds your income is a fast track to financial woes. This habit often leads to a cycle of debt and financial stress. It’s crucial to align your lifestyle with your actual income, not your aspirational one.

5. Ignoring Insurance

Many overlook the importance of insurance until it’s too late. Whether it’s health, life, or property insurance, being uninsured can lead to devastating financial losses in times of crisis. Insurance is an essential tool for risk management.

6. Paying Only the Minimum on Credit Cards

Paying just the minimum on credit cards prolongs debt and accrues massive interest. This practice can turn a short-term loan into a long-term financial burden. It’s always best to pay off as much as you can afford monthly.

7. No Emergency Fund

The lack of an emergency fund is a glaring oversight. Life is full of unexpected events, and without a financial buffer, these can lead to debt or worse. An emergency fund provides a safety net, keeping you financially secure during tough times.

8. Taking on Too Much Debt

Excessive debt is a major precursor to bankruptcy. It’s important to use debt wisely and avoid overburdening your financial future. Responsible borrowing involves understanding your repayment capacity and avoiding unnecessary loans.

9. Neglecting Credit Scores

Many underestimate the impact of a poor credit score. It can lead to higher interest rates on loans and credit cards, affecting your financial health. Regularly monitoring and improving your credit score using tools like My FICO is vital for financial flexibility.

10. Co-signing Loans Without Caution

Co-signing a loan is a generous gesture but can be fraught with risks. If the primary borrower defaults, you’re on the hook. Always consider the implications and your ability to pay if things don’t go as planned.

11. Falling for Get-Rich-Quick Schemes

The allure of quick wealth can be tempting, but these schemes often lead to financial ruin. Real wealth is built over time through consistent saving and smart investing. Avoid any plan that promises high returns with little or no risk.

12. Not Diversifying Investments

Putting all your financial eggs in one basket is a risky strategy. Diversification reduces risk by spreading investments across various asset classes. This approach can protect you from significant losses in any single investment.

13. Overlooking Small Expenses

It’s easy to dismiss small expenses, but they add up. Regular small purchases can quietly eat into your budget, leaving less for savings and investments. Tracking and managing these expenses can lead to significant long-term savings.

14. Failing to Plan for Taxes

Taxes are an unavoidable part of financial life. Not planning for them can lead to unexpected liabilities and penalties. Effective tax planning can help you understand your obligations and minimize your tax burden.

Leave The Idea Of Bankruptcy Behind

Navigating the complex world of personal finance can be challenging, but avoiding these 14 mistakes can make a significant difference. From the basics of budgeting to the nuances of investment diversification, each aspect plays a critical role in securing your financial future and helping you leave the ideal of bankruptcy behind.

Remember, financial wellness isn’t just about avoiding bankruptcy; it’s about building a stable life where your money works for you.

Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance Tagged With: bankruptcy, budgeting, Credit card debt, credit scores, emergency fund, financial mistakes, investments, Planning, tax planning

10 Common Financial Habits That Annoy the Experts

December 6, 2023 by Tamila McDonald 1 Comment

Financial Habits

Financial habits play a crucial role in shaping our economic future. While some habits, like a daily latte or occasional shopping splurge, may seem harmless, their cumulative impact on our bottom line can be significant. Even the smallest, routine purchases of $1 or $5 can add up, potentially contributing to chronic debt-related issues. Let’s explore ten common financial habits that not only annoy financial experts but can also hinder your path to financial freedom.

1. Impulse Buying

Snapping up unplanned purchases, whether on sale or not, can lead to unsound spending behaviors. Justifying poor purchasing decisions, using credit cards for impulse buys, and losing track of your budget are common pitfalls. Combat this habit by developing a mantra like “I only buy what I need” and implementing a waiting period before non-essential purchases.

2. Using Credit Cards for Points

While rewards credit cards can be beneficial, they often encourage overspending. Credit card spending activates reward centers in the brain, fostering a craving to spend more. Be wary of credit card reward schemes that may lead to increased debt. If already in credit card debt, consider transferring balances to a lower APR card.

3. Keeping Up With the Joneses

The urge to match your neighbors’ lifestyle, known as “conspicuous consumption,” can lead to overspending. The pressure to impress others often results in unnecessary purchases and compromises financial goals. Remember, appearances can be deceiving, and it’s crucial to prioritize personal financial milestones over societal expectations.

4. Shopping to Boost Your Mood

Retail therapy, or shopping to alleviate stress or boost mood, can become a harmful habit. Repetitive or compulsive shopping may lead to continued spending, irrespective of the emotional, social, and financial consequences. Consider implementing waiting periods before nonessential purchases and seek professional help if emotional spending becomes unmanageable.

5. Spending on Convenience

Overspending for the sake of convenience, such as frequent takeout meals, can hinder debt repayment. Assess your spending habits to identify areas where you can cut back on convenience purchases. Small adjustments, like preparing meals at home, can significantly contribute to reducing unnecessary expenses.

6. Excessive Lifestyle Inflation

While salary increases are expected, excessive lifestyle inflation, where every income increase leads to higher spending, can perpetuate the cycle of debt. Differentiate between needs and wants and avoid increasing spending every time income rises. Redirect additional income towards debt repayment and financial goals.

7. Ignoring Your Debt

Ignoring debt-related issues by avoiding calls from creditors or neglecting bills only exacerbates the problem. Face your financial situation head-on by opening statements, knowing your debt amount, and creating a budget that includes debt repayment plans. Ignoring debt leads to late fees, interest charges, and a deeper cycle of harmful financial behavior.

8. Not Following a Budget

Budgeting is a fundamental tool for financial management. Track your income and expenses, including fixed and variable costs, to gain a comprehensive understanding of your financial situation. Budgeting helps in allocating funds for debt repayment, essential expenses, and discretionary spending.

9. Not Saving Money at All

Even when in debt, saving is crucial. Establishing an emergency fund prevents reliance on credit for unexpected expenses, breaking the cycle of debt. Start small, contribute regularly to savings, and gradually build a financial safety net.

10. Ignoring the Future

Thinking about future goals is integral to breaking the debt cycle. While dealing with debt, envision your future, set goals, and prioritize financial decisions that align with your long-term aspirations. Regularly evaluate and adjust your goals, considering milestones like homeownership, early retirement, or starting a business.

Breaking free from the cycle of debt involves recognizing and altering harmful financial habits. Whether it’s impulse buying, ignoring debt, or succumbing to lifestyle inflation, taking charge and cultivating healthier money habits can pave the way to financial freedom. Remember, progress may be gradual, but the outcome—financial stability and peace of mind—is well worth the effort.

Read More:

These 5 Money Habits Will Keep You Poor

Hiring a Financial Advisor: Clues from the Reception Area

Financial Literacy Tips From A Financial Advisor

Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance Tagged With: bad financial habits, financial habits

Think You’re Too Old To Get Life Insurance – Think Again: 5 Places to Get Life Insurance For Seniors

December 4, 2023 by Tamila McDonald Leave a Comment

life insurance for seniors

As you get older, you typically have fewer life insurance options available. However, there are some undeniably excellent policies out there, and some can cover you for longer than you might expect. That means if you think you’re too old to get life insurance, there’s a good chance you’re wrong. If you want to find a suitable policy, here are five places to get life insurance for seniors.

1. Guardian Life

Guardian Life has some excellent policies that can work well for seniors. If you’re open to term life, you can get up to 20 years of coverage if you’re age 65 or younger. Seventy-year-olds can qualify for up to 15 years of coverage, while 75-year-olds can get 10-year term life policies. With all of these options, the value of the policy can be $100,000 or higher, which makes it easier to get ample peace of mind.

For whole life, seniors as old as 90 years of age can qualify. Coverage levels start at $25,000, making this a solid choice for lower-cost goals like covering final expenses. However, you can potentially secure more coverage. Plus, seniors as old as 85 can explore variable and universal life policies, leading to even more options.

One benefit of choosing Guardian Life is that the company has a solid reputation, with many people being fully satisfied with their policies. When it comes to challenges, the biggest is that there isn’t an online purchase option, so getting a policy may feel a little cumbersome.

2. Mass Mutual

With Mass Mutual, seniors can explore term and whole-life policies. Term life policies are available to seniors as old as 75, and coverage starts at $100,000, though going higher is an option. For whole life, the maximum age for a policy is 90, and the lowest coverage level is $25,000, which is a good amount for final expenses and some basic costs.

Mass Mutual is also a company with a solid reputation and very few complaints. As a result, it’s an excellent choice for seniors who want coverage with fewer hassles. Plus, getting a policy online is an option, so that works well for anyone who prefers a purely digital experience.

One benefit of choosing Mass Mutual is that there are some no-exam policies available. That can work well for seniors who prefer a hassle-free experience, but these options usually cost more than the alternatives, so keep that in mind.

3. New York Life

At New York Life, seniors can secure term life policies, though how long the coverage lasts may vary depending on a person’s age. Seniors as old as 65 can get 15 or 20-year terms, giving them some flexibility. For seniors no older than 75, there’s a 10-year term option available instead. Coverage amounts begin at $100,000, though they can go up from there.

For whole life, the maximum age for a policy through New York Life is 90. The minimum amount of coverage is $25,000, but policyholders can potentially qualify for a higher amount if they’d like to explore that option.

A drawback to New York Life is that purchasing life insurance policies for seniors online isn’t an option. Still, the company has an excellent reputation and a high rate of customer satisfaction, so using an alternative approach to buy a policy is generally worth the effort.

4. State Farm

State Farm offers term, whole, and no-exam life insurance policies, giving seniors an array of options. Minimum coverage amounts for term life policies are set at $100,000, but you can secure more coverage if you prefer (and qualify). For seniors no older than 65 years of age, 20-year terms are available. Seniors who are as old as 75 can get a 10-year term instead.

The maximum age for whole-life policies can vary depending on the details. However, seniors can get it as long as they’re no older than 80, and the minimum coverage amount can be as low as $10,000, though securing more is potentially an option.

When it comes to customer satisfaction, State Farm consistently ranks incredibly high, and it takes the number one spot in some studies. As a result, it’s a strong choice for seniors who want a positive customer experience and fewer hassles. Just be aware that buying a policy online isn’t an option, but the effort is worthwhile if stellar customer service once the policy is in place is a priority.

5. USAA

While many USAA services are only open to military members, veterans, and their families, that isn’t the case with life insurance through USAA. As long as a senior is a US citizen or permanent resident, they can explore these life insurance options.

USAA has term life policies that seniors as old as 70 can check out, with the available coverage amount ranging from as low as $100,000 to as high as $10 million. Whole life is also an option for seniors up to the age of 85, with coverage amounts ranging from $25,000 on the low end up to $10 million.

One benefit of using USAA is that policyholders can convert term life policies into permanent ones before the initial coverage expires. That can work well for seniors who decide that lifelong coverage is a better fit down the line. USAA also has an excellent reputation when it comes to customer satisfaction and customer service. Just not that online purchasing isn’t an option, but that may not be an issue since the experience is typically positive.

Do you know of any other places to get life insurance for seniors? Have you tried any of the options above and want to tell others about your experience? Share your thoughts in the comments below.

Read More:

  • Considering Life Insurance After 50? All That You Need to Know!
  • Understanding Life Insurance: 9 Tips on How to Choose the Right Plan
  • Best 4 Tips for Starters Looking to Buy Life Insurance
Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance Tagged With: Guardian Life, Mass Mutual, New York Life, State Farm, Think You're Too Old To Get Life Insurance-Think Again: 5 Places to Get Life Insurance For Seniors, USAA

  • « Previous Page
  • 1
  • …
  • 68
  • 69
  • 70
  • 71
  • 72
  • …
  • 95
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework