• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for saving money

The “Just One More” Syndrome: Small Expenses That Are Keeping You Broke

March 3, 2025 by Latrice Perez Leave a Comment

Expenses Coffeee
Image Source: 123rf.com

We’ve all done it—grabbing a coffee on the way to work, adding an extra streaming service “just for one show,” or impulsively ordering takeout because cooking feels like too much effort. These small, seemingly harmless expenses don’t feel like much in the moment, but over time, they add up in ways that can quietly sabotage your financial health. If you’ve ever wondered why your bank balance isn’t growing, “Just One More” Syndrome might be to blame.

Your Daily Coffee Fix Might Be a Silent Budget Killer

A $5 coffee here, a $3 pastry there—it doesn’t feel like much, right? But if you’re making this a habit, the cost quickly balloons. Spending $5 a day on coffee adds up to $150 a month, or $1,800 a year. That’s enough to cover a vacation, knock out a chunk of debt, or boost your emergency fund. While the occasional treat is fine, if you’re hitting the coffee shop every morning without thinking, it may be time to reconsider how much that caffeine habit is truly costing you.

Subscription Creep: The Streaming Services Draining Your Wallet

Netflix, Hulu, Disney+, HBO Max, Spotify—individually, they all seem affordable. But when you add up multiple subscriptions, you could easily be spending over $100 a month on services you barely use. Subscription creep happens when you sign up for “just one more” service, thinking it’s only a few extra dollars, without realizing you’re paying for content you don’t even watch. If you haven’t done a streaming audit recently, now is the time to cut the excess and reclaim that money.

Eating Out and Takeout: The Hidden Drain on Your Budget

Ordering takeout or grabbing fast food feels like a convenient option when life gets busy. But let’s be real—those $15-$20 meals add up quickly. If you’re eating out multiple times a week, you could easily be spending hundreds of dollars a month without realizing it. Cooking at home not only saves money but also allows you to eat healthier. Even cutting back takeout by half could free up money for more important financial goals.

Retail Therapy That Comes Back to Haunt You

Impulse purchases can be sneaky. Whether it’s a “just-because” Amazon order, a sale you couldn’t resist, or a spontaneous shopping spree, these little indulgences can wreck your budget. The thrill of buying something new fades fast, but the dent in your bank account sticks around. If you constantly find yourself saying, “It was only $20,” take a step back and look at how much all those small purchases add up over the month. You might be surprised.

Rideshare Addiction: How Uber and Lyft Are Silently Stealing Your Cash
Ride Share
Image Source: 123rf.com

Hopping into an Uber or Lyft is convenient, but relying on rideshares too often is a financial black hole. At an average of $10-$25 per ride, frequent ridesharing can cost hundreds per month—money that could go toward savings or debt repayment. If you’re using rideshares for trips you could walk, bike, or take public transit for, it’s time to rethink whether convenience is worth the long-term cost.

Grocery Store “Extras” That Destroy Your Budget

You go to the grocery store for milk and bread, but somehow, you leave with $40 worth of snacks, drinks, and random “just-in-case” items. These little extras inflate your grocery bill without you even noticing. The solution? Make a list, stick to it, and avoid grocery shopping when you’re hungry. Your wallet will thank you.

Sneaky Bank Fees That Keep Chipping Away at Your Money

Overdraft fees, ATM charges, and monthly account fees may seem minor, but they’re costing you money unnecessarily. Some banks charge $35 for overdrafts, while ATM fees can add up to $5 per transaction. If you’re paying these sneaky fees regularly, consider switching to a no-fee bank or setting up low-balance alerts to avoid unnecessary charges.

In-App Purchases That Seem Harmless (But Aren’t)

Whether it’s a $2 upgrade on a mobile game, a new filter pack for Instagram, or premium access to an app you barely use, small digital purchases add up fast. These microtransactions don’t seem like much at first, but they can lead to big spending over time. If you’re making frequent in-app purchases, check your digital spending history—you might be shocked by how much you’ve spent.

How to Break Free from “Just One More” Syndrome

Recognizing these small spending habits is the first step toward change. Start by tracking your spending to see where your money is really going—small expenses add up quickly, and seeing them in black and white can be eye-opening. If you’re tempted to buy something unnecessary, use the 24-hour rule: wait a day before making the purchase, and if you still want it, then it’s likely a meaningful expense rather than an impulse buy.

Do you suffer from “Just One More” syndrome? What steps can you take to make the changes you need to stop unnecessary spending? Let us know in the comments below.

Read More:

The ‘Silent Killer’ of Your Budget: 10 Pointless Expenses That Are Keeping You Poor

7 Signs Your Budget Is Running Your Life—and How to Take Back Control

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Budgeting Tagged With: Budgeting Tips, financial habits, Financial Wellness, impulse purchases, saving money, small expenses, unnecessary spending

Millionaire Secrets: 7 Weird Money Habits That Actually Work

March 3, 2025 by Latrice Perez Leave a Comment

Millionaire Secrets
Image Source: 123rf.com

Most people assume millionaires live lavishly, but many wealthy individuals follow unconventional money habits to build and protect their fortunes. Their secret? They don’t think about money the same way the average person does. Instead of spending like they’re rich, they embrace unique strategies that seem odd but are surprisingly effective. If you want to grow your wealth, consider adopting these seven millionaire money habits.

They Avoid Lifestyle Inflation at All Costs

When most people earn more, they immediately upgrade their lifestyle—bigger homes, fancier cars, and expensive vacations. Millionaires resist this temptation and keep their expenses low, even when they can afford more. Many self-made millionaires drive older cars, live in modest homes, and avoid unnecessary luxuries. By maintaining a simple lifestyle, they free up more money to invest and grow their wealth.

They Treat Every Dollar Like an Employee

Instead of thinking of money as something to spend, millionaires view each dollar as an employee that should be working for them. This means they prioritize investing over splurging. They put money into stocks, real estate, and businesses that generate passive income. Every dollar is given a job—whether it’s earning interest, compounding in investments, or funding a future project.

They Set “No-Spend” Days Regularly

Many wealthy people schedule days or even weeks where they spend nothing beyond absolute necessities. This practice helps them stay mindful of their expenses and break unnecessary spending habits. It also forces creativity—finding free entertainment, cooking at home, and using what they already have instead of buying more. This habit builds financial discipline and prevents impulse spending.

They Negotiate Everything

Millionaires don’t just accept the first price they’re given—they negotiate. From real estate deals to credit card interest rates, they challenge prices to maximize savings. Even in everyday purchases, they ask for discounts or perks. While negotiating may feel uncomfortable at first, it can save thousands of dollars over time. If you don’t ask, you’ll never know what savings you might get.

They Read More Than They Watch TV

A surprising habit among millionaires is their dedication to reading. Many successful people, like Warren Buffett and Elon Musk, credit much of their knowledge to reading books. Instead of wasting hours on entertainment, they consume information that helps them grow—financial books, biographies of successful people, and industry news. By learning continuously, they make smarter financial decisions and spot opportunities others miss.

They Buy Quality (But Less Often)

Buy Quality
123rf.com

Rather than chasing trends or buying cheap, millionaires focus on quality purchases that last. They prefer durable goods over disposable ones, saving money in the long run. Whether it’s clothing, appliances, or cars, they research before buying and invest in things that provide long-term value. This prevents constant replacements and reduces wasteful spending.

They Automate Their Savings and Investments

Many millionaires remove the temptation to spend by automating their finances. They set up automatic transfers to savings accounts, retirement funds, and investments before they even touch their money. This “pay yourself first” strategy ensures that they consistently build wealth without relying on willpower. Over time, small automated contributions turn into significant financial gains.

Shift Your Mindset

You don’t need to be a millionaire to adopt these habits—you just need to shift your mindset. By treating money as a tool for wealth-building, resisting lifestyle inflation, and making intentional financial choices, you can start accumulating wealth the same way self-made millionaires do. The key isn’t how much you make—it’s how you manage it.

Do you have any millionaire habits that are helping you to shift your mindset? Are you already on your way to becoming a millionaire? Let us know how you’re doing it in the comments below.

Read More:

The Secrets of Self-Made Millionaire Women: 6 Tips You Can Steal

FireAid Concert Raises a Staggering $100 Million for LA Wildfire Relief—Here’s How It Happened

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: money management Tagged With: budgeting, financial mindset, financial success, millionaire habits, money tips, Personal Finance, saving money, smart investing, Wealth Building

How to Make Banks Pay You Instead of the Other Way Around

February 26, 2025 by Latrice Perez Leave a Comment

Bank Pay You
Image Source: 123rf.com

Most people assume banks are just a place to store money, but the truth is, banks make billions off their customers through fees, interest, and low-yield savings accounts. The good news? You don’t have to be on the losing side of this equation. With the right strategies, you can flip the script and make banks pay you instead of the other way around. Here’s how.

Choose a High-Yield Savings Account

Traditional savings accounts often offer insultingly low interest rates—sometimes as little as 0.01%. Meanwhile, online banks and credit unions offer high-yield savings accounts with interest rates 10 to 20 times higher.

How to make this work for you:

  • Compare different banks and find an account with at least a 4% APY or higher.
  • Avoid savings accounts with monthly maintenance fees.
  • Set up automatic transfers to take advantage of compound interest over time.

Use Cashback and Rewards Checking Accounts

Many banks now offer checking accounts that pay you to use them, often through cashback on debit card purchases or interest-bearing checking accounts.

How to make this work for you:

  • Look for banks that offer 1-3% cashback on debit purchases.
  • Some banks provide interest rates on checking balances—shop around for those offering at least 1-2% APY.
  • Ensure the account doesn’t have high fees that offset your rewards.

Get Rid of Unnecessary Fees

Overdraft fees, ATM withdrawal charges, and maintenance fees quietly eat away at your money. The less you pay in fees, the more cash stays in your pocket.

Try This:

  • Switch to a fee-free checking account that doesn’t charge for overdrafts or minimum balances.
  • Use in-network ATMs to avoid withdrawal fees.
  • Ask your bank to waive fees—many will remove them if you call and ask.

Take Advantage of Bank Sign-Up Bonuses

Sign Up Bonus
Image Source: 123rf.com

Banks often run promotions where they’ll pay you to open an account, with bonuses ranging from $100 to $500. While they may require a direct deposit or a certain balance, these offers can be a quick way to earn extra cash.

Follow These Steps:

  • Research current bank promotions and find one with a low deposit requirement.
  • Read the fine print to ensure you meet the requirements to receive the bonus.
  • Close old accounts that no longer benefit you to keep your finances streamlined.

Invest Through Your Bank’s Brokerage Services

Many banks offer commission-free investment accounts or partnerships with brokerages where you can earn passive income. Instead of leaving your money idle in a low-interest account, investing allows you to grow your wealth.

Take These Steps:

  • If your bank has a brokerage arm, look into low-cost index funds or ETFs.
  • Set up automatic investments so your money works for you without effort.
  • Compare bank brokerage fees—sometimes using an independent brokerage is more cost-effective.

Use Credit Cards with Cashback and Rewards

Banks make money when you carry a credit card balance, but if you use credit wisely, you can earn cashback and rewards without paying interest.

Take These Steps:

  • Get a no-annual-fee cashback credit card and pay off the balance in full every month.
  • Use a card that offers at least 1.5-2% cashback on everyday purchases.
  • Redeem cashback for statement credits, deposits, or travel rewards.

Flip the Banking System in Your Favor

Banks make money off uninformed customers, but by playing the game strategically, you can turn the tables and make them work for you. With high-yield savings, cashback checking, fee elimination, and sign-up bonuses, you can stop paying banks and start getting paid instead. It’s time to make your money work smarter—not harder.

Have you already used some of these techniques to earn money from your bank? Have you learned of other ways to earn from banking? Let us know in the comments.

Read More:

8 Things You Didn’t Know About Digital-Only Banks (And Why They’re the Future)

Traditional Banking vs. Digital Solutions: What is the Future of Overseas Payments?

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Banking & Finance Tagged With: banking tips, cashback rewards, Financial Hacks, high-yield savings, no-fee accounts, Personal Finance, saving money, smart banking

The ‘Silent Killer’ of Your Budget: 10 Pointless Expenses That Are Keeping You Poor

February 25, 2025 by Latrice Perez Leave a Comment

Leaky Budget
Image Source: 123rf.com

You may think you have a solid budget, but small, unnoticed expenses can quietly drain your finances. These silent budget killers don’t always stand out like a big shopping spree or a luxury vacation, but over time, they chip away at your financial goals. The worst part? You probably don’t even realize they’re happening. By identifying these hidden costs, you can take control of your money and start saving more without changing your lifestyle drastically. Here are ten sneaky expenses that could be draining your budget.

Subscription Overload

Streaming services, cloud storage, fitness apps, and subscription boxes may seem inexpensive individually, but they add up fast. Many people forget to cancel trials or keep multiple subscriptions they rarely use. Even that $9.99 monthly fee can total over $100 annually per service. Take inventory of your subscriptions and cancel anything you don’t actively use. Consider rotating between services instead of keeping them all year-round.

Bank Fees You Don’t Notice

Overdraft charges, ATM fees, and account maintenance fees can silently eat away at your money. Some banks charge for paper statements, minimum balance violations, or even inactivity. These costs may seem small, but they add up over time. Review your bank’s fee structure and switch to a fee-free account if possible. Online banks often have fewer charges and better interest rates.

Unused Gym Memberships

Signing up for a gym membership feels like an investment in your health, but if you rarely go, it’s just wasted money. Many gyms make cancellation difficult, hoping you’ll keep paying even if you stop going. Instead of wasting money, consider a pay-per-visit gym or free workout options like home fitness apps and outdoor activities. If you truly value the gym, commit to going regularly to get your money’s worth.

Convenience Fees and Delivery Costs

Food delivery services, convenience store markups, and ride-sharing fees add unnecessary costs to your daily spending. It’s easy to justify a $5 delivery charge here and there, but over time, these costs skyrocket. Cooking at home, planning grocery trips, and using public transport can save you hundreds of dollars per year. Be mindful of when convenience is worth the extra price.

Extended Warranties and Insurance Overload

Retailers often push extended warranties, but most products rarely break within the covered period. Similarly, paying for unnecessary insurance—like excessive rental car coverage—can drain your budget. Before agreeing to extra protection, check if you’re already covered by a manufacturer’s warranty, credit card benefits, or existing insurance policies.

Energy Vampires at Home

Energy Vampires
123rf.com

Everyone has some energy vampires at home. Leaving electronics plugged in, running outdated appliances, or cranking up the heat or air conditioning unnecessarily can spike your utility bills. Even small habits like leaving lights on or overusing space heaters add up. Invest in energy-efficient appliances, unplug unused devices, and use smart thermostats to control costs.

Impulse Shopping and Retail Tricks

Retailers use psychological pricing, limited-time offers, and strategic store layouts to encourage impulse purchases. Ever grabbed something extra at the checkout line? Those small purchases accumulate over time. Shopping with a list, setting a budget, and avoiding emotional spending can help you cut back. Try a “48-hour rule” where you wait before making non-essential purchases.

Coffee and Snacks on the Go

A daily coffee habit or frequent vending machine trips may seem like minor indulgences, but they drain your wallet over time. A $5 coffee each weekday adds up to over $1,200 a year. Making coffee at home, bringing snacks from home, or setting a budget for treats can keep these costs in check.

Unused Gift Cards and Loyalty Points

Billions of dollars in unused gift cards and loyalty points go to waste each year. It’s easy to forget about that $25 gift card in your wallet or the airline miles that could cover a flight. Check your balance regularly and use your rewards before they expire. Selling or trading unwanted gift cards is another way to recoup value.

Late Fees and Interest Charges

Missing payment due dates results in unnecessary fees and higher interest rates on credit cards. Even a single late payment can hurt your credit score. Automate bill payments or set reminders to avoid penalties. Paying off credit card balances in full each month prevents costly interest charges.

Stop the Silent Budget Leaks

A leaky budget can feel like a mystery, but once you spot these hidden costs, you can take back control. By cutting unnecessary expenses, canceling unused subscriptions, and being mindful of everyday spending, you’ll free up more money for the things that truly matter. The key is awareness—once you recognize these financial leaks, you can start plugging them for good.

Do any of these budget leaks resonate with you? Which one has been the biggest budget buster for you? Let’s talk about it below.

Read More:

7 Signs Your Budget Is Running Your Life—and How to Take Back Control

10 Cheap Home Decor items on amazon to Transform Your Space on a Budget

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: budget tips Tagged With: banking fees, budgeting, financial mistakes, hidden expenses, money tips, Personal Finance, saving money, Smart Spending, subscriptions

The $5 Rule: How This One Trick Can Change Your Financial Future

February 25, 2025 by Latrice Perez Leave a Comment

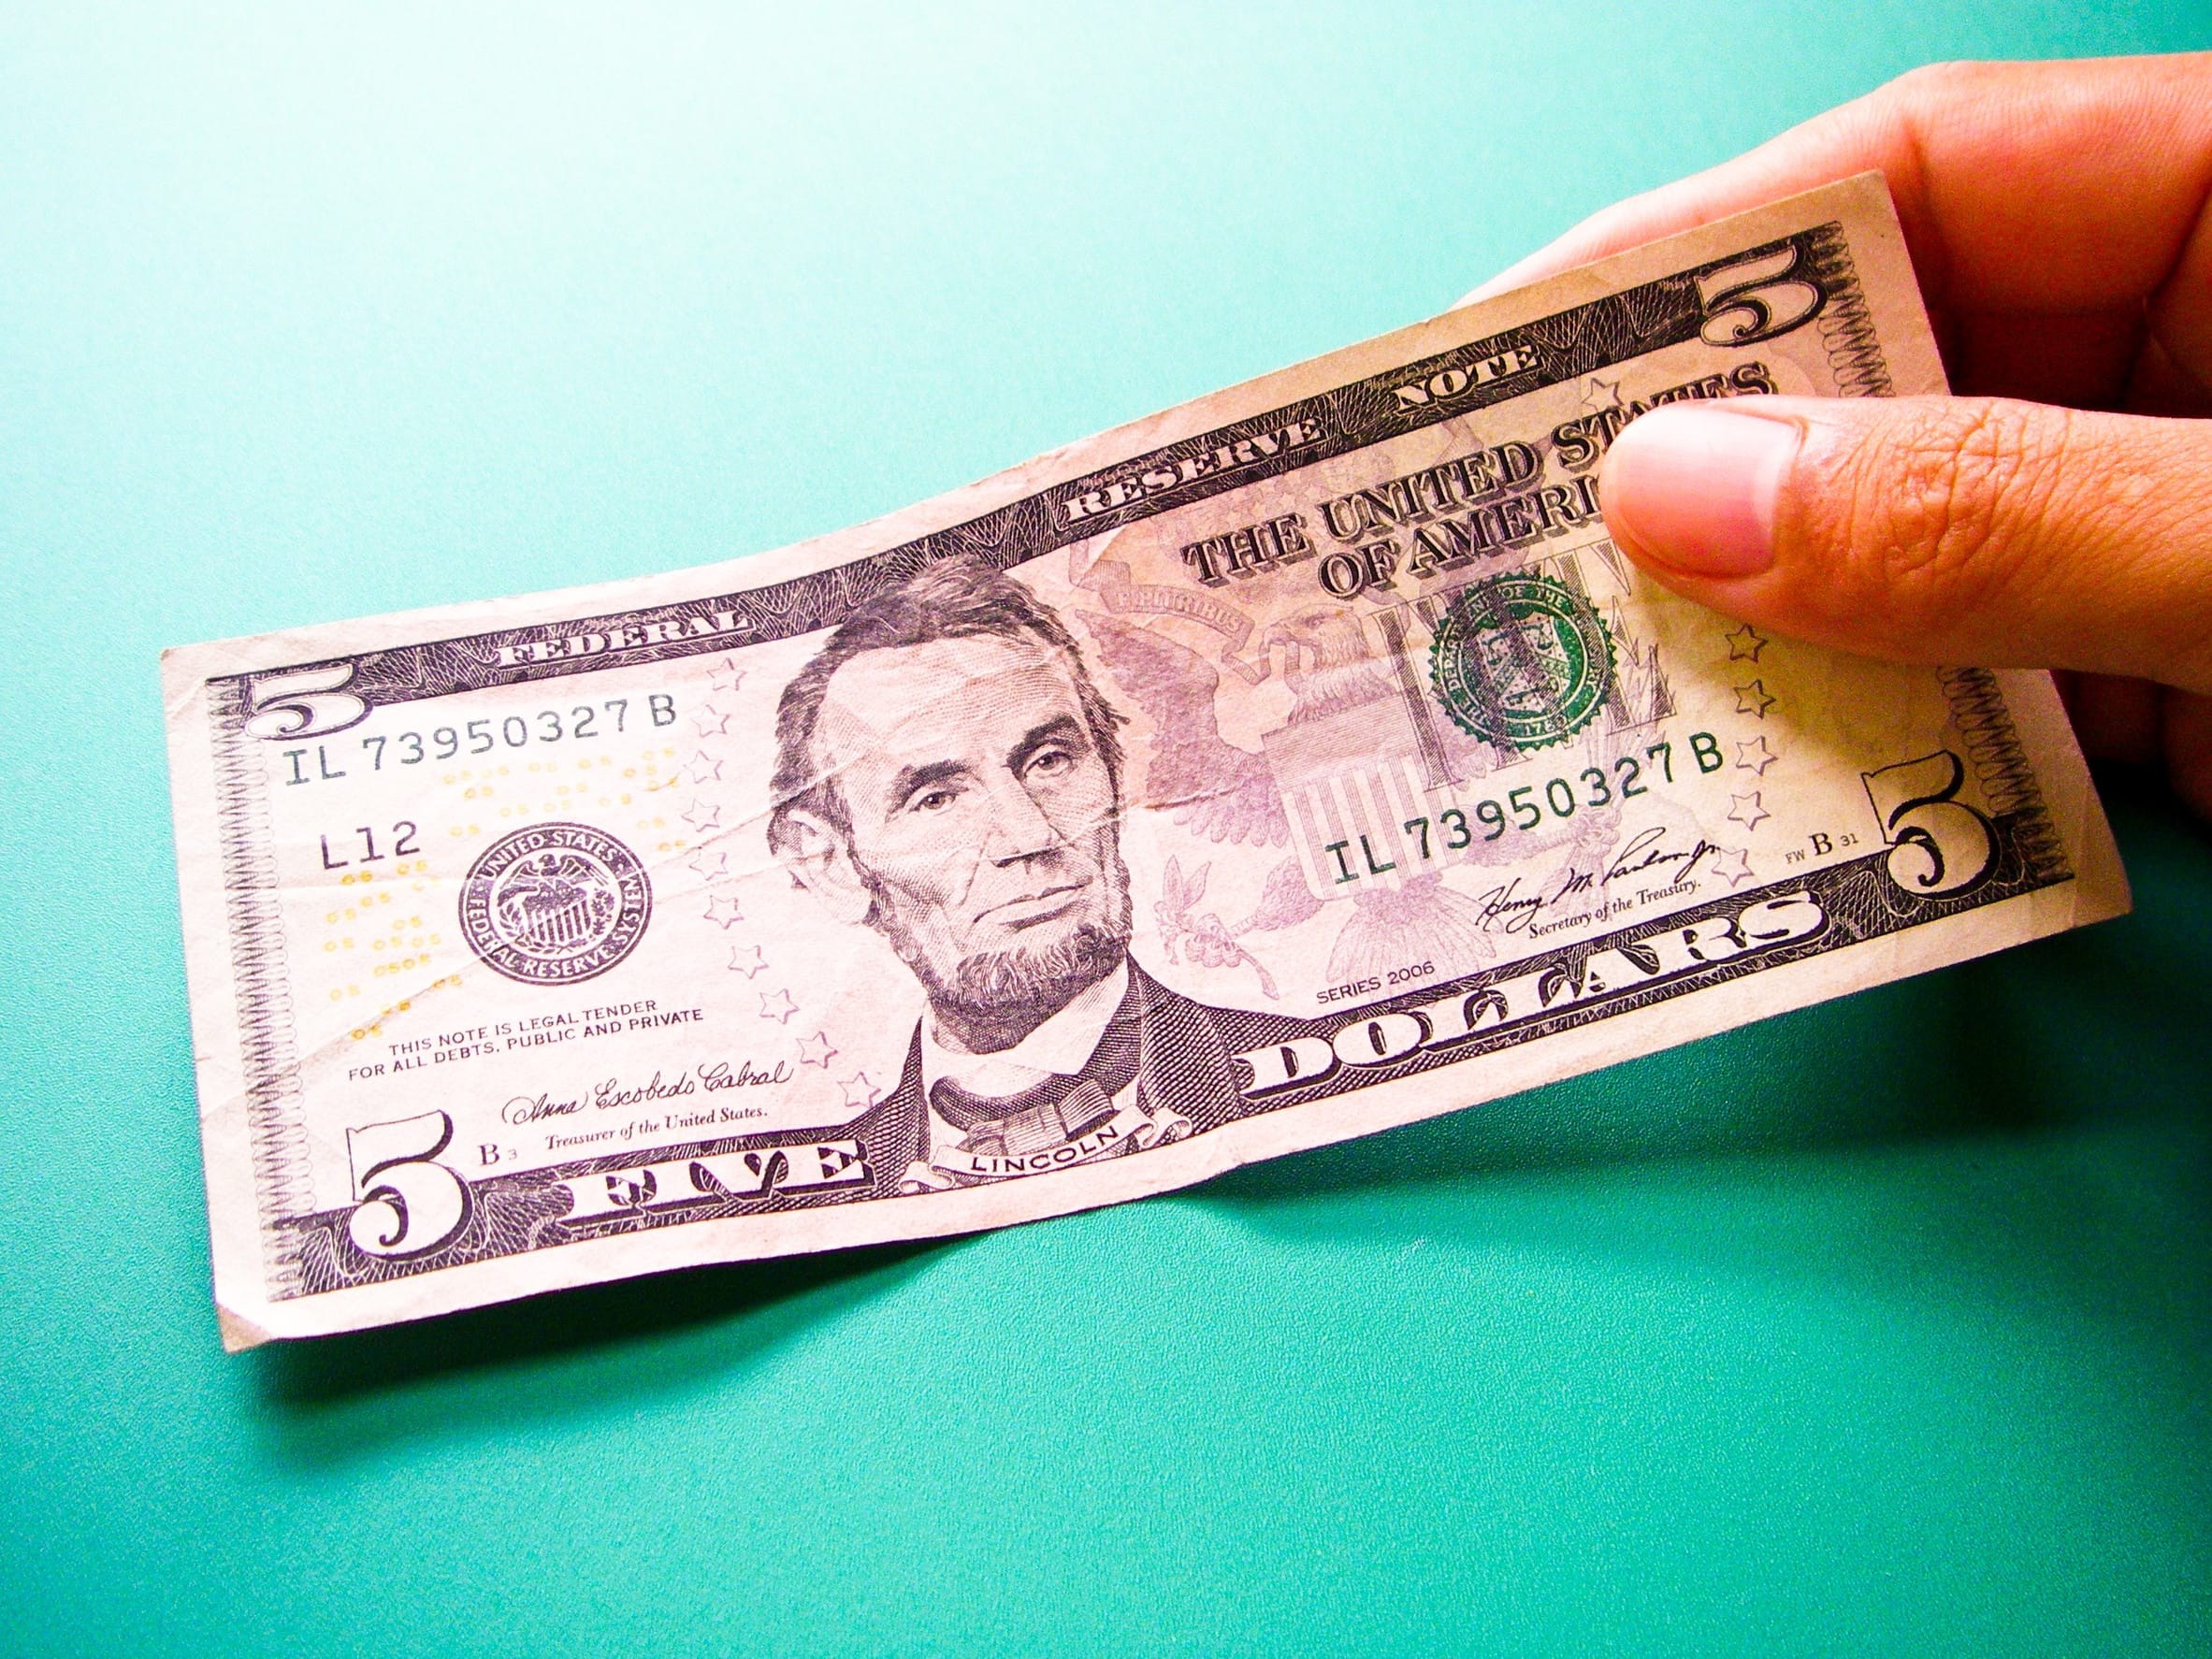
5 dollar bill
Image Source: 123rf.com

Many people struggle with saving money, often feeling overwhelmed by complicated budgeting systems. But what if there was an easy, low-effort way to build wealth? Enter the $5 Rule—a simple trick that has helped countless people grow their savings without stress. It’s an effortless financial habit that anyone can adopt, and the results can be surprisingly powerful.

How the $5 Rule Works

The concept is simple: Every time you receive a $5 bill, you set it aside instead of spending it. Whether you get it as change from a purchase, withdraw cash from an ATM, or receive it as a gift, that bill goes directly into a savings jar or a separate bank account. By consistently following this rule, you’ll be amazed at how quickly the savings add up.

People who use the $5 Rule often find that they accumulate hundreds—or even thousands—of dollars in just a few months. Since $5 bills don’t seem like a lot individually, setting them aside doesn’t feel like a financial burden. Over time, these small amounts create a substantial safety net.

Why the $5 Rule Works

One reason this trick is so effective is that it plays on human psychology. Unlike traditional savings methods that require discipline and budgeting, this method feels more like a fun challenge. Instead of dreading saving money, people enjoy watching their stack of $5 bills grow.

Another advantage is that it removes the temptation to spend. Since $5 bills are earmarked for savings as soon as you receive them, you naturally start handling money more intentionally. Without even realizing it, you become more mindful of your spending habits.

Real-Life Success Stories

Many people who have adopted the $5 Rule have seen incredible results. Some have saved enough for a vacation, while others have built emergency funds without changing their lifestyle drastically.

For example, I’ve been able to save over $3,000 in a year simply by following this rule. I also used it to pay off a credit card balance that had been stressing me out. Another friend of mine saved enough to buy a new laptop without dipping into their regular paycheck.

How to Make It Even More Effective

Save Money
Image Source: 123rf.com

If you want to take the $5 Rule to the next level, consider these variations:

  • Set a specific savings goal – Whether it’s for an emergency fund, a vacation, or a down payment, having a purpose makes it more motivating.
  • Use a dedicated container or account – Keeping your $5 bills separate from your regular spending money prevents temptation.
  • Go digital – If you primarily use cards instead of cash, transfer $5 to a savings account every time you make a purchase. Many banking apps allow for automated small transfers.
  • Get others involved – Turn it into a friendly challenge with your family or friends to stay motivated.

Why This Strategy Beats Traditional Budgeting

Unlike strict budgeting plans that require tracking every penny, the $5 Rule is flexible and effortless. You don’t have to analyze every expense or create a complicated spreadsheet. Instead, it works passively in the background, growing your savings over time without much effort.

This strategy also helps people develop a healthier relationship with money. Instead of feeling deprived, you feel empowered knowing that small actions can lead to big results.

Small Steps, Big Financial Wins

The $5 Rule proves that saving money doesn’t have to be difficult. By making one small change in your daily routine, you can build a financial cushion without feeling the pinch. Whether you use this trick for a rainy day fund, debt repayment, or a fun splurge, the impact is real. Give it a try—you might be surprised at how much you can save with just $5 at a time.

What do you think about this method of saving? Is it something you’re ready to try? If so, let’s talk about it in the comments below.

Read More:

Here’s The 10 Real Reasons Why Millennials Are Saving So Little

11 Pieces of Advice Your Financial Advisor Isn’t Giving You About Retirement Savings

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: budget tips Tagged With: budgeting hacks, easy saving tricks, financial success, Financial Tips, frugal living, money habits, Personal Finance, saving money

“The ‘Spending Freeze’ Challenge: Could You Survive a Month Without Shopping?

February 25, 2025 by Latrice Perez Leave a Comment

Spending Freeze
Image Source: 123rf. com

Cutting out all unnecessary spending for an entire month may sound extreme, but the spending freeze challenge has helped many people reset their financial habits. By committing to spending only on essentials, participants can see where their money usually goes and break free from impulsive buying. The challenge forces you to become more intentional about your finances, helping to build better habits in the long run.

Preparing for a Spending Freeze

Before starting, it is important to set clear rules and define what qualifies as essential spending. Rent or mortgage, utilities, groceries, and necessary transportation costs should be allowed, while dining out, entertainment, and impulse purchases should be cut completely. Creating a list of must-pay expenses and identifying potential problem areas will make it easier to stick to the plan.

Finding Free Alternatives

One of the biggest obstacles during a spending freeze is finding ways to stay entertained without spending money. Instead of going to the movies or dining out, consider free activities such as hiking, visiting local museums on free-admission days, or hosting a game night at home. Using this time to explore free hobbies can help make the challenge more enjoyable while reinforcing the idea that entertainment does not have to come with a price tag.

Meal Planning to Avoid Extra Costs

Meal Planning
Image Source: 123rf.com

Food is one area where people often overspend, especially on takeout and dining out. Planning meals ahead of time and cooking at home can help cut food costs significantly. Using pantry staples, making meals in bulk, and getting creative with ingredients you already have will prevent unnecessary grocery trips and reduce food waste. A well-thought-out meal plan can make a spending freeze more manageable without sacrificing good meals.

Identifying Spending Triggers

A month-long spending freeze provides an opportunity to recognize what triggers unnecessary purchases. Some people shop out of boredom, stress, or habit rather than actual need. Tracking spending habits and noting what situations lead to impulse buying can help break these cycles. Finding alternative ways to cope, such as exercising or engaging in a productive hobby, can reduce reliance on shopping for emotional reasons.

The Lasting Benefits of a Spending Freeze

Although the challenge only lasts for a month, the lessons learned can have long-term financial benefits. Many participants become more conscious of their spending habits and find that they enjoy living with less. The money saved during the freeze can be used to pay off debt, build an emergency fund, or invest in future financial goals. By successfully completing a spending freeze, you can gain better control over your money and develop financial discipline that lasts beyond the challenge.

Do you think you could go a month without spending any money? What do you think you’d miss the most? Let us know in the comments below.

Read More:

10 ‘Bargain’ Online Shopping Sites That Could Drain Your Wallet

Money-Saving Tricks for Online Shopping

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Personal Finance Tagged With: breaking spending habits, Budgeting Tips, Financial Discipline, frugal living, no spend challenge, Personal Finance, saving money, spending freeze

7 Signs Your Budget Is Running Your Life—and How to Take Back Control

February 4, 2025 by Latrice Perez Leave a Comment

Budget
Image Source: 123rf.com

When it comes to personal finance, having a budget is essential. It helps you plan, save, and ensure you’re making the most of your money. But if you’re not careful, your budget can take on a life of its own, controlling your decisions rather than guiding them. Sometimes, a budget can go from being a helpful tool to a source of stress and limitation. If you feel like your budget is running your life, it might be time to reassess and take back control. Here are seven signs that your budget may be overstepping its bounds, and what you can do to regain your financial freedom.

1. You’re Constantly Stressing About Every Dollar

While budgeting is meant to give you peace of mind, if you find yourself stressing about every single dollar, it might be a sign that your budget is becoming too rigid. If every purchase feels like a mini-crisis or you’re afraid to spend on anything that isn’t “essential,” your budget might not be serving you the way it should.

Financial stress can take a toll on your mental health, and it’s important to remember that a budget should support your goals, not make you anxious. To take back control, try adjusting your categories to allow for some flexibility, like including “fun money” or an “emergency fund” to cushion life’s little indulgences. Your budget should work with you, not against you.

2. You’re Avoiding Social Events Due to Money Concerns

If you’re saying “no” to invitations or skipping social events because you’re worried about how they’ll impact your budget, that’s a red flag. A well-balanced budget should allow for occasional fun and socializing—it’s a part of life! By denying yourself experiences, you risk not just overspending but also missing out on important connections and memories. Revisit your budget and see where you can allocate funds for socializing or entertainment. If your budget is too restrictive, it might be time to adjust your priorities to allow for a healthier balance between saving and enjoying life.

3. You’re Sacrificing Necessities to Stick to Your Budget

Budgets are meant to help you manage your money, but if you’re cutting back on basic needs to stick to your budget, something is wrong. Skimping on essentials like groceries, health care, or housing can lead to bigger problems down the line. If your budget is making you sacrifice your well-being, it’s time to rethink it. Instead of eliminating crucial expenses, reallocate funds from less important categories or reduce discretionary spending. A healthy budget allows you to balance short-term needs with long-term goals, so don’t let it push you into unhealthy compromises.

4. You’re Focusing Too Much on the Small Stuff

While it’s important to track your spending, obsessing over minor expenses like a coffee here or a snack there can keep you from seeing the bigger picture. If you’re too focused on small expenditures, you might be missing out on making bigger, more impactful financial decisions. When you’re so focused on trimming the little things, you might overlook larger opportunities for saving or investing. To regain control, shift your focus to bigger financial goals—like paying off high-interest debt or building an emergency fund—while still being mindful of unnecessary spending. This approach will help you avoid getting lost in the weeds and allow you to see your progress more clearly.

5. You Feel Guilty Every Time You Spend Money

If you feel guilty every time you make a purchase, no matter how small, it’s a sign that your budget may be too restrictive. Feeling guilty can lead to unhealthy financial behaviors, like over-saving or avoiding necessary purchases. A good budget allows for both saving and spending, helping you make informed decisions without guilt. If guilt is creeping into your spending habits, it’s time to reevaluate your budget. Try to set aside a designated amount for guilt-free spending—this way, you can enjoy life while still staying on track with your financial goals.

Stop Saving Money
Image Source: 123rf.com

6. You’ve Stopped Saving for the Future

One of the key purposes of a budget is to help you save for the future. However, if your budget is so tight that you’re unable to contribute to savings, you might be overdoing it. Saving for retirement, an emergency fund, or a big purchase should still be a priority, even if it’s just a small amount each month. Instead of feeling like your budget is forcing you to give up your future financial goals, look for areas where you can cut back to reallocate funds into savings. A successful budget should allow you to live well today while preparing for tomorrow.

7. You Feel Like You Have No Room to Breathe Financially

The ultimate sign that your budget is controlling you is feeling like you can’t breathe financially. If your finances feel suffocating, you’re likely overshooting your goals or being too strict. While having a goal to be financially responsible is great, a budget that makes you feel trapped isn’t doing its job. Take a step back and adjust your budget to allow for more flexibility and breathing room. Look at areas where you can give yourself permission to relax without abandoning your financial goals entirely.

There’s Room For Improvement

If you recognize any of these signs in your current budget, don’t panic—there’s plenty of room for improvement. A budget should empower you to reach your financial goals without causing stress. By making small adjustments, you can create a healthier balance between saving, spending, and living freely. Take back control and make your budget work for you, not the other way around.

Have you ever felt like you were no longer controlling your money because of your budget? What changes did you make to get more control and still save? Let us know in the comments below.

Read More:

Budgeting for One: Smart and Fun Ways to Manage Your Finances Solo

Budgeting For Irregular Income: Freelancers And Gig Workers

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: budget tips Tagged With: budgeting, Debt Management, financial control, financial freedom, financial goals, Financial Health, money management, Personal Finance, saving money, spending tips

10 Bad Ideas for Preventing Unnecessary Spending in Your Family

January 17, 2025 by Latrice Perez Leave a Comment

Senior man holding of dollars
Image Source: 123rf.com

Managing family finances is no small feat, and it’s easy to fall into traps that seem like good ideas but end up doing more harm than good. Preventing unnecessary spending requires thoughtful strategies, not shortcuts that can backfire. Understanding what is not a good way to prevent unnecessary spending is key to making smarter choices. Let’s explore ten bad ideas for curbing expenses that could leave your family feeling more stressed and less financially secure.

1. Cutting Out All Entertainment

Eliminating entertainment entirely might seem like an easy way to save money, but it often leads to burnout and frustration. Families need affordable ways to relax and bond, and cutting this out can create resentment. Instead of canceling everything, look for low-cost or free activities, like movie nights at home or local community events. Balance is key to keeping morale high while sticking to a budget. Depriving your family of all fun is counterproductive in the long run.

2. Ignoring Budgeting Tools

Thinking you can manage your finances without a budget is a recipe for disaster. Budgeting apps and tools help track spending and identify problem areas, ensuring you know what is not a good way to prevent unnecessary spending. Avoiding these tools often leads to overspending and financial surprises. Invest time in setting up a simple budget to see where your money is going. A little effort upfront can save significant stress later.

3. Making Everything a DIY Project

While DIY projects can save money, taking on everything yourself can be time-consuming and stressful. Some tasks, like home repairs or car maintenance, may require expertise that you don’t have. Attempting these projects without proper skills can lead to costly mistakes. Focus on DIY projects where you’re confident and leave complex tasks to professionals. Knowing when to spend on expert help is a smart financial move.

4. Skipping Regular Maintenance

Auto mechanic working in garage. Repair service.
Image Source: 123rf.com

Avoiding routine maintenance to save money is a classic false economy, and it exemplifies what is not a good way to prevent unnecessary spending. Ignoring minor repairs for your car, home, or appliances can lead to bigger, costlier problems down the road. For example, skipping oil changes might save you $50 today but cost you thousands in engine repairs later. Schedule regular check-ups and upkeep to prevent expensive surprises. A proactive approach saves money in the long term.

5. Relying on Sales Alone

Waiting for sales to buy everything might seem smart, but it can lead to impulse purchases and overspending. Sales often tempt families to buy items they don’t need simply because they’re discounted. Instead, focus on buying only what’s on your planned list, regardless of sales. Strategic shopping means sticking to your needs, not your whims. Don’t let discounts derail your financial goals; knowing what is not a good way to prevent unnecessary spending will help you stay on track.

6. Eliminating Emergency Funds

Some families think they can cut costs by skipping an emergency savings fund, but this is a dangerous idea. Life is unpredictable, and unexpected expenses like medical bills or car repairs can wreak havoc on your finances. Without a safety net, you may end up relying on high-interest credit cards or loans. Prioritize building an emergency fund, even if you can only save a small amount at a time. Financial security starts with being prepared.

7. Buying Cheap Instead of Quality

Opting for the cheapest option might save money initially, but it often leads to higher costs over time. Low-quality items may wear out or break faster, requiring frequent replacements. Investing in durable, high-quality products can save money in the long run. This applies to everything from clothing to household appliances. Make thoughtful purchases that balance cost and value.

8. Canceling Insurance Policies

Skipping insurance coverage to cut costs is a high-risk strategy. Whether it’s health, home, or car insurance, being uninsured can lead to financial disaster if something goes wrong. Instead of canceling, review your policies to ensure you’re not overpaying for unnecessary coverage. Shop around for better rates, but never leave yourself vulnerable by going uninsured. Peace of mind is worth the expense.

9. Implementing Strict No-Spending Rules

Banning all discretionary spending might sound like a great way to save, but it can backfire by creating feelings of deprivation. Family members may become frustrated and rebel against the rules, leading to bigger financial conflicts. Instead, set realistic spending limits and allocate some funds for enjoyable activities. A balanced approach is more sustainable and helps everyone stay on board.

10. Overusing Credit Cards for Rewards

Using credit cards to earn rewards can be beneficial, but overspending to chase points is a common pitfall. Families often justify unnecessary purchases because they earn cashback or travel miles. This behavior can lead to mounting debt that outweighs any rewards earned. Use credit cards responsibly and pay off balances in full each month. Remember, rewards are only worthwhile if they don’t lead to financial strain.

Avoiding Financial Pitfalls

Preventing unnecessary spending requires smart strategies and open communication within your family. Avoid these bad ideas and instead focus on practical, sustainable approaches to managing your finances. Your family can achieve greater financial security by working together, staying mindful of your goals, and understanding what is not a good way to prevent unnecessary spending.

Have you encountered any of these bad ideas in your family’s financial journey? Share your experiences in the comments below. Don’t forget to share this article with friends and family to help them avoid these common mistakes.

Read More:

  • Here Are 5 Books That Everyone Should Read to Improve Their Financial Literacy
  • 12 Financial Hacks to Beat Emotional Spending and Save Big!
Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: budget tips Tagged With: bad financial habits, Budgeting Tips, family finances, Planning, saving money, unnecessary spending

Budgeting for One: Smart and Fun Ways to Manage Your Finances Solo

October 18, 2024 by Latrice Perez Leave a Comment

fun things to do alone
123rf

Managing your finances on your own can be a challenge, but it also opens up a great opportunity for creativity and personal growth. Whether you’re single, living alone for the first time, or just prefer a more independent lifestyle, there are many smart and fun ways to handle your budget. This article explores how to make the process enjoyable with activities and strategies that are both effective and engaging.

Embrace Tech to Track Your Spending

Utilizing technology is a fantastic way to manage your finances solo. Apps like Mint and You Need a Budget (YNAB) can make tracking your spending almost effortless. These tools not only help you keep a close eye on where your money goes but also provide insights into your spending patterns. This understanding can help you make smarter choices and find more fun things to do alone that don’t break the bank.

Set Goals That Excite You

Goal setting is crucial when you’re budgeting for one. Think about what you truly want to save for, whether it’s a dream vacation, a new gadget, or a comfortable retirement. Make these goals visual: create a vision board or use an app to track your progress towards these dreams. Seeing your goals laid out visually can motivate you to manage your funds wisely and allow you to enjoy fun things to do alone that enrich your life.

Learn to Cook Exciting New Dishes

Cooking for one doesn’t have to be mundane. It can be one of the most fun things to do alone, allowing you to explore new cuisines and improve your culinary skills without the pressure of cooking for others. Try challenging yourself to make dishes from different cultures each week. Not only will this make mealtime an adventure, but buying groceries with specific dishes in mind can also help you stick to your budget.

Invest in Experiences, Not Things

Spending money on experiences rather than material items can lead to greater personal satisfaction and happiness. Consider using part of your budget to try new hobbies or attend workshops that interest you. Whether it’s a pottery class or a solo travel adventure, experiences can enrich your life in ways that objects cannot. This approach also makes looking for fun things to do alone both a budgeting strategy and a lifestyle choice.

Make Budgeting a Regular Retreat

Turn your budgeting sessions into a fun, relaxing ritual. Set aside time each week to review your finances while enjoying a favorite coffee or treat. This not only makes the process more enjoyable but also ensures that you stay on top of your financial health. Make these moments a blend of productivity and pleasure, reinforcing that managing money can be one of the rewarding fun things to do alone.

Thrive Financially On Your Own Terms

Managing your finances solo does not have to be a tedious chore. By incorporating fun activities into your budgeting process and seeking out enjoyable solo experiences, you can make financial management a fulfilling part of your independent lifestyle. Embrace these strategies to maintain control over your finances while enjoying a rich and engaging life on your own terms.

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: budget tips Tagged With: budgeting for one, financial management, fun things to do alone, managing finances alone, Personal Finance, saving money, solo activities, solo budgeting tips

Ready to Take Control of Your Finances? Start with These 10 Fun Activities!

October 11, 2024 by Latrice Perez Leave a Comment

money management activities for adults
123rf

Taking control of your finances doesn’t have to be a drudgery. With the right money management activities for adults, you can transform your financial habits while having fun. These 10 engaging activities are designed not only to educate but also to entertain, helping you to build a stronger, more positive relationship with your money. Let’s dive into some creative ways to enhance your financial literacy and stability.

Host a Budgeting Dinner Party

Combine socializing with budgeting by hosting a dinner party where discussions revolve around money management strategies. Each guest can bring a dish and their favorite budgeting tip to share. This collaborative environment encourages learning from each other’s experiences and can lead to discovering new ways to save or invest. It’s a relaxed setting to discuss financial goals and challenges without the pressure.

Play Financial Board Games

money management activities for adults
123rf

Board games like Monopoly or The Game of Life can highlight financial principles in a playful, engaging manner. You can also find games specifically designed to enhance financial understanding and decision-making skills. These games teach critical aspects of money management such as investing, saving, and emergency planning in a fun, competitive way. Playing regularly with friends or family makes learning about finances an enjoyable routine.

Join a Book Club Focused on Finance

Start or join a book club with a focus on financial literacy books. Reading titles like “Rich Dad Poor Dad” or “The Total Money Makeover” and discussing them can provide deep insights and different perspectives on personal finance. This not only builds your knowledge but also keeps you motivated and accountable. It’s a great way to tackle complex financial concepts in a supportive group setting.

Create DIY Financial Art

Visualize your financial goals by creating DIY art projects that represent your aspirations, such as dream boards or savings trackers. This creative activity makes the abstract concept of financial planning more tangible and personal. You can use this as a daily reminder of your financial targets and as a motivating factor to continue pushing towards them. Plus, it adds a personalized touch to your home decor!

Attend a Finance Workshop

Look for interactive workshops or seminars in your area that focus on money management activities for adults. These sessions often include hands-on activities and group discussions that make learning dynamic and engaging. Attending these workshops can also help you network with like-minded individuals who are also looking to improve their financial health. It’s a practical way to gain valuable advice and new strategies.

Plan a No-Spend Weekend Challenge

Challenge yourself with a no-spend weekend. Plan activities that require no money, such as hiking, visiting free museums, or a movie night at home. This not only saves money but also sparks creativity in finding free entertainment options. It’s a fun challenge that can lead to more mindful spending habits.

Develop a Financial Vision Board Online

Use online platforms to create a digital financial vision board. Include your long-term financial goals, inspirational quotes, and milestones. This activity helps keep your financial aspirations in clear view and can be easily updated as your goals evolve. It’s a modern take on visualizing and achieving your financial dreams.

Try a Money Management App Challenge

Download a budgeting or money management app and set a challenge for yourself or with friends to save a certain amount of money within a set period. These apps often include fun features like savings goals, budgeting tools, and spending trackers. Competing against friends or tracking your progress makes it an engaging way to improve your financial habits.

Organize a Swap Meet

Organize a community swap meet where people can trade items like books, clothes, and other goods without spending money. This promotes a sense of community, reduces waste, and helps everyone save money. It’s an enjoyable way to declutter and find new treasures without impacting your wallet.

Participate in a Financial Webinar

Enroll in a financial webinar that offers interactive, engaging content on managing personal finances. Many webinars are led by financial experts and provide actionable tips in a live, interactive setting. This can be a great way to learn advanced money management techniques and ask real-time questions from financial professionals.

Your Financial Fun Journey

Engaging in these fun money management activities for adults can revolutionize the way you handle your finances. By incorporating enjoyment into your financial education, you’re more likely to stick with good habits and make informed decisions. Start with one or two activities and gradually incorporate more into your routine as you grow more comfortable and skilled at managing your finances.

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: budget tips Tagged With: budgeting, financial education, financial literacy, money management activities for adults, Personal Finance, saving money

  • « Previous Page
  • 1
  • …
  • 19
  • 20
  • 21
  • 22
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework