• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for emergency savings

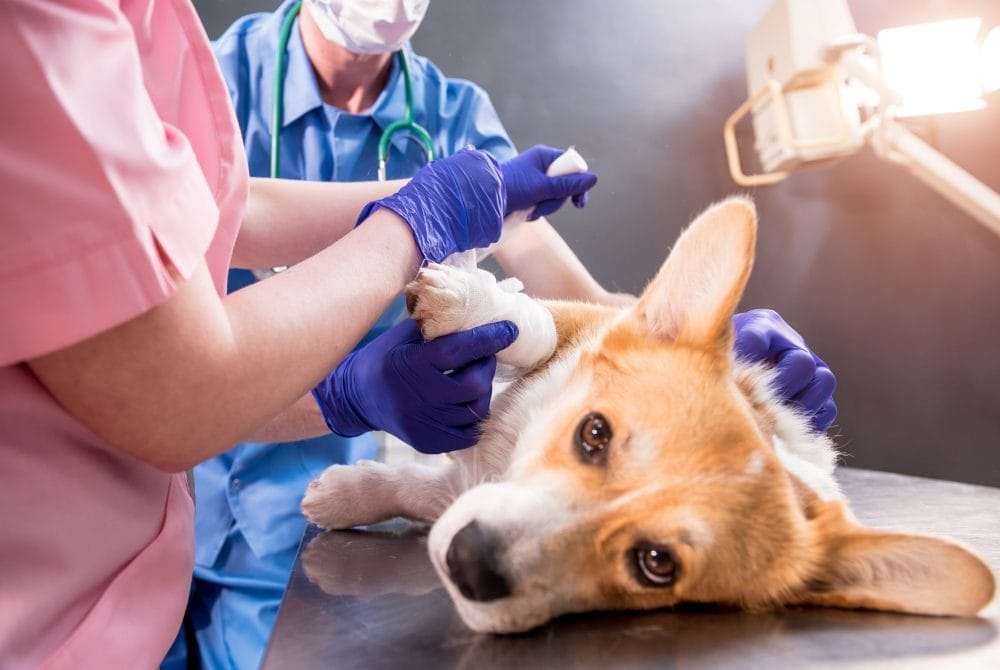
Could A Pet’s Surgery Push You Into Debt

September 26, 2025 by Catherine Reed Leave a Comment

Could A Pet’s Surgery Push You Into Debt
Image source: 123rf.com

For many families, pets are more than companions—they’re part of the family. But when a pet’s surgery becomes necessary, the emotional stress often collides with a painful financial reality. Veterinary procedures can cost thousands of dollars, sometimes due upfront, and pet owners may feel cornered between debt and their animal’s health. This dilemma raises an important question: how can you protect your finances without compromising your pet’s well-being? Let’s explore the hidden costs, practical steps, and strategies to prevent a pet’s surgery from wrecking your financial stability.

1. Why Veterinary Bills Can Skyrocket

The cost of a pet’s surgery isn’t just about the operation itself. Expenses often include pre-op bloodwork, anesthesia, hospitalization, follow-up visits, and medications. When combined, these elements can quickly climb into the thousands, especially if specialized care or emergency services are required. Unlike human healthcare, most pet procedures don’t have insurance subsidies or employer-backed plans to soften the blow. Understanding these factors helps you anticipate the true scope of what you might face if your pet requires surgery.

2. Emergency Timing Makes It Worse

One of the hardest parts of a pet’s surgery is that it usually comes without warning. Emergency care carries a higher price tag because of urgent staffing, specialized equipment, and around-the-clock monitoring. These circumstances often force pet owners into snap financial decisions, sometimes leading to high-interest credit card use or personal loans. Even if you have a savings cushion, emergencies can drain it faster than you expect. Being aware of the emergency premium helps you plan for the unplanned.

3. Financing Options Aren’t Always Friendly

When faced with the immediate cost of a pet’s surgery, many owners turn to financing plans offered by veterinary clinics. While these can provide instant relief, they often come with high interest rates or deferred interest penalties if balances aren’t paid off on time. Pet-specific credit cards and payment programs can seem appealing but may lock you into unfavorable terms. Exploring all financing details before committing is crucial to avoid compounding the financial strain. A quick decision in a stressful moment can turn into long-term debt.

4. Pet Insurance Can Make a Difference

One way to buffer the financial impact of a pet’s surgery is pet insurance. Policies vary widely, but many cover accident-related procedures, some chronic illnesses, and even certain surgeries. The catch is that you need to sign up before a crisis occurs, as pre-existing conditions are usually excluded. Monthly premiums may feel like an added expense, but in the long run, they can significantly reduce the blow of an unexpected procedure. Insurance is worth exploring if you want a layer of protection between your wallet and surprise vet bills.

5. Savings Specifically for Pets

Another smart move is creating an emergency savings fund just for pet care. Setting aside even a small monthly amount ensures you have resources earmarked for your animal’s health. This strategy avoids dipping into broader household savings or retirement accounts during a crisis. A pet’s surgery may still be costly, but having a dedicated fund provides peace of mind. Treating it like any other financial goal helps you stay prepared without adding to your debt load.

6. Hidden Costs After Surgery

Even when you manage to pay for a pet’s surgery, the expenses don’t stop at the operating table. Post-operative care can involve specialized diets, ongoing medications, physical therapy, or additional checkups. These recurring costs add up over time, often catching families off guard. If you only plan for the initial procedure, you may underestimate the long-term financial impact. Preparing for recovery-related costs is just as important as paying for the surgery itself.

7. Asking About Alternatives

Sometimes the best way to manage the financial burden of a pet’s surgery is to ask your vet about alternatives. In certain cases, less invasive treatments or phased approaches may provide comparable outcomes at lower costs. Veterinarians may also know about nonprofit programs, charitable funds, or teaching hospitals offering reduced rates. Being proactive about discussing your options can open doors you didn’t realize existed. It can make the difference between sinking into debt or finding an affordable solution.

The Takeaway: Balancing Love and Finances

A pet’s surgery can be a heart-wrenching experience, not only emotionally but financially. While no one likes to think about the possibility of their furry friend needing a costly procedure, preparing in advance helps you stay out of unnecessary debt. Whether it’s through pet insurance, savings, or exploring alternative treatments, having a plan reduces stress when emergencies strike. At the end of the day, it’s about finding the balance between protecting your finances and giving your pet the care they deserve. Thoughtful preparation can ensure you don’t have to choose between the two.

Have you ever faced a big vet bill for your pet? How did you handle the cost of a pet’s surgery without jeopardizing your finances? Share your story in the comments.

What to Read Next…

6 Financial Risks Nobody Tells You About Pet Ownership

10 Little-Known Costs That Appear With Aging Parents

Pets Over People: 6 Financial Reasons People Are Choosing Dogs Over Children

7 Strange Truths About Middle-Class Spending Habits

The Financial Advice That Works—But Almost No One Follows

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Pets Tagged With: emergency savings, financial planning for pets, pet debt, pet insurance, pet’s surgery, veterinary bills

10 Financial Dangers of Skipping Emergency Funds

September 20, 2025 by Catherine Reed Leave a Comment

10 Financial Dangers of Skipping Emergency Funds
Image source: 123rf.com

Life has a way of throwing curveballs when you least expect them, and without a financial cushion, those surprises can quickly spiral into chaos. From job loss to medical bills, emergencies often strike at the worst possible time. Yet many households overlook the importance of saving for the unexpected, convincing themselves they’ll handle problems when they come. The truth is that skipping emergency funds leaves you vulnerable to debt, stress, and financial setbacks that can take years to fix. Here are ten major risks of neglecting this crucial safety net.

1. Immediate Dependence on Credit Cards

When emergencies strike and no savings exist, credit cards often become the first line of defense. High interest rates make even small balances balloon into long-term debt. Families who rely on credit cards in a crisis often pay far more than the original expense. What could have been manageable with an emergency fund becomes a financial burden lasting years. Skipping emergency funds is one of the fastest ways to rack up costly credit card debt.

2. Risk of Losing Housing Stability

Unexpected expenses like a sudden layoff or medical emergency can make rent or mortgage payments difficult. Without a backup fund, falling behind on housing costs becomes a real possibility. Missed payments put renters at risk of eviction and homeowners at risk of foreclosure. Housing instability creates long-lasting damage to financial and emotional well-being. Skipping emergency funds leaves families vulnerable to losing the roof over their heads.

3. Derailing Retirement Savings

Without emergency savings, people often raid their retirement accounts during crises. This creates immediate penalties and taxes while also reducing long-term growth. Skipping contributions or making early withdrawals sets retirement plans back by years. Many who take this route struggle to catch up. Neglecting emergency funds can quietly erode your future security by forcing you to tap into retirement too soon.

4. Missed Opportunities for Financial Growth

Emergencies don’t just create expenses—they also prevent opportunities. Without savings, families can’t take advantage of chances like buying a home at a good price or investing during a market dip. Instead of building wealth, they remain stuck playing financial catch-up. Having a cushion provides flexibility to seize opportunities when they appear. Skipping emergency funds keeps you locked out of chances to move forward.

5. Increased Stress and Mental Strain

Financial insecurity weighs heavily on mental health. When every unexpected expense feels like a crisis, stress levels skyrocket. This strain can affect work performance, relationships, and overall well-being. Having an emergency fund reduces anxiety by offering peace of mind. Skipping emergency funds turns everyday challenges into overwhelming burdens.

6. Damage to Credit Scores

Late payments caused by a lack of savings quickly lower credit scores. A single missed bill can linger on a credit report for years, raising borrowing costs in the future. Poor credit impacts everything from loan approvals to insurance rates. Recovering from damaged credit is slow and frustrating. Skipping emergency funds often leads to a chain reaction that destroys financial credibility.

7. Dependence on Loans and Borrowing

Without cash reserves, families often rely on payday loans, personal loans, or borrowing from friends and family. These options may provide quick relief but come with high interest or strained relationships. Borrowing repeatedly to cover crises creates a cycle of dependency that’s difficult to escape. Over time, this erodes financial independence. Skipping emergency funds ensures you remain dependent on others when trouble arises.

8. Disruption of Daily Life Expenses

Emergencies don’t pause regular bills. Skipping emergency funds means that when car repairs or medical bills appear, daily expenses like groceries, childcare, and utilities take a hit. Families are forced to juggle which bills to pay, often falling behind in multiple areas. This juggling act creates instability that takes months to repair. Without a cushion, one unexpected cost can disrupt your entire budget.

9. Limited Career Flexibility

Workers without savings often feel trapped in jobs they dislike because they can’t afford a gap in income. Skipping emergency funds removes the freedom to change careers, take time off for education, or start a business. Fear of financial ruin keeps people stuck in roles that don’t serve them. Having a cushion offers the ability to make choices for long-term growth. Without it, options are painfully limited.

10. Long-Term Financial Setbacks

Skipping emergency funds means that every setback pushes your goals further away. Paying off debt, saving for a home, or planning for retirement all become harder when crises wipe out progress. Instead of moving forward, families find themselves starting over repeatedly. The long-term cost of never building a safety net is lost time and delayed dreams. A strong emergency fund keeps progress steady even when life is unpredictable.

Your Future Self Will Thank You for Saving

Emergency funds are not just about money—they’re about freedom, stability, and peace of mind. Skipping emergency funds puts you at the mercy of debt, stress, and instability that ripple through every area of life. By setting aside even small amounts consistently, you protect yourself from crises and give your future self a priceless gift. The smartest financial decision you can make today is to prepare for tomorrow’s unknowns.

Do you think skipping emergency funds is the most common financial mistake families make? Share your perspective in the comments below.

What to Read Next…

  • 10 Money Moves That Look Smart but Lead to Regret
  • 7 Strange Truths About Middle-Class Spending Habits
  • Why Do Some People Refuse to Budget Until It’s Too Late
  • 6 Financial Risks That Appear After Moving in With Someone
  • Why Do People Get Trapped by “Buy Now Pay Later” Schemes
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Personal Finance Tagged With: Debt Management, emergency savings, money tips, Personal Finance, Planning, saving money, skipping emergency funds

7 Strange Truths About Middle-Class Spending Habits

September 18, 2025 by Catherine Reed Leave a Comment

7 Strange Truths About Middle-Class Spending Habits
Image source: 123rf.com

The middle class is often viewed as the backbone of the economy, but their financial choices can be surprising. From splurging on conveniences to juggling debt while still prioritizing luxuries, the way the middle class spends doesn’t always match the narrative of careful budgeting. These patterns reveal not just financial behavior but also cultural values, lifestyle pressures, and aspirations for upward mobility. Looking at these strange truths about middle-class spending habits can help shed light on why so many families feel stuck despite earning decent incomes.

1. Dining Out Eats Up a Big Chunk of Budgets

One of the strangest middle-class spending habits is how much money goes toward dining out. Despite financial pressures, many households prioritize restaurant meals and takeout for convenience. It’s not uncommon for families to spend hundreds of dollars a month on food prepared outside the home, even when groceries could cost significantly less. The trade-off is often justified as saving time, though in reality it stretches budgets thinner. This pattern shows how lifestyle convenience often wins over long-term savings.

2. Subscriptions Sneak Into Monthly Expenses

Streaming services, digital apps, and subscription boxes have quietly become a hallmark of middle-class spending habits. While each service feels affordable on its own, they accumulate into large monthly bills. Families often underestimate how much they are paying for services they rarely use. Canceling these subscriptions can feel like giving up small luxuries, even if the money could be put to better use. The normalization of subscription spending has created ongoing costs that drain savings unnoticed.

3. Credit Card Rewards Drive Overspending

Another strange truth about middle-class spending habits is the pursuit of credit card rewards. Many families swipe for every purchase, convinced the points or cash back are worth it. While rewards can be useful, they often encourage overspending beyond what’s affordable. Carrying balances wipes out the benefits, leaving households deeper in debt. This reveals how the promise of perks can overshadow sound financial judgment.

4. Cars Remain a Status Symbol

Even with rising costs, middle-class families continue to prioritize cars that stretch their budgets. New vehicles, expensive leases, and frequent upgrades are common, reflecting the cultural weight cars still carry. These choices often come with high monthly payments and insurance premiums, leaving less money for savings or investments. The desire to maintain a certain image on the road keeps families locked into expensive cycles. This habit highlights the tension between practical needs and social aspirations.

5. Home Improvements Outpace Necessities

Middle-class households frequently spend heavily on home improvements, even when budgets are already strained. Projects like new kitchens, landscaping, or trendy furniture upgrades often take priority over emergency funds or debt repayment. While these upgrades can boost comfort and property value, they are sometimes more about keeping up with neighbors than actual necessity. This spending choice can delay financial progress in other areas. It reflects how middle-class spending habits often balance practicality with a desire for social validation.

6. Vacations Are Treated as Essentials

For many middle-class families, vacations are not viewed as luxuries but as necessities. Even when money is tight, they often prioritize travel, sometimes relying on credit cards to fund trips. The experience of relaxation and escape is seen as essential for well-being, justifying the financial strain. While memories are valuable, the debt left behind can be long-lasting. This shows how emotional fulfillment often takes precedence over financial prudence.

7. Emergency Savings Take a Backseat

Perhaps the strangest of all middle-class spending habits is how little emphasis is placed on emergency savings. Despite knowing the importance of a safety net, many families prioritize other expenses instead. This leaves them vulnerable when unexpected costs like medical bills or car repairs arise. Ironically, the money often exists in the budget but is funneled into lifestyle choices. The result is financial instability, even among households with steady incomes.

Rethinking Middle-Class Money Choices

Middle-class spending habits reveal a mix of practicality, emotional fulfillment, and social influence. While families often have good intentions, choices like dining out, upgrading cars, or skipping emergency savings can keep them from building real wealth. Recognizing these strange truths is the first step toward healthier financial decisions. By rethinking priorities and focusing on long-term security, middle-class households can balance enjoyment today with stability tomorrow.

Which of these middle-class spending habits do you see most often in your own life or among people you know? Share your thoughts in the comments below.

What to Read Next…

Why Do Middle-Class Families End Up Paying the Most Taxes

10 Money Moves That Look Smart but Lead to Regret

Why Do High Earners End Up With Less Cash on Hand Than Expected

8 Financial Myths That People Still Pass Down to Kids

10 Times Inflation Changed What Families Could Afford Overnight

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Spending Habits Tagged With: budgeting, Credit card debt, emergency savings, household expenses, lifestyle choices, middle-class spending habits, Personal Finance, Planning

Why Do High Earners Still Struggle With Emergency Savings

September 10, 2025 by Travis Campbell Leave a Comment

money
Image source: pexels.com

It’s easy to assume that people who make a lot of money have their finances in perfect shape. Yet, many high earners still struggle with emergency savings. This problem matters because, without a safety net, even those with big paychecks can face real setbacks. Unexpected expenses or job loss can hit anyone, regardless of income. Building emergency savings isn’t just about how much you earn—it’s also about the habits, choices, and pressures you face. Understanding why high earners still struggle with emergency savings can help anyone make smarter decisions with their money.

1. Lifestyle Inflation

One of the biggest reasons high earners still struggle with emergency savings is lifestyle inflation. As income rises, so do expenses. People often upgrade their homes, cars, vacations, and even everyday habits when they start earning more. These new expenses can quickly eat up any extra cash. Suddenly, that higher paycheck feels just as tight as before.

This cycle makes it hard to set aside money for emergencies. Even though the income is there, it’s already spoken for by bigger bills and fancier tastes. Breaking out of lifestyle inflation requires conscious effort and clear priorities.

2. Social Expectations and Pressure

High earners can feel pressure to keep up with their peers. Whether it’s joining expensive clubs, sending kids to elite schools, or throwing lavish parties, the expectations can be relentless. These social influences often lead to overspending, leaving little left for emergency savings.

Many people don’t realize how much these pressures affect their financial decisions. The desire to fit in or impress others can quietly drain bank accounts, making it tough to build a solid emergency fund.

3. Underestimating Emergencies

Some high earners believe that their income alone will protect them from financial shocks. They might think, “I make enough to handle anything that comes up.” But emergencies—like medical bills, lawsuits, or sudden job loss—can be expensive and unpredictable.

Without dedicated emergency savings, even a high salary may not be enough. This overconfidence can lead to risky financial behavior and a false sense of security.

4. Complex Finances

As income rises, finances often become more complicated. High earners may juggle multiple investment accounts, side businesses, or real estate holdings. Managing these assets takes time and attention, and it’s easy to overlook the basics—like maintaining an emergency fund.

Complex finances can also create confusion about where money is going. With so many moving parts, it’s easy to lose track of cash flow and underestimate the need for emergency savings. Sometimes, high earners assume their investments will serve as a safety net, but accessing those funds quickly can be difficult or costly.

5. High Fixed Expenses

Many high earners lock themselves into large monthly payments. Big mortgages, luxury car leases, private school tuition, and other fixed expenses can add up fast. These commitments can leave little room in the budget for emergency savings.

When most of your paycheck goes toward non-negotiable bills, it’s tough to set aside extra cash. Even a short-term loss of income can put these obligations at risk, highlighting the need for a dedicated emergency fund.

6. Procrastination and Overconfidence

It’s common for high earners to put off saving for emergencies. With a steady income, it’s tempting to believe there’s always time to save later. This procrastination, combined with overconfidence in their earning power, can lead to a lack of preparation.

Unfortunately, emergencies don’t wait for the “right time.” Without a plan, high earners can find themselves scrambling when the unexpected happens.

7. Lack of Financial Planning

Many high earners don’t take the time to create a detailed financial plan. They might focus on growing their income or investments but neglect the basics of budgeting and saving. A lack of planning makes it easy for money to slip through the cracks.

Working with a financial advisor or using budgeting tools can help. For example, tools like Mint or consulting with a professional can highlight gaps in emergency savings and suggest practical steps to improve.

8. Misplaced Priorities

Sometimes, high earners direct their money toward goals they think are more important than emergency savings—like paying off debt, investing in the stock market, or funding their children’s education. While these are all worthy goals, skipping an emergency fund leaves them exposed to sudden financial shocks.

It’s important to balance long-term ambitions with the need for short-term security. Without emergency savings, progress in other areas can quickly unravel when life throws a curveball.

Building Strong Emergency Savings Is Possible

High earners often face unique challenges that make it hard to build emergency savings. Lifestyle inflation, social pressures, and overconfidence in income are just a few of the hurdles. Yet, setting up a solid emergency fund is just as critical for them as for anyone else. The primary step is to treat emergency savings as non-negotiable, just like any other bill or investment.

Automating transfers to a separate savings account can help. Exploring resources like practical savings strategies can also make a difference. Ultimately, anyone—regardless of income—can build financial resilience with the right habits and mindset.

Do you think high earners face different challenges with emergency savings than others? Share your thoughts in the comments below!

What to Read Next…

  • What Happens When A Medical Emergency Outpaces Your Emergency Fund
  • Why Some People Feel Rich But Can’t Afford A 400 Emergency
  • 5 Emergency Repairs That Could Force You Into Debt Overnight
  • Are These 6 Helpful Budget Tips Actually Ruining Your Finances
  • Are These 8 Money Saving Tricks Actually Keeping You Broke
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Finance Tagged With: emergency savings, high income, Lifestyle Inflation, Personal Finance, Planning, savings strategies

Why Crowdfunding Might Be Your Next Emergency Fund

April 25, 2025 by Travis Campbell Leave a Comment

exchanging money
Image Source: pexels.com

In a world where financial stability feels increasingly elusive, traditional emergency funds—while essential—may not always be sufficient when crisis strikes. Crowdfunding platforms have emerged as powerful tools that allow individuals to tap into the collective generosity of friends, family, and even strangers during times of need. This alternative approach to emergency funding isn’t meant to replace your savings account but to supplement it when life throws particularly expensive curveballs your way. Understanding how crowdfunding works as a financial safety net could transform your approach to emergency planning and potentially save you from devastating financial setbacks.

1. Traditional Emergency Funds Have Limitations

Conventional wisdom suggests maintaining three to six months’ expenses in an easily accessible account. However, this advice faces serious challenges in today’s economic reality. According to a Federal Reserve survey, nearly 37% of Americans would struggle to cover an unexpected $400 expense without borrowing money. Even those who diligently save may find their emergency funds quickly depleted by major medical bills, home repairs, or extended job loss.

Traditional emergency funds also face the challenge of inflation eroding purchasing power while sitting in low-interest savings accounts. Additionally, many Americans are juggling multiple financial priorities—paying down debt, saving for retirement, and covering rising living costs—making it difficult to build substantial emergency savings in the first place.

2. Crowdfunding Provides Access to a Wider Support Network

Crowdfunding platforms like GoFundMe, Kickstarter, and Indiegogo have democratized access to financial support. These platforms allow you to reach beyond your immediate circle to potentially thousands of donors. Your story can resonate with people you’ve never met who are willing to contribute to your cause.

The power of social sharing means your fundraising campaign can reach exponentially more people than you could personally contact. Sharing with friends creates a ripple effect that significantly expands your potential donor pool. This network effect is something traditional emergency funds simply cannot replicate.

For example, medical crowdfunding campaigns on GoFundMe raise an average of $2,500, with some raising tens of thousands or even millions of dollars for particularly compelling cases. This demonstrates the potential scale of support available through crowdfunding that would be impossible to achieve through individual saving alone.

3. Crowdfunding Works Best for Specific, Compelling Needs

Not all emergencies are equally suited for crowdfunding. Campaigns that clearly articulate specific needs tend to perform better than general requests for financial assistance. Medical emergencies, disaster recovery, funeral expenses, and educational needs typically generate the strongest response from donors.

The key to successful crowdfunding is transparency and storytelling. Donors want to understand exactly what happened, why you need help, and how their contribution will make a difference. Sharing personal details, photos, and updates creates an emotional connection and trust with potential donors.

According to crowdfunding statistics, campaigns with personal stories and regular updates raise 126% more than those without. This highlights the importance of crafting a compelling narrative around your emergency need rather than simply asking for financial help.

4. Crowdfunding Can Be Faster Than Traditional Financial Options

Timing is critical in true emergencies. While building a traditional emergency fund takes months or years of disciplined saving, crowdfunding can potentially raise significant funds within days. Most platforms allow immediate withdrawal of funds as they come in, providing quick access to financial support when you need it most.

This speed advantage becomes particularly valuable when facing time-sensitive emergencies like medical treatments, housing crises, or urgent travel needs. While bank loans and credit cards might offer similar speed, they come with application processes, credit checks, and interest charges that crowdfunding avoids entirely.

The average successful crowdfunding campaign reaches 42% of its goal within the first three days, demonstrating how quickly support can materialize when your network mobilizes around your cause.

5. There Are Important Limitations to Consider

Crowdfunding isn’t a guaranteed solution and comes with significant considerations. Success rates vary widely, with most campaigns failing to reach their goals. Factors like the size of your social network, the nature of your emergency, and your ability to effectively communicate your story all impact outcomes.

There are also potential tax implications to navigate. While most personal crowdfunding contributions are considered gifts and not taxable income, large amounts may trigger gift tax considerations for donors. Platform fees typically range from 2.9% to 5% plus processing fees, reducing the amount you actually receive.

Privacy concerns represent another significant consideration. Sharing personal hardships publicly can feel uncomfortable and potentially impact your professional reputation or future opportunities. Before launching a campaign, carefully consider how much of your situation you’re comfortable sharing with the world.

6. Best Practices for Emergency Crowdfunding Success

Creating an effective crowdfunding campaign requires strategic planning. Start by selecting the right platform for your specific need—GoFundMe for personal emergencies, Kickstarter for creative projects, or specialized platforms like GiveForward for medical expenses.

Set a realistic funding goal based on your actual needs rather than an arbitrary amount. Be specific about how funds will be used and provide a detailed breakdown if possible. Include compelling visuals—photos and videos significantly increase engagement and sharing.

Leverage all available social networks and don’t be afraid to directly ask friends and family to share your campaign. The first 48 hours are critical for building momentum, so plan your launch carefully and have an initial outreach strategy ready.

7. Building a Hybrid Emergency Safety Net

The most resilient financial strategy combines traditional emergency savings with awareness of crowdfunding as a backup option. Continue building your conventional emergency fund while understanding how crowdfunding works, should you ever need additional support.

Consider creating a “crowdfunding contingency plan” that outlines which types of emergencies might warrant a campaign, who would help you manage it, and how you’d approach sharing your story. Having this plan in place reduces stress and decision fatigue during an actual emergency.

This hybrid approach acknowledges both the importance of self-reliance through saving and the reality that community support through crowdfunding can provide a crucial safety net when traditional resources fall short.

The Community-Powered Financial Safety Net

Crowdfunding represents a fundamental shift in how we think about financial emergencies, moving from purely individual responsibility to a model that embraces community support. While it shouldn’t replace traditional emergency savings, it offers a powerful complementary tool that recognizes our interconnectedness and collective capacity to help each other through difficult times. As economic uncertainty continues to challenge conventional financial wisdom, incorporating crowdfunding into your emergency planning may provide the additional security and peace of mind that traditional approaches alone cannot deliver.

Have you ever contributed to or created a crowdfunding campaign for an emergency? What was your experience, and would you consider it part of your financial safety net?

Read More

Peer-to-Peer Lending Requirements

How to Fund a Startup When You Don’t Have Any of Your Own Money

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Budgeting Tagged With: crowdfunding, emergency fund, emergency savings, financial safety net, GoFundMe, Personal Finance, Planning

  • « Previous Page
  • 1
  • 2

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework