• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for tax tips

Are You Prepared For The Tax-Law Changes Arriving Sooner Than Most Americans Expect?

December 11, 2025 by Brandon Marcus Leave a Comment

You Need To Be Prepared For The Tax-Law Changes Arriving Sooner Than Most Americans Expect
Image Source: Shutterstock.com

Tax season has always had a way of sneaking up on us, but this year, the game is changing faster than most Americans realize. New rules are rolling out that could reshape deductions, credits, and even how your paycheck is taxed—sometimes without any warning. It’s not just a matter of filing differently; these changes could impact everything from your retirement planning to your side hustle.

Staying ahead means understanding what’s coming, how it affects you, and what moves you can make now to avoid surprises. Let’s dig into the tax shifts that are making accountants and everyday taxpayers alike rethink their strategy.

1. Understanding The Key Deductions That Are Shifting

Tax deductions are no longer what they used to be, and some familiar write-offs are getting trimmed or redefined. For instance, certain business expenses, home office deductions, and education credits are facing updates that could limit eligibility. Many Americans rely on these deductions to reduce taxable income, so missing a change could mean paying more than necessary. Staying informed now gives you the chance to adjust spending, receipts, or timing before the law takes effect. Ignoring the shifts could turn a routine tax return into an unpleasant shock when you realize a deduction you counted on is no longer available.

2. How Credits Are Being Rewritten And Expanded

While some deductions are shrinking, certain tax credits are getting a boost—especially those aimed at energy-efficient home upgrades, childcare, and education. The government is incentivizing behaviors they want to see more of, which means you could qualify for credits you didn’t know existed. On the flip side, older credits are being phased out or adjusted for income thresholds. Missing out on a new credit could cost you hundreds or even thousands of dollars, so now is the time to review eligibility criteria. Proper planning and documentation can make the difference between claiming every available credit and leaving money on the table.
You Need To Be Prepared For The Tax-Law Changes Arriving Sooner Than Most Americans Expect
Image Source: Shutterstock.com

3. Retirement Accounts And Contributions Face New Limits

One of the sneakiest changes involves retirement contributions, which may affect 401(k), IRA, and other retirement accounts. Contribution limits are being updated, and the rules surrounding deductions for traditional IRAs are shifting based on income levels. These updates can have ripple effects, altering how much you can shelter from taxes each year. Regular taxpayers might find themselves unexpectedly over or under-contributing if they don’t pay attention. Staying proactive ensures your retirement planning stays on track without creating accidental penalties or missed opportunities.

4. The Side-Hustle Impact Is Bigger Than You Think

Side hustles and gig work are booming, and the tax code is adjusting to catch up. Many self-employed individuals may see changes in how expenses, income reporting, and deductions are calculated. What once felt like an easy home office deduction or vehicle write-off might now require extra documentation or meet new criteria. Ignoring these changes could mean underpaying taxes one year and facing a hefty bill later. The key is understanding how your extra income fits into the updated rules so that you stay compliant and avoid surprise penalties.

5. State And Local Taxes Are Joining The Shuffle

Federal changes aren’t the only thing shaking up tax season—state and local governments are also adjusting rules to align with new federal updates. These changes could affect itemized deductions, credits, and how local income or property taxes are reported. Some states are even creating new incentives for renewable energy or education spending, adding another layer of complexity. Taxpayers who only focus on federal law could miss key opportunities—or face unexpected liabilities. Keeping track of both federal and state changes ensures your tax plan is holistic, not just piecemeal.

6. Timing Could Make Or Break Your Savings

Many of the new rules have effective dates that arrive sooner than most Americans anticipate. Planning for these changes now can help you shift income, accelerate deductions, or restructure investments to maximize savings. Procrastinating, even by a few months, could mean missing deadlines for key deductions or credits. Tax planning isn’t just about filing correctly—it’s about using timing to your advantage. Understanding when rules take effect gives you a window to make strategic moves that could save significant money.

7. Digital Records And Documentation Are More Important Than Ever

With new rules comes increased scrutiny, and proper documentation has never been more critical. Receipts, invoices, and digital records can prove eligibility for deductions, credits, and business expenses. Losing or misfiling a document could mean losing the tax benefit entirely. The updated laws may also favor taxpayers who can provide clear, organized evidence of expenses and income. Staying meticulous now prevents headaches, audits, or denied deductions later.

8. Professional Advice Is Not Optional

Given the complexity and speed of these changes, relying solely on DIY tax software might not be enough. Professional accountants and tax advisors are adapting quickly and can provide guidance tailored to your specific financial situation. They can identify opportunities or pitfalls that you might overlook, saving you both money and stress. While self-education is important, expert insight ensures you’re not leaving money on the table or inadvertently violating new rules. Investing in professional advice now could pay off exponentially when tax season arrives.

Take Action Before The Clock Runs Out

The tax-law changes coming sooner than expected aren’t just bureaucratic reshuffles—they’re potential financial game-changers. Understanding deductions, credits, retirement rules, side-hustle implications, and state-level updates gives you a competitive edge. Planning now allows you to make informed decisions and adjust your financial habits before deadlines hit. Ignoring the updates could lead to missed opportunities, higher taxes, and unnecessary stress.

How are you preparing for the changes? Share your strategies, questions, or stories.

You May Also Like…

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

Side Hustles That Look Legit—Until They Break Tax Laws

5 Tax Laws That Could Save You Thousands of Dollars Each Year If You Knew About Them

What Happens When Small Business Owners Skip Taxes

Why Do Middle-Class Families End Up Paying the Most Taxes


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: 2025 tax changes, 2025 taxes, 2026 tax law, credits, deductions, local taxes, retirement accounts, savings account, side hustle, side hustles, state taxes, Tax, tax contributions, tax credits, tax laws, tax tips, taxes

Estate Shift: 4 Overlooked Documents That Could Trigger Major Tax Headaches

December 11, 2025 by Brandon Marcus Leave a Comment

There Are Many Overlooked Documents That Could Trigger Major Tax Headaches
Image Source: Shutterstock.com

Managing your estate isn’t just about writing a will and hoping for the best. Even the most organized families can stumble into tax pitfalls if certain documents are ignored or misunderstood. The problem is, these documents are sneaky—they sit quietly in drawers, digital folders, or old email threads, waiting for an unsuspecting executor to discover them… right in the middle of tax season.

What seems like a minor oversight can snowball into confusion, penalties, or costly delays. Let’s dig into four overlooked estate documents that could create major headaches if you’re not careful.

1. Life Insurance Policies With Outdated Beneficiaries

Life insurance policies are supposed to provide peace of mind, but outdated beneficiaries can turn them into a tax nightmare. Many people name a spouse or child years ago and forget to update it after a divorce, second marriage, or adoption. When a death occurs, the policy payout could go to the wrong person, sparking legal disputes and potentially unexpected tax consequences. Executors may have to juggle multiple claims while filing estate taxes correctly, which can lead to delays or even fines. Regularly reviewing and updating beneficiary information is essential to avoid this hidden headache.

2. Old Retirement Account Statements

401(k)s, IRAs, and other retirement accounts can become ticking tax time bombs if the paperwork isn’t kept up to date. Old statements may show outdated contributions, missing rollovers, or forgotten accounts that can complicate distribution after death. Failing to provide accurate, current records can lead to miscalculations, triggering unnecessary tax liabilities for heirs. Even small oversights, like forgetting a beneficiary designation on an old IRA, can result in substantial penalties or disputes. Staying on top of retirement account documentation ensures your assets are distributed smoothly and tax-efficiently.

3. Forgotten Trust Agreements

Trusts are meant to simplify estate management, but a forgotten or outdated trust agreement can cause chaos. Many people set up trusts and then tuck the documents away, assuming everything will work automatically. If the trust’s instructions conflict with other documents, like a will or beneficiary form, executors face the tricky task of untangling discrepancies while avoiding tax pitfalls. Even minor ambiguities can escalate into court disputes, delays, and unexpected tax bills. Reviewing and updating trust agreements regularly helps prevent misinterpretation and keeps tax planning on track.

4. Previous Gift Tax Filings

Gift tax documents may feel like ancient history once the gifts are given, but they can come back to haunt heirs if overlooked. Previous gifts to family members or friends may affect the estate’s total value and its tax obligations. And then executors must reconcile these older gifts with current estate valuations to ensure taxes are reported correctly. Keeping detailed records of all gift tax filings provides clarity and protects beneficiaries from unexpected burdens.

There Are Many Overlooked Documents That Could Trigger Major Tax Headaches
Image Source: Shutterstock.com

Avoiding Hidden Estate Headaches

Estate planning isn’t just about creating documents—it’s about keeping them current, accurate, and accessible. Overlooking life insurance updates, retirement statements, trust agreements, or gift tax filings can create serious headaches for heirs and executors alike. The key to preventing major tax issues is regular review, careful record-keeping, and awareness of potential conflicts among documents.

Have you ever encountered a hidden estate document that caused unexpected complications? Share your experiences, tips, or cautionary tales in the comments.

You May Also Like…

Alert Phase: 5 Tax Tricks You’ll Regret Ignoring Before Year-End

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

Am I the Only One Who Thinks Estate Planning Is Deeply Terrifying?

7 Excuses Millennials Use to Delay Estate Planning (and Why It’s Risky)

8 Tax Moves That Save You When You Can’t Pay the IRS on Time


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: 2025 tax changes, 2025 taxes, 2026 tax law, DIY taxes, Easy Tax Filing, Insurance, life insurance, life insurance policies, retire, Retirement, retirement accounts, tax filings, tax headaches, tax problems, taxes, trust agreements

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

December 9, 2025 by Brandon Marcus 2 Comments

Here Are The Georgia Counties Where Property Taxes Are Set to Rise the Fastest
Image Source: Shutterstock.com

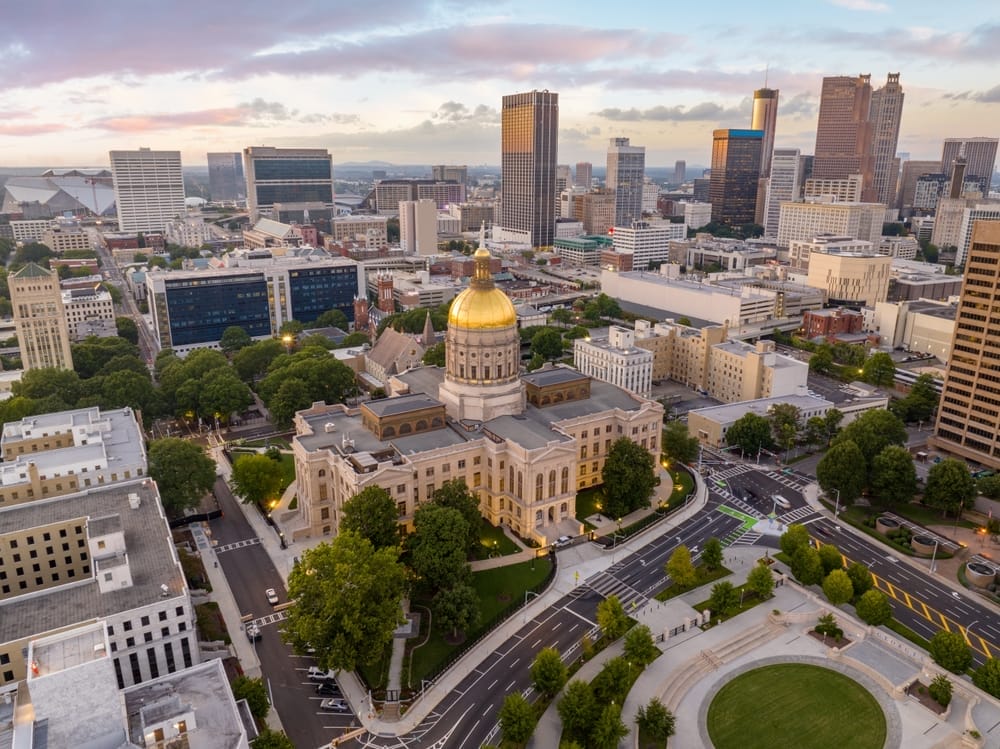
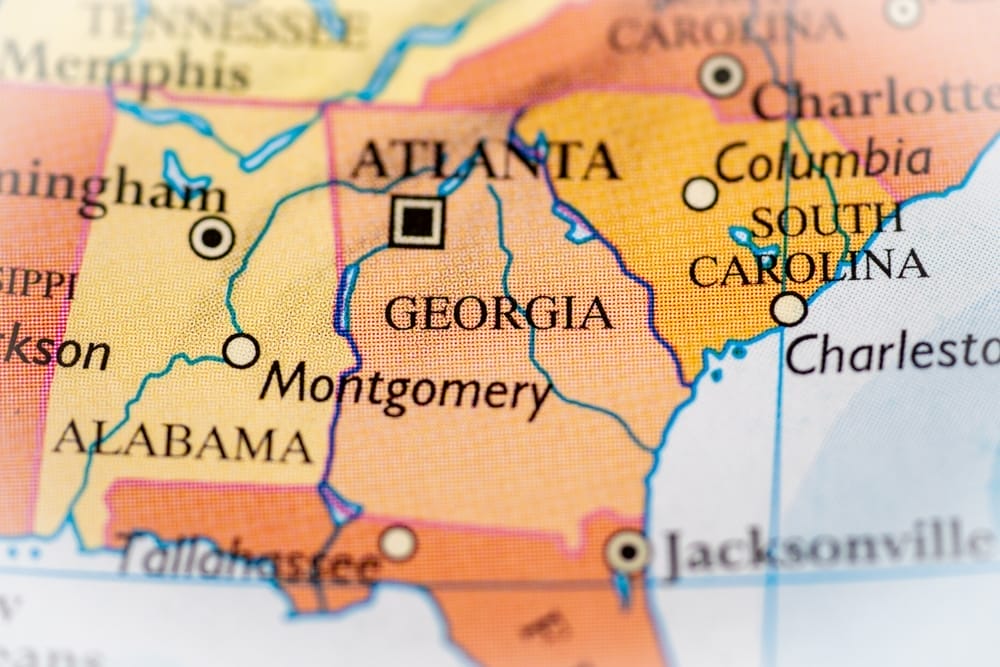
Let’s dive right in — if you own property in Georgia (or you’re house-hunting), buckle up. Home values are shooting up across parts of the state, and that means for many homeowners, the property tax bill that lands in your mailbox this year could hit a lot harder than last year. Between rapidly rising assessments, shifting millage rates, and local governments scrambling to keep up with growth (or budget shortfalls), there are several counties where taxes are on track to climb faster than you might expect.

Here are nine Georgia counties to watch if you care about what your home will cost you — and what you might start paying soon.

1. DeKalb County

DeKalb County is practically waving a red flag when it comes to rising tax burdens in 2025. The county’s governing authority has approved a tentative millage rate of 12.427 mills — that’s 2.690 mills over the computed “rollback” rate, representing a 27.6 percent increase from what the rollback formula would dictate. Even though the combined rate for all levies has been held flat at 20.81 mills since 2015, the reassessment of property values means many homeowners are still looking at significantly larger tax bills.

For those living in parts of metro Atlanta where housing demand has exploded — and with schools, public services, and infrastructure under pressure — the jump in tax obligations feels like the price tag for growth. If your property was reassessed upward even a little, that 27% swing could hit harder than it looks on paper.

2. Cobb County

Cobb County remains one of Georgia’s fastest-growing suburban hubs, and with growth comes rising home values — and rising taxes. According to the 2025 residential property value report, the market value of single-family homes rose about 3.1 percent compared to 2024. That’s not the kind of jump that knocks you off your feet overnight — but consistent annual increases add up over time, especially when many homeowners already operate on tight margins or fixed incomes.

The ripple effect? Expect next year’s tax digest (and likely your bill) to reflect the new valuations. As properties change hands or get upgraded, it’s a reminder that suburban expansion often comes with a hidden cost.

3. Fulton County

In the heart of metro Atlanta, Fulton County continues to see some of the steepest home-value gains statewide — and that typically translates directly into steeper taxes. A recent report showed residential property values increased by 5.9 percent overall, with even bigger upswing among higher-valued homes. It’s not just luxury mansions driving the spike either; mid-range properties saw solid upward movement, pushing more “average” homeowners into new tax brackets.

The truth is, when demand is high and inventory is tight, tax assessments follow market prices — and that upward pressure tends to stick. For many long-time residents, this can feel like being priced out of your own neighborhood without ever moving.

Here Are The Georgia Counties Where Property Taxes Are Set to Rise the Fastest
Image Source: Shutterstock.com

4. Gwinnett County

Though not always in the headlines, Gwinnett County in recent years has seen rapid population growth and mounting development. As demand pushes property values upward, tax bills are likely to follow. In recent statewide property-tax data, Gwinnett had among the highest effective tax burdens for homeowners. This county is part of the broader metro-Atlanta growth wave — new homes, families moving in, and expanding services. With schools, roads, and infrastructure needing funding, officials often lean on property tax increases to keep pace. If you own in Gwinnett and haven’t looked at your latest assessment closely — now might be a good time.

5. Chatham County

Way out on the coast, things are heating up in Chatham County too. As home to the city of Savannah and its surrounding suburbs, Chatham is seeing rising demand for housing — which tends to push up property valuations. According to the latest county-by-county data, Chatham’s effective property tax rate and median tax bills are among the higher ones in Georgia. For coastal homeowners, rising property taxes can clash with other cost pressures like insurance, maintenance, and flood-related expenses. If you own a home in this region, prepare for what could be a steeper climb than many inland counties are facing.

6. Fayette County

Fayette County is often overlooked in discussions about tax spikes, but it’s a place where property value increases and tax burdens have quietly climbed. According to recent data, many mid-sized Georgia counties like Fayette are seeing rising effective tax rates and increased tax bills, even as statewide attention focuses on the major metros. For long-term homeowners, that can mean incremental increases over successive years — enough to shift what was once a manageable payment into a financial burden. Communities that had affordable charm a few years back may now feel the squeeze as valuations edge upward and local government costs rise.

7. Henry County

Henry County, which sits on the growing periphery of metro Atlanta, is another spot where homeowners should keep a close eye. As development expands outward and more people move in, property values tend to follow — and with that, tax bills often climb too. Tax data show that Henry County’s effective property tax burden is already above the statewide median. For families moving into what once felt like affordable suburbs, this means the dream of lower-cost living might be under threat from rising assessments and incremental tax pressure. New growth brings new amenities — but also new expenses.

8. Coweta County

Few counties outside the big metro centers get much attention, but Coweta County is quietly part of the broader shift. As people look for more space and affordability outside major urban zones, places like Coweta become magnets — which can trigger property value hikes. According to recent property-tax data sets, Coweta shows a relatively high effective rate, suggesting that as home values rise, tax bills are likely to follow. This dynamic often sneaks up on homeowners: the neighborhood feels peaceful, the home feels like your refuge, but the tax bill creeping up in your mailbox tells a different story. If you call Coweta home — or are thinking about buying there — it’s worth budgeting for steeper taxes down the line.

9. Butts County

Last but not least, Butts County stands out among Georgia’s smaller and more rural counties, yet it shows signs of rising tax burden that many might not expect. According to county-by-county effective property tax data, Butts is among the counties where rates — relative to property values — are trending upward. As urban sprawl pushes outward, even rural zones can feel the ripple effect of increased demand, leading to reassessments and higher bills. For homeowners who moved here for peace, space, or affordability, that tax increase can sting: what once felt affordable might suddenly feel like a stretch.

What This Means For Georgia Homeowners

If you own — or are thinking of buying — a home in Georgia, these counties show that the property-tax landscape is shifting quickly. Rising home values, population growth, and local budget pressures are colliding to make increases more common than exceptions. It’s a reminder that homeownership isn’t just about your mortgage and that property taxes can sneak up and add real impact to your bottom line.

Have you seen a jump in your latest tax bill? Are you feeling the squeeze — or moving because of it? We want to hear your story. Drop your experience, tips, or frustrations in the comments below.

You May Also Like…

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

Can Your Taxes Be Cut In Half By You Simply Incorporating Your Name?

5 Reasons Why Homeowners Should Increase Their Property’s ROI

9 Financial Dangers of Ignoring Property Taxes

7 Lesser-Known Costs of Selling Inherited Property


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: Butts County, Chatham County, Cobb County, Coweta County, DeKalb County, Fayette County, Fulton County, Georgia, Gwinnett County, Henry County, property tax, property taxes, tax rules, taxes

8 Tax Moves That Save You When You Can’t Pay the IRS on Time

November 17, 2025 by Travis Campbell Leave a Comment

tax
Image source: shutterstock.com

The start of tax season can create panic because your financial records do not align with your expected results. The feeling of being unable to pay your IRS debt becomes overwhelming, but you can prevent it from getting out of hand. You can reduce expenses through various financial strategies that help you stay penalty-free while gaining control over your money. The combination of IRS payment plans with strategic actions helps you to manage your financial situation effectively, rather than letting it deteriorate into a dire state. The correct strategy allows you to defend your money while maintaining your mental serenity.

1. Set Up an IRS Payment Plan

An IRS payment plan is often the fastest way to steady the situation. It reduces stress because you know the debt won’t go into harsher collection methods. Many people qualify without much hassle, and the application can be completed online.

The monthly payments stay flexible, which helps if your income shifts. Even if interest continues, slowing down penalties is still a win. The IRS payment plan also signals a good-faith effort, which matters if issues come up later.

2. Ask for a Short-Term Extension

Sometimes you don’t need a long repayment window. A short-term extension gives you up to 180 days to pay the full amount. This option works well if cash is coming soon, like a bonus, sale, or expected payout.

You avoid the setup fees tied to longer arrangements. Penalties don’t disappear, but they stay limited. It’s a simple move that keeps you out of deeper trouble while you pull money together.

3. Request Penalty Abatement

Penalty abatement can significantly reduce the impact. If you have a clean tax record for the past few years, you might qualify for a first-time abatement. The IRS removes certain penalties while still charging interest on the debt.

This is worth exploring when an IRS payment plan is already in place, but the added charges feel punishing. If you had a serious illness or another hardship, reasonable cause abatement might also apply. Every dollar that drops off makes repayment easier.

4. Adjust Your Withholding for Next Year

It’s easy to fall behind again if nothing changes. Adjusting your withholding helps prevent a repeat. A small shift in each paycheck spreads the tax burden over the year instead of all at once.

You can use a calculator or the guidance offered on the official IRS website to fine-tune your numbers. Once adjusted, your next season feels more predictable. It’s not exciting, but it steadies the long-term picture.

5. Reduce the Bill With Available Credits

Before settling on what you owe, double-check if you missed any credits. People often overlook energy improvements, education credits, or income-based reductions. Claiming even one of these can lower the balance and shrink the pressure.

If you work with a tax professional, ask them to scan for missed credits. If you prepare your own return, review updated rules since they change often. Even small credits have a noticeable impact when cash is tight.

6. File Even If You Can’t Pay

Filing late triggers harsh penalties. Filing on time avoids that, even when the money isn’t ready. The IRS separates the act of filing from the act of paying, which surprises many people.

You might still be nervous about the balance, but filing first limits damage. After that step, you can explore an IRS payment plan or extension. Staying current with your returns also prevents the IRS from estimating your tax for you, which usually turns out worse.

7. Use a Partial Payment Agreement

A partial payment agreement works like a long-term installment plan, but the final payoff may be less than the full balance. The IRS reviews your income and expenses closely before approving it. It’s not a quick fix, but it can help when your budget leaves almost no room.

Because finances change, the IRS checks in every couple of years to reassess. If things improve, payments may increase. Still, for someone truly struggling, this structure provides breathing room.

8. Explore an Offer in Compromise

Some taxpayers qualify for an Offer in Compromise, which settles the debt for less than the total amount. It’s strict and only applies when full payment is unrealistic. You must show that paying in full would create long-term financial strain.

The process requires good documentation and patience. While not fast, it can be life-changing if approved. You can review guidelines through the Taxpayer Advocate Service before deciding if it fits your situation.

Staying Steady After the First Shock

Your primary objective following the initial period of financial stress should focus on identifying upcoming financial problems. The IRS payment plan helps you handle your current year tax debts, but you need to build solid financial practices to safeguard your long-term financial security. You should track your income fluctuations while keeping a minimal tax fund and update your tax withholdings based on any changes in your personal situation.

The tax system may appear unyielding, but you have various options. Your knowledge of available tools helps you move from being trapped to developing self-assurance. What particular step did you perform after getting a tax bill that exceeded your current financial resources?

What to Read Next…

  • 5 Account Transfers That Unexpectedly Trigger IRS Penalties
  • 9 Mistakes That Turned Wealth Transfers Into IRS Nightmares
  • 7 Ill Advised Advisor Tips That Trigger IRS Audits
  • 6 Tax Breaks That Vanished Before Anyone Noticed
  • Are You Reading The Right Fine Print On Your Tax Refund?
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: tax tips Tagged With: IRS, money management, Personal Finance, tax debt, taxes

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

October 30, 2025 by Travis Campbell Leave a Comment

Tax
Image source: shutterstock.com

Stock investments, real estate ownership, and other asset purchases result in taxable capital gains that must be reported to the government. The tax returns of high-income earners and asset holders will decrease significantly because of these new levies. Smart investors understand that minimizing capital gains taxes leads to better wealth growth because it allows them to retain their earned income. The good news? There are advanced and legal strategies you can use to lower capital gains taxes. Knowledge of these methods enables you to create more effective investment plans that lead to safer financial decisions and generate superior long-term results. Here are six advanced ways to help you legally lower your capital gains taxes and keep your investments working harder for you.

1. Tax-Loss Harvesting

Tax-loss harvesting is a savvy strategy that involves selling investments that have declined in value to offset gains from other investments. By realizing losses, you can reduce your taxable capital gains and, in some cases, even offset up to $3,000 of ordinary income each year. If your losses exceed that amount, you can carry them forward to future years. This approach is commonly used at the end of the year, but you can harvest losses throughout the year whenever the market dips. Just be mindful of the wash-sale rule, which prevents you from claiming a loss if you buy a substantially identical security within 30 days before or after the sale.

2. Take Advantage of Long-Term Capital Gains Rates

Not all capital gains are taxed equally. Assets held for more than a year benefit from lower long-term capital gains tax rates, which can be significantly less than short-term rates. In 2024, long-term capital gains tax rates range from 0% to 20%, depending on your income. By holding investments for at least 12 months before selling, you can lower your capital gains taxes and keep more profit in your pocket. This simple shift in timing can save thousands over the years, especially for high-value assets.

3. Use Qualified Opportunity Zones

Investing in Qualified Opportunity Zones (QOZs) is a powerful way to lower your capital gains taxes while supporting economic development. When you reinvest capital gains into a Qualified Opportunity Fund, you can defer paying tax on those gains until as late as 2026. If you hold the new investment for at least 10 years, any additional gains from the QOZ investment can be tax-free. This strategy requires careful research and planning, but it’s a valuable option for those looking to reduce capital gains taxes on substantial profits.

4. Donate Appreciated Assets to Charity

Donating appreciated stocks or other investments directly to charity is a double win. You avoid paying capital gains taxes on the appreciated value, and you may qualify for a charitable deduction based on the full fair market value of the asset. This technique works especially well for investors who are already charitably inclined. If you’re interested in structured giving, consider setting up a donor-advised fund, which allows you to make a charitable contribution, receive an immediate tax deduction, and recommend grants from the fund over time.

5. Strategic Use of 1031 Exchanges

Real estate investors have a unique opportunity to defer capital gains taxes by using a 1031 exchange. This process allows you to sell one investment property and purchase another “like-kind” property without immediately paying taxes on the gains. The tax is deferred until you eventually sell the replacement property. There are strict rules and timelines, so working with a qualified intermediary is essential. 1031 exchanges can be repeated, allowing you to defer capital gains taxes indefinitely while growing your real estate portfolio.

6. Gifting Appreciated Assets to Family Members

If you’re looking to help family members and lower your capital gains taxes, consider gifting appreciated assets. When you gift stock or other investments to someone in a lower tax bracket, they may pay less (or even no) capital gains taxes when they sell. This works best with adult children or relatives who are not subject to the kiddie tax rules. You can gift up to the annual exclusion amount ($17,000 per recipient in 2024) without triggering gift taxes. This approach lets you support loved ones while reducing your capital gains exposure.

Building a Smarter Tax Strategy

Your ability to reduce capital gains taxes will create substantial benefits for your future financial stability. You can maintain your investment gains while lowering your annual tax expenses through tax-loss harvesting, 1031 exchanges, and strategic gifting methods. The tax benefits from capital gains reductions apply to everyone who owns appreciated assets, regardless of their financial status or investment experience.

What strategies have you used to lower your capital gains taxes? Share your tips and experiences in the comments below!

What to Read Next…

  • 7 Real Estate Transfers That Trigger Capital Gains Overnight
  • How a Rental Property in the Wrong State Can Wreck Your Tax Bracket
  • 6 Tax Moves That Backfire After You Sell a Property
  • 7 Tax Breaks That Sound Generous But Cost You Later
  • 6 Tax Breaks That Vanished Before Anyone Noticed
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: tax tips Tagged With: 1031 exchange, capital gains tax, charitable giving, investing, Real estate, tax strategies, tax-loss harvesting

The “Dirty Dozen”: The 12 Tax Scams the IRS Is Warning All Americans About

October 17, 2025 by Catherine Reed Leave a Comment

The "Dirty Dozen": The 12 Tax Scams the IRS Is Warning All Americans About
Image source: shutterstock.com

Every year, the IRS releases a “Dirty Dozen” list—a public warning to taxpayers about the latest and most dangerous tax scams circulating across the country. These scams target both individuals and tax professionals, aiming to steal personal information, refunds, or even entire identities. From fake charities to shady “tax experts,” these schemes evolve quickly, preying on confusion and trust. Understanding how these scams work is your best defense against falling victim. Here are the 12 tax scams the IRS wants every American to watch out for this year.

1. Email and Text Phishing Attacks

Phishing remains one of the most common tax scams the IRS warns about every year. Scammers send fake emails claiming to be from the IRS or tax preparation companies, luring victims with promises of refunds or threats of legal action. These emails often contain links that lead to fake websites or malware downloads. A newer twist, called “smishing,” uses text messages to do the same thing. The IRS never contacts taxpayers by email, text, or social media, so delete any suspicious message immediately.

2. Bad Social Media Tax Advice

Social media platforms have become breeding grounds for misleading tax information. Some videos and posts encourage taxpayers to misuse legitimate forms—like the W-2—to claim fake credits or refunds. This trend is especially common on platforms like TikTok, where “tax hack” videos spread quickly. The IRS has made it clear that following this bad advice can result in hefty fines or even criminal charges. Always rely on verified information from the IRS website or licensed tax professionals.

3. IRS Online Account Assistance Scams

Another fast-growing tax scam involves fake “helpers” who offer to set up your IRS online account for you. The scammers claim to simplify the process but instead use it to steal your personal information. Once they gain access, they can file fraudulent tax returns in your name and collect your refund. The IRS emphasizes that setting up an online account is free and easy to do yourself at IRS.gov. If someone offers this “service,” it’s almost certainly a con.

4. Fake Charities That Exploit Generosity

Whenever disaster strikes or headlines highlight humanitarian crises, fake charities start popping up. Scammers create convincing websites or social media pages to collect donations that never reach real victims. In some cases, they use the opportunity to steal your credit card or banking details. Before donating, always verify that the organization is registered with the IRS’s Tax Exempt Organization Search tool. Remember—if the group pressures you to donate immediately, it’s probably a fake.

5. False Fuel Tax Credit Claims

Some dishonest tax preparers or online influencers encourage taxpayers to claim the fuel tax credit even when they’re not eligible. This credit is intended only for off-highway business use, like farming or construction—not personal vehicles. Filing for it incorrectly can trigger audits or penalties. The IRS has seen a rise in fake promotions encouraging people to use Form 4136 to boost refunds. Always confirm your eligibility before claiming any specialized tax credit.

6. Bogus Sick Leave and Family Leave Credits

A newer addition to the list of tax scams involves people falsely claiming pandemic-era credits that no longer apply. Fraudulent social media posts tell taxpayers to use Form 7202 to get large refunds for sick leave or family leave—even if they were employees, not self-employed. These credits were only valid for income earned during 2020 and 2021. Filing for them now is illegal and could lead to repayment demands or penalties. The IRS continues to flag this growing issue across multiple states.

7. The Fake Self-Employment Tax Credit

Scammers are also pushing a nonexistent “Self-Employment Tax Credit” on social media. They falsely claim that gig workers and freelancers can receive payments of up to $32,000 as part of a government relief program. In reality, no such credit exists. Fraudsters use this tactic to collect personal information or charge upfront fees to “file” on your behalf. The IRS warns that any credit related to self-employment income is highly specific and must follow official eligibility guidelines.

8. False Household Employment Tax Claims

In this scam, taxpayers fabricate household employees—like nannies or caregivers—and file Schedule H to claim fake sick or family leave wages. Some even claim refunds for taxes they never paid. It might sound harmless, but this scheme is outright fraud. The IRS can quickly verify whether these employees exist, and those caught filing false claims can face steep penalties. Always file based on real employment and accurate income records.

9. The Overstated Withholding Scheme

One of the more complex tax scams on the IRS radar involves falsifying W-2 or 1099 forms to inflate income and withholding. Scammers claim that by exaggerating these amounts, taxpayers can get massive refunds. But once the IRS reviews the forms and finds no matching employer data, those refunds are frozen and flagged for investigation. This scam can also involve multiple form types, including W-2G and 1099-DIV. Submitting falsified tax information is a quick path to fines or prosecution.

10. Misleading “Offer in Compromise” Mills

The Offer in Compromise (OIC) program helps taxpayers settle debts with the IRS, but scammers exploit it through aggressive “OIC mills.” They promise to wipe away your tax debt for a large upfront fee, even if you don’t qualify. These companies rarely deliver, leaving victims deeper in financial trouble. Taxpayers can check their eligibility for free through the official IRS Offer in Compromise Pre-Qualifier tool. If someone guarantees forgiveness for a price, it’s a clear red flag.

11. Ghost Tax Return Preparers

Not all tax preparers are trustworthy. “Ghost preparers” complete returns for clients but refuse to sign or include their IRS Preparer Tax Identification Number (PTIN), as required by law. Many charge fees based on the refund amount—an illegal practice that often leads to fraudulent filings. If a preparer won’t sign your return, don’t use them. Always choose certified professionals with transparent pricing and verifiable credentials.

12. New Client and Spear Phishing Attacks on Tax Pros

Cybercriminals have shifted their focus to tax professionals through spear phishing attacks. They pretend to be new clients and send emails that contain malicious links or attachments. Once opened, these links infect systems and expose sensitive client data. This scam is particularly dangerous because it affects both tax professionals and their clients. The IRS urges professionals to verify all new contacts and use multi-factor authentication to protect sensitive accounts.

Staying Safe from the “Dirty Dozen” Threats

The IRS updates its Dirty Dozen list every year to help taxpayers stay one step ahead of evolving scams. The biggest takeaway is simple: if something sounds too good to be true, it probably is. Protect yourself by verifying all sources, filing honestly, and consulting legitimate tax professionals when in doubt. Staying alert and skeptical is the best defense against losing your money—or your identity—to these sophisticated fraudsters.

Have you ever come across one of these tax scams or spotted suspicious activity during tax season? Share your experience or advice in the comments below!

What to Read Next…

6 Reasons the IRS Is Flagging More Trusts in 2025

The Financial Clue That Tells the IRS You’re Hiding Assets

6 Credit Card Reward Scams That Cost You More Than You Earn

What Happens When Joint Account Owners Fall Into Scams Together?

8 Email Formats That Signal a Financial Scam in Disguise

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: tax tips Tagged With: cybersecurity, financial safety, IRS scams, Personal Finance, phishing, tax fraud, tax season tips, taxes

Why an Enormous Tax Refund Is Actually a Bad Sign for Your Finances

October 12, 2025 by Travis Campbell Leave a Comment

tax
Image source: pexels.com

Every spring, millions of Americans eagerly await their tax refunds. For some, receiving a big check from the IRS feels like a financial windfall. It’s common to hear people brag about getting thousands back at tax time, treating it as a reward for a year of hard work. But is this really something to celebrate? When you dig deeper, you’ll see that an enormous tax refund is actually a bad sign for your finances. Understanding why can help you take control of your money and use your income more effectively throughout the year.

If you’re aiming for smart money management, your goal shouldn’t be a huge refund. Instead, you should strive for a balanced approach—one that lets you keep more of your paycheck when you earn it. Let’s look at the real reasons why a large tax refund can be a warning sign that something is off in your financial planning.

1. You’re Giving the Government an Interest-Free Loan

The main reason an enormous tax refund is a bad sign for your finances is simple: you’re letting the government hold onto your money all year, interest-free. When too much is withheld from your paycheck, you’re essentially loaning your hard-earned cash to the IRS, and they don’t pay you any interest in return. That money could be working for you instead.

Imagine if you put that extra cash into a high-yield savings account or used it to pay down credit card debt. You’d earn interest or save on interest payments, making your money grow. Instead, with a big refund, you miss out on those opportunities for months at a time.

2. Missed Opportunities for Saving and Investing

Withholding too much from your paycheck means you have less money available throughout the year. This can make it harder to build an emergency fund, invest for retirement, or reach other financial goals. If you’re waiting for your tax refund to make a big purchase or catch up on bills, you’re not maximizing your financial potential.

By adjusting your tax withholding, you can put more money into your own accounts every month. This regular habit can help you take advantage of compound interest and grow your savings over time. As compound interest shows, even small monthly contributions can add up to significant amounts, especially if you start early.

3. It Signals a Lack of Tax Planning

Receiving an enormous tax refund often points to a lack of proactive tax planning. If you’re not reviewing your tax situation each year, you might miss out on deductions, credits, or other strategies that could keep more money in your pocket now. Good tax planning means understanding how much you owe—and how much you should have withheld—based on your income and life changes.

Life events like getting married, having a child, or starting a side hustle can all impact your tax situation. If you haven’t updated your withholding in years, your refund might be a sign that you’re not paying enough attention. Taking a few minutes to review your W-4 form can make a big difference and help you avoid surprises at tax time.

4. You Could Face Cash Flow Problems

If you’re consistently getting a large tax refund, you might be short-changing yourself throughout the year. More money withheld means smaller paychecks, which can make it difficult to manage monthly expenses, pay off debt, or save for short-term goals. This can lead to relying on credit cards or loans to make ends meet, which creates new financial problems.

Cash flow is key to financial stability. When you get your money as you earn it, you have more flexibility to handle unexpected expenses or take advantage of opportunities. A big tax refund means you’ve been living with less, only to get a lump sum later—money that could have made your life easier all year long.

5. It Can Encourage Unwise Spending

Getting a large tax refund can feel like a bonus, but this mindset can lead to poor financial decisions. Many people see their refund as “found money” and end up splurging on things they don’t really need. This can undermine your progress toward savings goals or debt repayment.

When you receive your money in smaller, regular amounts, you’re more likely to budget wisely and make thoughtful choices. A big, unexpected windfall, on the other hand, can tempt you to spend impulsively. If you want to make the most of your income, it’s better to plan for steady, predictable paychecks.

How to Adjust Your Withholding and Take Control

The good news is that you can fix this problem. If you’ve realized that an enormous tax refund is a bad sign for your finances, it’s time to take action. Start by reviewing your most recent tax return and your current W-4 form. The IRS offers a helpful tax withholding estimator that can guide you through the process. Make adjustments so that you get closer to breaking even at tax time—owing a small amount or receiving a modest refund is ideal.

By taking control of your withholding, you’ll have more money available throughout the year. You can use it to pay down debt, boost your emergency fund, or invest for your future. Remember, your goal shouldn’t be a huge refund; it should be using your money wisely all year long. If you’re proactive, you can avoid giving the government an interest-free loan and start building real financial security.

Have you ever adjusted your tax withholding after getting a large refund? How did it change your approach to your finances? Share your experience in the comments below!

What to Read Next…

  • Are You Reading the Right Fine Print on Your Tax Refund?
  • What Tax Preparers Aren’t Warning Pre-Retirees About in 2025
  • 6 Tax Moves That Backfire After You Sell a Property
  • 5 Ways Missing One Tax Form Can Cost Your Heirs Thousands
  • 7 Tax Breaks That Sound Generous but Cost You Later
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: tax tips Tagged With: Cash flow, Financial Tips, Personal Finance, tax planning, tax refund, withholding

10 Lesser-Known Tax Rules That Cost Households Big Money

August 31, 2025 by Travis Campbell Leave a Comment

tax
Image source: pexels.com

Tax season can feel overwhelming, especially when you realize how many tax rules are tucked away in the fine print. Many households miss out on savings or end up paying more than they should because they don’t know about certain lesser-known tax rules. These overlooked details can quietly drain your wallet year after year. Understanding them is key to keeping more of your hard-earned money. Let’s break down 10 of the most important lesser-known tax rules that cost households big money—and what you can do about them.

1. The Kiddie Tax on Unearned Income

Think your child’s investment gains are taxed at their lower rate? Not always. The “kiddie tax” applies when children under 19 (or under 24 if full-time students) have unearned income above a set threshold. That income can be taxed at your higher rate, not theirs. Many parents are surprised when their kids’ summer dividends push them into a higher tax bracket. To avoid an unexpected bill, monitor all investment accounts in your child’s name.

2. Limits on State and Local Tax Deductions (SALT Cap)

The IRS limits the deduction for state and local taxes to $10,000 per year ($5,000 if married filing separately). If you live in a high-tax state, this rule can raise your federal tax bill by thousands. Households with high property taxes are especially affected. Consider this cap when budgeting for homeownership or evaluating your overall tax strategy.

3. Mortgage Interest Deduction Changes

Many homeowners count on the mortgage interest deduction, but recent changes mean only interest on up to $750,000 of mortgage debt is deductible for loans taken after December 15, 2017. If you bought a home before that date, you may qualify under the old $1 million limit. Refinancing or moving could impact your eligibility, so check the details before making big decisions.

4. The Alternative Minimum Tax (AMT)

The Alternative Minimum Tax was designed to prevent wealthy taxpayers from avoiding taxes, but it can affect upper-middle-class households, too. Certain deductions like state taxes and miscellaneous expenses are not allowed under AMT, which can lead to a higher tax bill than expected. If you regularly exercise incentive stock options or claim a large number of deductions, check whether you may be subject to the AMT. This is one of those lesser-known tax rules that cost households big money without warning.

5. Taxation of Social Security Benefits

Many retirees are surprised to learn that up to 85% of their Social Security benefits may be taxable, depending on their total income. If you have other sources of income—like pensions, part-time work, or withdrawals from retirement accounts—those can push you over the threshold. Planning withdrawals carefully can help reduce the tax hit on your benefits.

6. Penalties for Early Retirement Account Withdrawals

Need to tap your IRA or 401(k) before age 59½? Unless you qualify for a specific exception, you’ll pay a 10% penalty on top of regular income tax. Some exceptions exist, like for first-time homebuyers or certain medical expenses, but the rules are strict. Failing to plan withdrawals properly is one of those lesser-known tax rules that cost households big money, especially during emergencies.

7. The “Wash Sale” Rule for Capital Losses

If you sell a security at a loss and buy it back within 30 days, the IRS disallows the loss for tax purposes. This is called the “wash sale” rule. Many investors accidentally trigger this rule when trying to harvest tax losses. To avoid losing out on valuable deductions, wait the full 30 days before repurchasing the same or substantially identical investment.

8. Taxation of Health Savings Account (HSA) Withdrawals

HSAs provide excellent tax benefits, but only if you use withdrawals for qualified medical expenses. Non-qualified withdrawals before age 65 are subject to income tax and a 20% penalty. After age 65, you can withdraw for any reason without a penalty, but non-medical withdrawals are still taxed as income. Keep good records and save receipts to avoid costly mistakes.

9. Missed Education Credits

Education credits like the American Opportunity Tax Credit and Lifetime Learning Credit can shave thousands off your tax bill. But many households miss out by not claiming expenses or misunderstanding eligibility. For example, you can’t double-dip by claiming both credits for the same student.

10. Dependent Care FSA Forfeitures

If you contribute to a Dependent Care Flexible Spending Account, unused funds generally don’t roll over. If you don’t use the money by the deadline, you lose it. Many families overestimate their dependent care expenses, leaving hundreds or thousands on the table. Plan contributions carefully and track expenses throughout the year to maximize these tax benefits.

How to Avoid These Costly Tax Surprises

Staying informed about lesser-known tax rules that cost households big money can make a huge difference in your annual tax bill. Small missteps add up fast, while a little research and planning can keep more money in your pocket. Tax laws change often, so it’s wise to review your situation every year and consult trusted resources like the IRS website or a qualified tax professional.

What confusing tax rules have caught you off guard? Share your experiences or questions in the comments below!

What to Read Next…

  • 7 Tax Breaks That Sound Generous But Cost You Later
  • 6 Tax Breaks That Vanished Before Anyone Noticed
  • 5 Ways Missing One Tax Form Can Cost Your Heirs Thousands
  • 6 Tax Moves That Backfire After You Sell A Property
  • What Tax Preparers Aren’t Warning Pre Retirees About In 2025
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: tax tips Tagged With: household taxes, Personal Finance, retirement planning, Tax Deductions, tax rules

7 Things Wealthy Families Do With Taxes That Ordinary People Never Hear About

August 29, 2025 by Travis Campbell Leave a Comment

tax
Image source: pexels.com

When it comes to taxes, most people just want to file on time and hope for a refund. But for wealthy families, taxes are a completely different game. They don’t just react during tax season; they plan all year round. The strategies they use can seem almost invisible to the rest of us. Yet, understanding these advanced moves can be eye-opening. If you want to build lasting wealth or just get smarter with your own finances, it pays to learn what the wealthy are doing with their taxes that most people never even hear about.

1. Setting Up Family Limited Partnerships

Family Limited Partnerships (FLPs) are a common tool among wealthy families for tax planning. An FLP lets family members pool assets—like investments or real estate—into a partnership. The senior family members usually retain control, while gradually transferring ownership to younger generations. This move can help reduce estate taxes and protect assets from creditors.

By gifting partnership interests, families can also take advantage of valuation discounts. In simple terms, the value of what’s gifted is considered lower for tax purposes because it’s harder to sell a minority interest in a partnership. This is a technique rarely used by ordinary taxpayers, but it can make a huge difference in long-term tax planning for wealthy families.

2. Leveraging Grantor Retained Annuity Trusts (GRATs)

One of the best-kept secrets in wealthy families and taxes is the use of Grantor Retained Annuity Trusts, or GRATs. These trusts allow the wealthy to transfer appreciating assets—like stocks or private business shares—to heirs with little or no estate tax.

The idea is simple: the grantor puts assets into the trust and receives an annuity for a set period. If the assets grow faster than the IRS’s assumed rate, the excess passes to heirs tax-free. For families with significant assets, this can mean millions saved over time. Most people have never even heard of GRATs, but they’re a staple for tax-savvy families with wealth to protect.

3. Using Donor-Advised Funds for Charitable Giving

Wealthy families often approach charitable giving differently from most. Instead of writing checks here and there, they set up Donor-Advised Funds (DAFs). These funds let them make a large, tax-deductible donation upfront, then recommend grants to charities over time.

This approach offers two major perks: a big immediate tax deduction and the ability to invest the donated money for potential growth before it’s given away. DAFs are easy to set up through major financial institutions. For families who want to support causes and manage their tax bill, it’s a win-win. Ordinary taxpayers rarely use this strategy, but it’s become a go-to for those focused on both philanthropy and tax efficiency.

4. Timing Income and Deductions Strategically

Wealthy families don’t just accept whatever income comes their way each year. They work with advisors to time when they receive income or claim deductions. For example, they might delay a bonus until the following year if it means falling into a lower tax bracket. Or, they may bunch deductions—like charitable donations or medical expenses—into a single year to maximize their tax benefit.

This level of planning takes foresight and often involves close coordination with accountants and legal experts. It’s a proactive approach that helps minimize taxes over time. While anyone can technically do this, most people aren’t aware of how much timing matters when it comes to wealthy families and taxes.

5. Investing in Tax-Efficient Assets

Another move that separates wealthy families from the rest is their focus on tax-efficient investing. They seek out municipal bonds, which are often exempt from federal (and sometimes state) taxes. They also invest in index funds or ETFs that generate fewer taxable events than actively managed funds.

Some also use strategies like tax-loss harvesting—selling losing investments to offset gains elsewhere. These techniques help wealthy families keep more of their investment returns. For average investors, these ideas might seem advanced, but learning about them can help anyone improve their after-tax returns.

6. Creating Irrevocable Life Insurance Trusts

Life insurance can be more than just a safety net. Wealthy families use Irrevocable Life Insurance Trusts (ILITs) to keep life insurance payouts out of their taxable estate. By placing a policy inside an ILIT, the death benefit goes directly to heirs without triggering estate taxes.

This move is particularly useful for families with large estates who want to provide liquidity for heirs or cover estate taxes without selling off assets. It’s a sophisticated strategy, but it’s one more way that wealthy families and taxes are linked through careful planning.

7. International Tax Planning and Residency Strategies

Some wealthy families look beyond the U.S. for tax solutions. They might establish residency in a state with no income tax, or even in another country with more favorable tax laws. This isn’t just for billionaires—families with significant assets sometimes relocate for tax reasons.

International tax planning can involve complex rules and reporting requirements. It’s not something to try without expert help, but it highlights just how far some families will go to optimize their tax situation.

Learning From the Wealthy: Practical Takeaways

Even if you don’t have a family office or millions in assets, you can still learn from how wealthy families handle taxes. Their secret isn’t just having more money—it’s using the tax code to their advantage. By understanding strategies like FLPs, GRATs, and donor-advised funds, you can start asking better questions and planning further ahead. The rules for wealthy families and taxes might be complicated, but the basic idea is simple: be proactive, not reactive.

Ready to dig deeper? What’s one tax strategy you wish you’d learned sooner? Share your thoughts below!

What to Read Next…

  • 7 Tax Breaks That Sound Generous But Cost You Later
  • 5 Ways Missing One Tax Form Can Cost Your Heirs Thousands
  • What Tax Preparers Aren’t Warning Pre Retirees About In 2025
  • 6 Tax Breaks That Vanished Before Anyone Noticed
  • 6 Tax Moves That Backfire After You Sell A Property
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: tax tips Tagged With: charitable giving, Estate planning, family finance, tax planning, tax strategies, Wealth management

7 Ways Digital Advisors Trigger Unexpected Tax Consequences

August 21, 2025 by Travis Campbell Leave a Comment

taxes
Image source: pexels.com

Digital advisors, also known as robo-advisors, have made investing easier and more accessible than ever. With low fees and automated portfolio management, they seem like the perfect solution for hands-off investors. But behind the convenience, digital advisors can sometimes trigger unexpected tax consequences. If you’re not paying attention, these surprises can chip away at your investment gains. This is especially important if you’re working toward long-term goals like retirement or college savings. Understanding how digital advisors impact your tax bill is key to making smart financial decisions and keeping more of your hard-earned money.

1. Automated Tax-Loss Harvesting Gone Wrong

Many digital advisors tout tax-loss harvesting as a benefit. They automatically sell investments at a loss to offset gains elsewhere in your portfolio. While this can reduce your current year’s tax bill, it’s not always a win. If losses are harvested too aggressively, you might end up with a portfolio full of similar assets, which can set you up for higher taxes in the future when those investments rebound and are eventually sold for a gain. It’s also possible to violate the IRS wash-sale rule if you (or your spouse) buy the same or a “substantially identical” security within 30 days, making the loss ineligible for deduction.

2. Capital Gains Surprises from Rebalancing

One of the main appeals of digital advisors is automatic portfolio rebalancing. This keeps your investments aligned with your risk tolerance and goals. However, rebalancing often involves selling assets that have appreciated, triggering capital gains taxes. If your digital advisor doesn’t consider your overall tax situation or coordinate with your other accounts, you could face a larger-than-expected tax bill come April. This is especially true if your portfolio is held in a taxable account, rather than a tax-advantaged one like an IRA or 401(k).

3. Overlooking State Tax Implications

Digital advisors typically focus on federal tax consequences, but state taxes can differ significantly. Some states tax capital gains at higher rates or have unique rules for certain investments. If your digital advisor isn’t programmed to consider your state’s tax laws, you might end up owing more than you expect. For example, municipal bond interest may be tax-free at the federal level, but not in every state. Always double-check how your digital advisor’s strategies will impact your state tax bill.

4. Dividend Income Creep

Many digital advisors favor dividend-paying stocks or funds for their stability and income potential. While dividends can be great for cash flow, they’re also taxable—even if you reinvest them. If your digital advisor doesn’t take your income tax bracket into account, you may find yourself in a higher bracket or paying more in taxes than you anticipated. Qualified dividends are taxed at a lower rate, but non-qualified dividends are taxed as ordinary income. Make sure you know what kind of dividends your digital advisor is generating for you.

5. Missed Opportunities for Tax Deferral

Some digital advisors default to placing your investments in taxable accounts for simplicity. But this can mean missing out on tax deferral benefits available in retirement accounts like IRAs or 401(k)s. Without proper guidance, you might end up paying taxes on investment gains and income annually, instead of letting them grow tax-deferred until retirement. This can significantly reduce your long-term returns. When using a digital advisor, make sure you’re using the right account types for your goals and tax situation.

6. Ignoring Your Broader Financial Picture

Most digital advisors optimize your portfolio based on the information you provide—usually just the assets you invest with them. They don’t always factor in other accounts you hold elsewhere, such as employer-sponsored retirement plans or brokerage accounts. This siloed approach can result in unexpected tax consequences, like duplicated investments or missed opportunities to offset gains and losses across all your holdings. To avoid this, look for digital advisors that allow you to connect external accounts or work with a financial planner who can see your entire financial landscape.

7. Inadvertent Short-Term Gains

Digital advisors may make frequent trades to keep your portfolio balanced or to harvest tax losses. But if they sell investments held for less than a year, those gains are taxed at higher short-term rates, which are the same as ordinary income. This can lead to a much bigger tax bite than if gains were realized after holding investments for over a year, qualifying them for lower long-term capital gains rates. Always check your advisor’s trading frequency and ask how they minimize short-term taxable gains.

How to Stay Ahead of Digital Advisor Tax Surprises

Digital advisors offer convenience and automation, but their algorithms don’t always catch the nuances of your personal tax situation. Before committing, review how your digital advisor handles tax-loss harvesting, rebalancing, and account types. Consider connecting all your investment accounts, or work with a human advisor to catch things that algorithms might miss. Tax laws can be complex and change frequently, so staying informed is crucial.

Have you run into unexpected tax consequences with a digital advisor? Share your experience or questions in the comments below!

Read More

5 Account Transfers That Unexpectedly Trigger IRS Penalties

7 Ill Advised Advisor Tips That Trigger IRS Audits

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: tax tips Tagged With: capital gains, digital advisors, investment tax, Personal Finance, robo-advisors, tax planning, tax-loss harvesting

  • « Previous Page
  • 1
  • …
  • 13
  • 14
  • 15
  • 16
  • 17
  • …
  • 21
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework