• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Health & Wellness

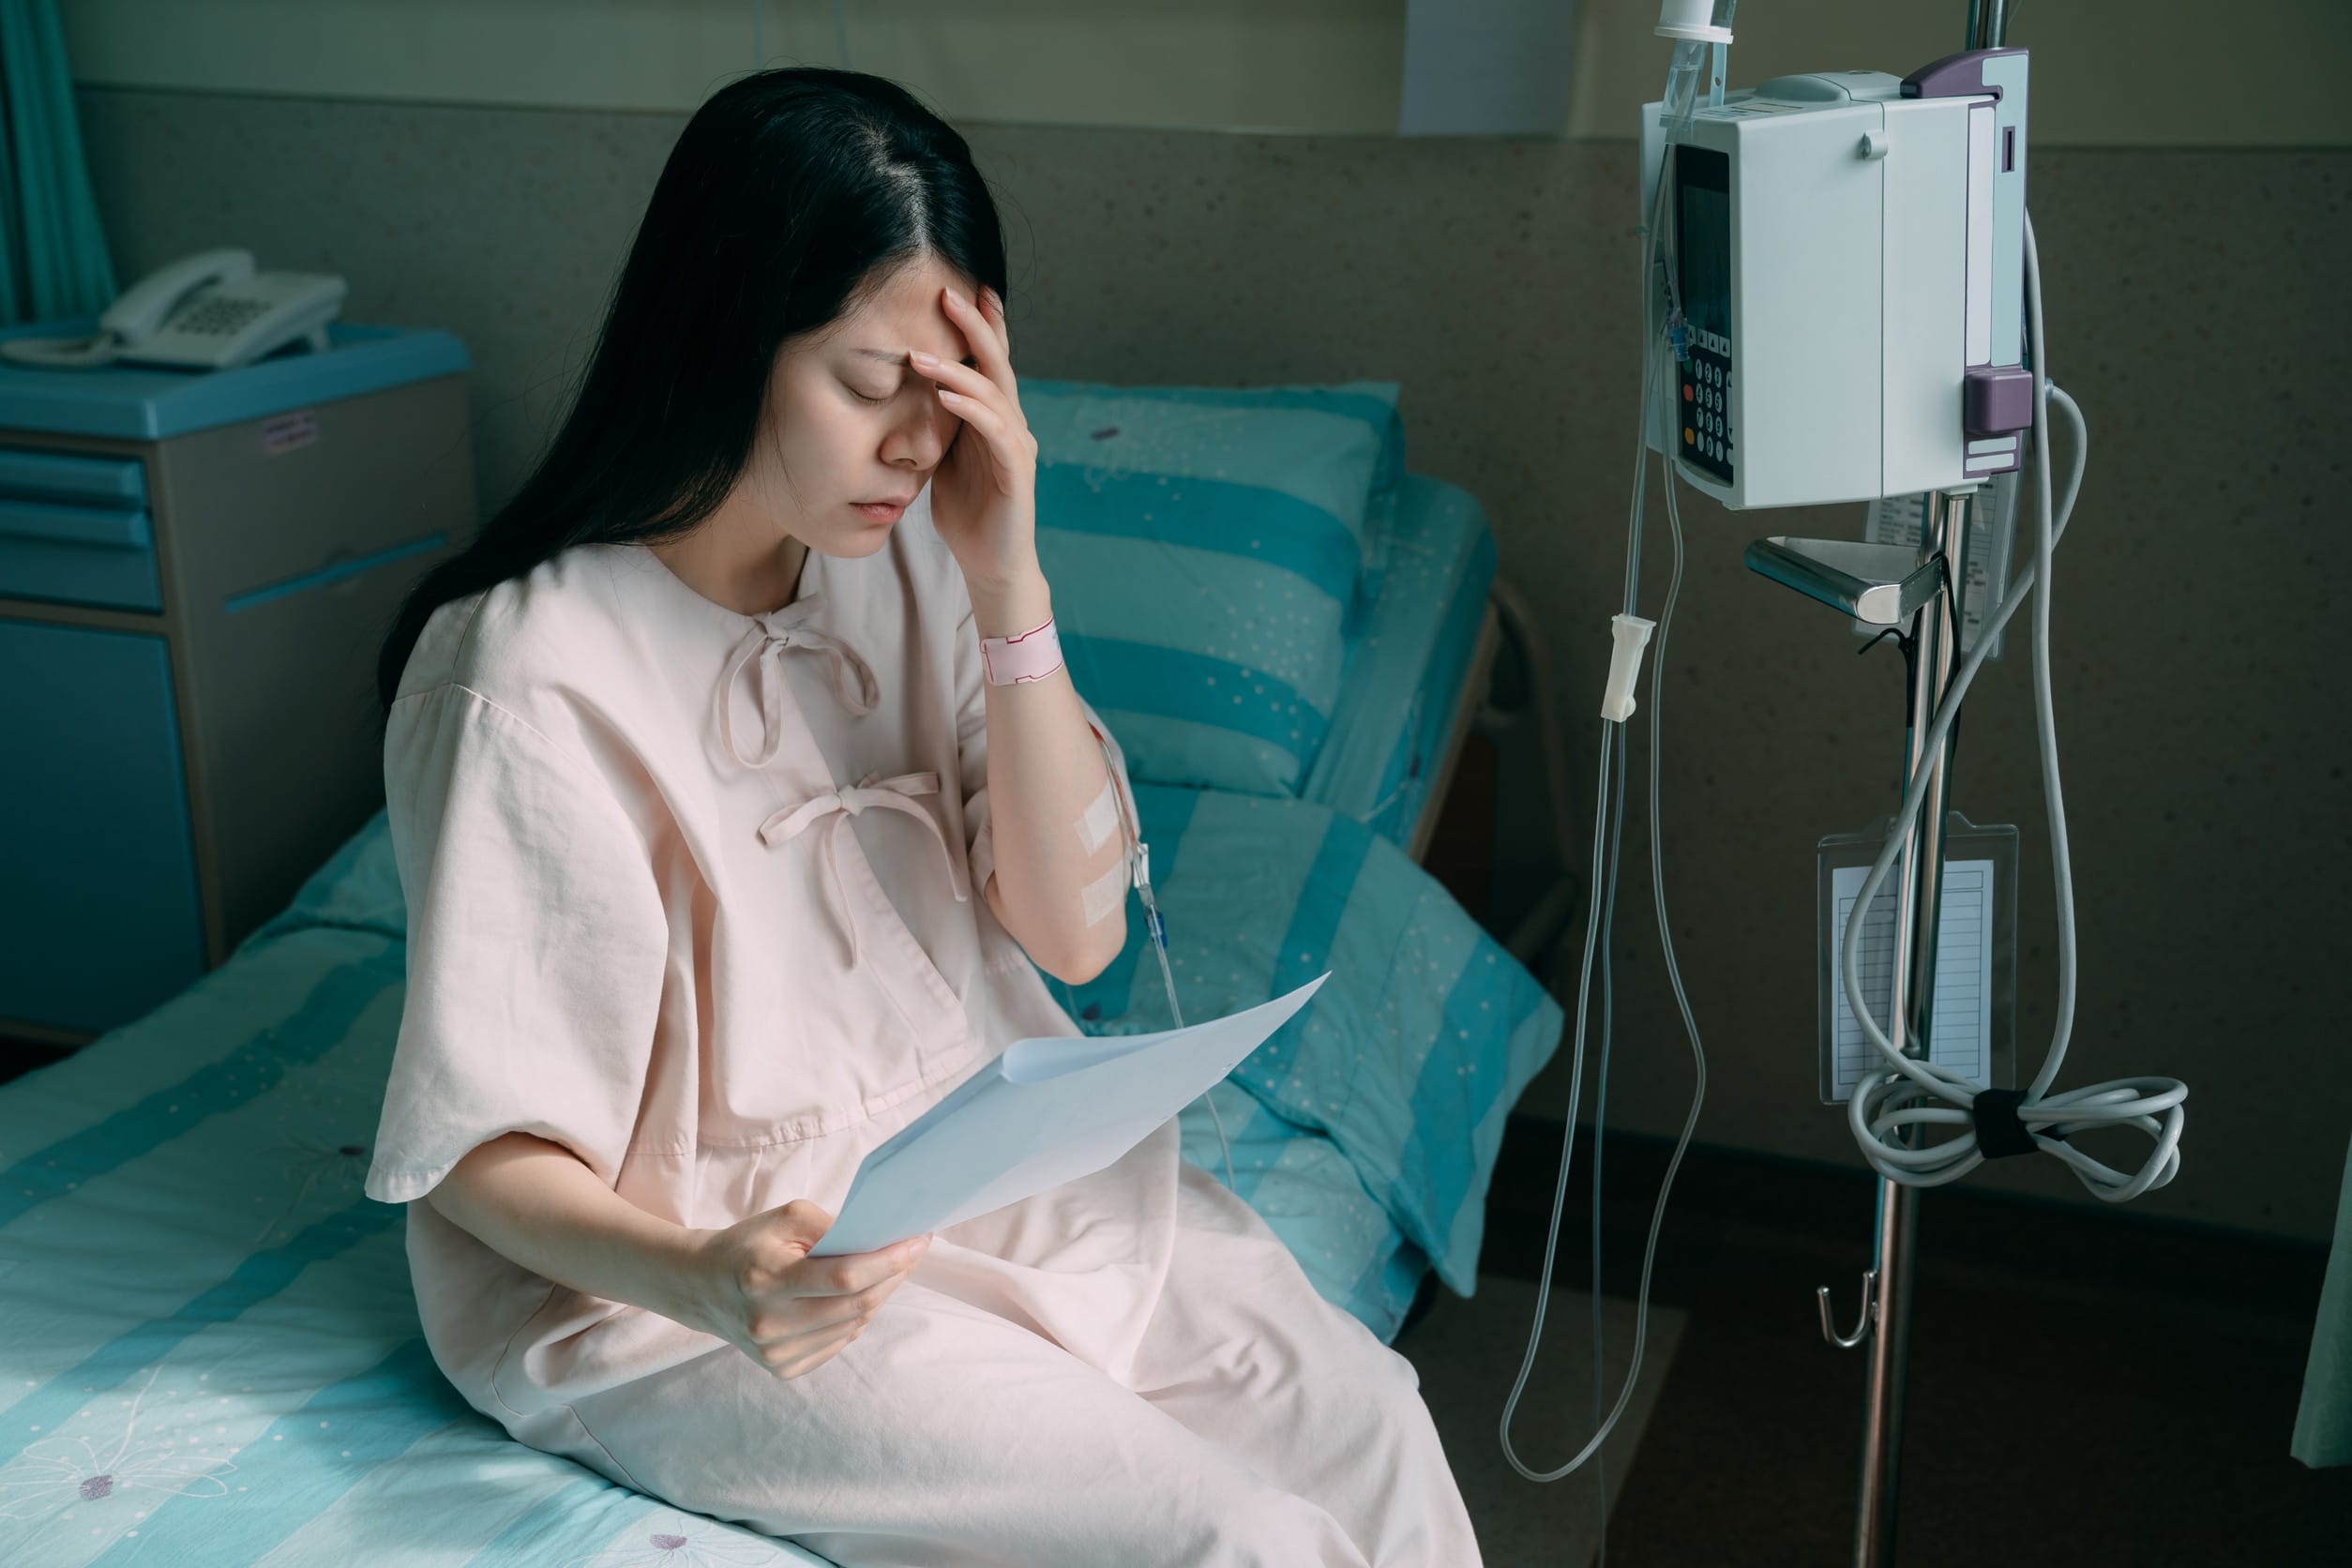
Could A Single Emergency Room Visit Bankrupt You

September 29, 2025 by Catherine Reed Leave a Comment

Could A Single Emergency Room Visit Bankrupt You
Image source: 123rf.com

No one plans for a sudden accident or unexpected illness, but millions of Americans discover just how expensive emergency care can be. Even with insurance, bills pile up quickly and catch families off guard. The shocking reality is that a single emergency room visit bankrupt you if you’re not financially prepared. Between hidden fees, unpredictable charges, and coverage loopholes, the financial fallout can be devastating. Here are some of the biggest reasons why one trip to the ER can threaten your financial stability.

1. The High Cost of ER Services

Emergency rooms are some of the most expensive places to receive medical care. A simple visit for stitches or a sprain can run into thousands of dollars before you even see the final bill. Charges often include facility fees, doctor’s fees, lab work, and imaging. When all of these add up, families may struggle to pay even for minor incidents. It’s one of the main reasons a single emergency room visit bankrupt you despite having what feels like routine care.

2. Surprise Out-of-Network Charges

Even if the hospital is in your insurance network, not every provider inside the ER is. Doctors, specialists, or anesthesiologists may bill separately at out-of-network rates. These surprise bills catch many patients by shock after an already stressful experience. The costs are often thousands more than expected and may not be negotiable. Out-of-network providers are a huge factor in why a single emergency room visit bankrupt you without warning.

3. Insurance Deductibles and Copays

Insurance plans often advertise coverage, but deductibles can be painfully high. If you haven’t met your deductible, you may be responsible for paying most of the bill out of pocket. Even after that, copays for ER visits are far higher than for a regular doctor’s office. Families with limited savings can find themselves maxing out credit cards to cover these expenses. This is another way a single emergency room visit bankrupt you, even when insured.

4. Additional Testing and Imaging

ER doctors are trained to rule out serious conditions, which means ordering extra tests. CT scans, MRIs, and blood panels are common, even for relatively minor symptoms. While these tests are medically justified, their costs skyrocket quickly. Patients rarely know the price upfront, leaving them with sticker shock later. Unnecessary or excessive testing contributes heavily to how a single emergency room visit bankrupt you unexpectedly.

5. Prescription Costs After Discharge

Leaving the ER doesn’t mean the expenses stop. Patients are often prescribed medications that may not be fully covered by insurance. Painkillers, antibiotics, or specialized drugs can cost hundreds of dollars out of pocket. Some patients may need ongoing treatment that stretches the financial impact even further. Post-discharge prescriptions are yet another way a single emergency room visit bankrupt you in the days that follow.

6. Lost Wages from Time Off Work

Medical emergencies don’t just cost money at the hospital—they can cost you income too. If you’re forced to miss work for recovery or follow-up care, the financial hit grows larger. For those without paid sick leave, the loss of income compounds the burden. Even a short absence can cause missed rent or bill payments. Lost wages make it easier for a single emergency room visit bankrupt you in more ways than one.

7. Interest and Collections on Unpaid Bills

Not everyone can pay ER bills immediately, and hospitals often turn debts over to collections. Once this happens, interest and late fees inflate the balance significantly. Medical debt collectors may call relentlessly, adding stress to an already difficult situation. Even if you try to negotiate, the damage to your credit score can be lasting. This cycle of debt is one of the most painful ways a single emergency room visit bankrupt you over time.

8. Long-Term Financial Ripple Effects

The financial effects of a medical emergency often extend far beyond the initial bill. Families may delay saving for retirement, paying off debt, or funding education just to manage hospital costs. Some are forced to take out high-interest loans, further trapping them in a cycle of debt. Even those who recover medically may never fully recover financially. The long-term burden is why a single emergency room visit bankrupt you more easily than most expect.

Protecting Yourself Against Medical Debt

The hard truth is that one emergency can put even financially responsible families at risk. Preparing with emergency savings, understanding insurance coverage, and negotiating bills can make a difference. Exploring options like health savings accounts or supplemental insurance can also provide a cushion. While no one can predict when they’ll need urgent care, being proactive helps reduce the chance that a single emergency room visit bankrupt you. Planning ahead ensures that an accident doesn’t derail your financial future.

Have you or someone you know faced financial struggles from a single ER trip? Share your experiences and thoughts in the comments below.

What to Read Next…

6 Popular Fitness Influencers Caught Promoting Dangerous Routines

7 Outrageous Truths About Medical Debt

9 Expenses That Quietly Rise After Retirement

6 End-of-Life Decisions That Families Always Regret Later

5 Surprising Costs Older Parents Face When Raising Kids Later in Life

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Health & Wellness Tagged With: emergency room visit bankrupt you, ER bills, family finances, financial risks, healthcare costs, hidden medical expenses, medical debt

8 Shocking Costs of Ignoring Small Medical Bills

September 26, 2025 by Travis Campbell Leave a Comment

medical bills
Image source: pexels.com

Many people brush off small medical bills, assuming a $50 or $100 charge isn’t worth worrying about. But ignoring these expenses can quickly spiral into much larger problems. The healthcare system in the U.S. is complex, and even minor unpaid balances can trigger a cascade of financial headaches. While it’s tempting to put off payment or assume a bill will just “go away,” that’s rarely how things work out. In fact, the costs of ignoring small medical bills often go far beyond the original amount owed. Understanding these consequences can help you avoid unnecessary stress and protect your financial health.

1. Damage to Your Credit Score

One of the most significant consequences of ignoring small medical bills is the impact on your credit score. Even a minor unpaid balance can end up on your credit report if it goes to collections. Medical providers may wait a few months before sending unpaid bills to a collection agency, but once they do, the impact can be long-lasting. A single collections account can lower your credit score by dozens of points, making it harder to qualify for loans, credit cards, or even rental housing. Repairing your credit after a medical collections event can take years, and the negative mark may remain on your report for up to seven years.

2. Accumulating Late Fees and Interest

Small medical bills don’t just sit quietly when ignored. Many providers add late fees or interest to unpaid balances. These extra charges can quickly add up, sometimes doubling or tripling the original amount owed. What started as a manageable expense can balloon into a significant debt. The longer you wait, the more you’ll end up paying in the end—simply because you didn’t address the bill promptly.

3. Collection Agency Harassment

When you ignore small medical bills, there’s a strong chance they’ll be handed over to collection agencies. These agencies are persistent, often calling, emailing, or sending letters to demand payment. Repeated contacts can be stressful and disruptive, especially if they reach you at work or contact your family members. The stress of dealing with aggressive collectors is a high price to pay for avoiding a minor bill. In some cases, collectors may even threaten legal action if the debt remains unpaid.

4. Loss of Access to Healthcare Providers

If you ignore medical bills from your doctor, clinic, or hospital, you might find yourself unable to schedule future appointments. Many providers have policies that restrict access to patients with unpaid balances. This means you could be denied care or forced to pay the entire debt before receiving additional treatment. Ignoring small medical bills can ultimately put your health at risk if you’re unable to see your preferred healthcare professionals when you need them.

5. Legal Action and Court Judgments

It might sound extreme, but unpaid small medical bills can sometimes lead to lawsuits. If a provider or collection agency decides to pursue legal action, you could face court fees and, if you lose, a judgment against you. Court judgments can lead to wage garnishment or bank account levies, making the original bill seem trivial by comparison. Legal trouble is a major cost of ignoring small medical bills that few people anticipate.

6. Difficulty Obtaining Loans or Credit

Having unpaid medical bills on your credit report can significantly increase the difficulty of obtaining approval for loans, credit cards, or even a mortgage. Lenders see unpaid medical debt as a red flag, even if the original amount was small. You may be offered higher interest rates or denied credit altogether. The cost of higher borrowing rates over time can be substantial, far outweighing the original bill.

7. Increased Insurance Premiums

Some insurance companies check your credit report when setting premiums for auto, home, or even life insurance. If small medical bills have damaged your credit, you could face higher monthly premiums. Over time, these increased costs add up. Ignoring small medical bills can have a ripple effect, making everything from car insurance to renters’ insurance more expensive.

8. Emotional Stress and Anxiety

Financial stress is one of the most common sources of anxiety for Americans. Ignoring small medical bills doesn’t make them disappear—instead, it often leads to ongoing worry about debt collectors, legal action, or damaged credit. This emotional toll can affect your sleep, relationships, and even your physical health. Paying attention to small medical bills helps maintain peace of mind and prevents stress from escalating into more significant problems.

How to Handle Small Medical Bills Proactively

Small medical bills may seem insignificant at first, but as you’ve seen, the costs of ignoring small medical bills can be surprisingly high. The best approach is to address these bills as soon as you receive them. Review each bill carefully to ensure it’s accurate, and don’t hesitate to ask your provider or insurer for clarification if something looks off. If you can’t pay the full amount right away, ask about payment plans or financial assistance options. Many providers are willing to work with you—especially when you communicate early and honestly.

Staying on top of your medical expenses not only protects your credit and finances but also gives you peace of mind. Have you ever had a small medical bill turn into a big problem? Share your experiences in the comments below!

What to Read Next…

  • Can An Unpaid Medical Bill Really Lead To Property Seizure?
  • 5 Emergency Repairs That Could Force You Into Debt Overnight
  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • 7 Financial Assumptions That Collapse After One Health Emergency
  • 10 Money Mistakes People Make After Losing A Spouse
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Health & Wellness Tagged With: credit score, debt collection, Financial Health, insurance premiums, medical bills

9 Expenses That Quietly Rise After Retirement

September 22, 2025 by Travis Campbell Leave a Comment

medication
Image source: pexels.com

Planning for retirement is about more than just saving enough. It also means preparing for how your spending might change. Many people expect their expenses to decrease once they stop working. While some costs do drop, others quietly creep up, often catching new retirees off guard. Managing your retirement budget means knowing which costs are likely to increase. Understanding these shifts helps you avoid surprises and stretch your savings further. In this article, we’ll highlight nine expenses that quietly rise after retirement so that you can plan with confidence.

1. Healthcare Costs

Healthcare is one of the most significant expenses that quietly rise after retirement. Even with Medicare, out-of-pocket costs for premiums, copays, prescriptions, dental, and vision can add up fast. As you age, you may need more frequent doctor visits, tests, and treatments. Many retirees are surprised by how much they spend on healthcare each year. Planning for these growing expenses helps you avoid dipping into your savings unexpectedly.

2. Prescription Medications

The cost of prescription drugs tends to rise as you get older. Chronic conditions, new diagnoses, and changes in insurance coverage can all push this expense higher. Even with Medicare Part D or other prescription plans, not every medication is covered. Some drugs require significant out-of-pocket payments or regular refills. Make sure to include rising medication costs in your retirement budget so you aren’t caught off guard.

3. Long-Term Care

Many retirees underestimate the likelihood of needing long-term care. Assisted living, in-home care, or nursing facilities can be costly. Medicare doesn’t typically cover these costs, and private insurance may only go so far. If you or your spouse eventually needs assistance with daily activities, the expense can quickly deplete your nest egg. Considering long-term care insurance or setting aside funds early is a smart way to prepare for this expense that quietly rises after retirement.

4. Home Maintenance and Repairs

With more time spent at home, you may notice things that need fixing or updating. Appliances wear out, roofs need replacing, and routine maintenance can’t be ignored. As homes age, repairs become more frequent and costly. Retirees often take on home improvement projects they put off while working. These expenses can quietly add up, especially if you want your home to remain comfortable and safe as you age.

5. Property Taxes and Insurance

Even if you’ve paid off your mortgage, property taxes, and homeowners’ insurance, you should still keep coming. In many areas, property taxes rise over time, and insurance premiums can increase with inflation or after claims. Retirees on fixed incomes may feel the pinch as these recurring costs quietly rise after retirement. It’s important to review your tax exemptions and shop around for insurance to minimize the impact.

6. Travel and Leisure

Retirement often brings more free time for travel, hobbies, and entertainment. While these activities are enjoyable, their costs can add up quickly. Visiting family, taking cruises, or signing up for classes may become regular parts of your routine. Many retirees find themselves spending more on travel and leisure than they expected, especially in the early years of retirement. Setting aside a dedicated budget for fun ensures you enjoy your retirement without financial stress.

7. Gifts and Charitable Giving

With more time to connect, retirees often increase spending on gifts for grandchildren, family, and friends. Charitable donations may also rise as you support causes close to your heart. Holiday and birthday gifts, special occasions, and contributions to local organizations can quietly push your expenses higher. Tracking these costs helps you stay generous without putting your finances at risk.

8. Utility Bills

Spending more time at home often means higher utility bills. Heating, cooling, electricity, and water usage can all increase after retirement. You might also invest in services like faster internet or streaming subscriptions to stay entertained. These recurring expenses can quietly rise, especially during extreme weather or if you live in a larger home. Energy-efficient upgrades and careful monitoring can help manage these costs.

9. Transportation

Even if you’re no longer commuting, transportation costs don’t disappear. Older vehicles may need more repairs, and you might use rideshares or public transportation more often. Some retirees choose to travel more frequently, which can add to their gas, maintenance, or rental car expenses. If you move to a new area, costs like registration or insurance could change. Keeping an eye on your transportation budget ensures these expenses don’t sneak up on you.

How to Stay Ahead of Rising Retirement Expenses

The key to managing expenses that quietly rise after retirement is awareness and planning. Regularly review your budget, and be honest about where your money goes. Consider working with a financial advisor who understands the unique needs of retirees. They can help you anticipate rising costs and adjust your strategy as needed.

What expenses have surprised you most since retiring? Share your experiences in the comments below!

What to Read Next…

  • Are These 7 Little Expenses Quietly Costing You Thousands a Year?
  • 7 Retirement Perks That Come With Shocking Hidden Costs
  • 6 Monthly Bills You Should Cancel Immediately Even If You Can Afford Them
  • 10 Services Adult Children Regret Paying for Their Parents
  • 7 Costs Retirees Refuse to Pay in 2025 and How You Can Follow Their Lead
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Health & Wellness Tagged With: budgeting, healthcare costs, Long-term care, Personal Finance, property taxes, retirement expenses, retirement planning

Could Cutting Corners on Health Lead to Bankruptcy

September 14, 2025 by Travis Campbell Leave a Comment

health
Image source: pexels.com

Many people look for ways to save money, especially when budgets are tight. Sometimes, that means skipping routine doctor visits, buying cheaper foods, or ignoring medical advice. But cutting corners on health can have serious financial consequences. Medical bills are one of the top reasons people file for bankruptcy in the United States. When you neglect your health, small problems can turn into big, expensive ones. In this article, we’ll look at how saving a little now can cost you a lot later, and why your health and your wallet are more connected than you might think.

1. Skipping Preventive Care Can Backfire

Many people avoid regular checkups or screenings to save on copays or out-of-pocket costs. It seems harmless—after all, if you feel fine, why spend the money? But skipping preventive care is one of the biggest ways that cutting corners on health can lead to bankruptcy. Small health issues, like high blood pressure or early-stage diabetes, often have no symptoms. Left unchecked, they can develop into serious conditions that require expensive treatments or hospital stays.

For example, catching cancer early often means simpler, less costly treatments and a better chance of recovery. Missing these appointments could mean facing a major health crisis down the road—along with overwhelming medical bills. Prevention is almost always cheaper than treatment.

2. Relying on Cheap, Unhealthy Food

On a tight budget, it’s tempting to fill your cart with inexpensive processed foods. Fast food and packaged snacks are easy on your wallet in the short term, but they can take a toll on your body. Diets high in sugar, salt, and unhealthy fats are linked to obesity, heart disease, and type 2 diabetes. Treating these chronic conditions is expensive and can last a lifetime.

The cost of prescription medications, insulin, and even lost workdays adds up. Over time, poor dietary choices can drain your savings and put you at risk of medical bankruptcy. Investing in healthier food—even on a budget—can help you avoid these long-term costs.

3. Ignoring or Delaying Medical Treatment

It’s easy to put off seeing a doctor when you’re worried about the bill. Many people hope that minor symptoms will go away on their own. But delaying care can turn a simple problem into a medical emergency. For example, ignoring tooth pain can lead to infections or even hospitalization. Skipping asthma medication can result in ER visits. These emergencies are not only dangerous—they’re also expensive.

Medical debt from avoidable emergencies is a direct path to bankruptcy for many families. Seeking treatment early, even if it costs a bit more up front, can prevent larger bills and bigger problems later.

4. Dropping Health Insurance to Save Money

Health insurance premiums can feel like a big monthly expense, especially if you’re healthy. Some people decide to drop their coverage, hoping to save money. But this is a risky gamble. Without insurance, even a minor accident or illness can lead to thousands of dollars in bills.

The cost of a broken arm, a hospital stay, or emergency surgery can wipe out savings fast. Medical bankruptcy often happens when people are uninsured and face unexpected health crises. If you’re struggling to afford coverage, look into government programs or subsidies that might help. Affordable health insurance options are available for many families, and having coverage is one of the best ways to protect your finances.

5. Using High-Interest Loans for Medical Bills

When faced with big medical expenses, some people turn to credit cards, payday loans, or other high-interest options. While this might provide short-term relief, it often leads to long-term debt. The interest adds up quickly, making it even harder to pay off bills. Instead of solving the problem, you may end up with both medical debt and high-interest payments.

This cycle can quickly spiral out of control, leading some people straight to bankruptcy. If you’re struggling with medical bills, look for payment plans, financial assistance programs, or nonprofit credit counseling instead of risky loans.

Your Health Is an Investment in Your Finances

Cutting corners on health might seem like a way to save money in the short run, but it’s often a false economy. The link between cutting corners on health and bankruptcy is real. Medical emergencies, chronic illness, and mounting debt can all stem from decisions made to save a few dollars today. Prioritizing preventive care, maintaining insurance, and making healthy choices protect both your well-being and your financial future.

Taking care of your health isn’t just about feeling good—it’s about protecting yourself from the unexpected costs that can lead to bankruptcy. Think of health spending as an investment, not an expense. It can save you money, stress, and heartache in the long run.

Have you or someone you know faced financial trouble because of health costs? Share your experiences or tips in the comments below!

What to Read Next…

  • 7 Financial Assumptions That Collapse After One Health Emergency
  • Can An Unpaid Medical Bill Really Lead To Property Seizure?
  • 5 Emergency Repairs That Could Force You Into Debt Overnight
  • Why Your Long Term Care Policy Might Be Useless After Age 75
  • 10 Money Mistakes People Make After Losing A Spouse
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Health & Wellness Tagged With: health care, Insurance, medical bankruptcy, medical debt, Personal Finance, preventive care

10 Financial Shocks That Hit After a Major Illness

September 13, 2025 by Catherine Reed Leave a Comment

10 Financial Shocks That Hit After a Major Illness
Image source: 123rf.com

A major illness can turn life upside down, and the challenges extend far beyond the physical toll. Even with good insurance, families often face unexpected bills and money struggles that few are prepared for. These financial shocks hit quickly, drain savings, and sometimes create long-lasting debt. Knowing what to expect is the first step in protecting your household against these hidden costs. Here are ten common financial shocks that strike after a major illness.

1. Out-of-Pocket Medical Costs

One of the most immediate financial shocks comes from out-of-pocket medical expenses. Even with insurance, deductibles, copayments, and uncovered treatments can add up to thousands of dollars. Families often underestimate just how high these costs can climb during extended treatment. Routine medications and follow-up visits only add to the total. This sudden financial burden can wipe out emergency funds in a matter of weeks.

2. Lost Income From Missed Work

A major illness often means extended time away from work, leading to reduced paychecks or no income at all. Not every employer offers paid sick leave or short-term disability benefits. Even when they do, the payments rarely cover a full salary. This gap creates one of the hardest-hitting financial shocks for families. Bills don’t stop just because someone is sick, making lost wages one of the biggest challenges to overcome.

3. Travel and Lodging Expenses

Serious illnesses sometimes require care at specialty hospitals that are far from home. Families must pay for travel, hotel stays, and meals during treatment. These extra costs pile up quickly, especially when multiple family members want to be present. Insurance rarely covers these types of expenses. For many, the hidden cost of travel is a financial shock that drains credit cards fast.

4. Increased Childcare or Elder Care Needs

When a parent or caregiver falls ill, someone else must step in to care for children or aging relatives. Hiring extra childcare or elder care can become one of the most surprising financial shocks. The costs are ongoing and often more expensive than families expect. Even short-term arrangements can create significant strain on budgets. This added expense complicates an already difficult financial situation.

5. Home Modifications and Medical Equipment

A major illness sometimes requires changes at home, such as installing ramps, stair lifts, or accessible bathrooms. Medical equipment like hospital beds, wheelchairs, or oxygen machines may also be needed. Insurance coverage for these items is often limited, leaving families to cover much of the cost. These modifications can run into the tens of thousands of dollars. The sudden need for major adjustments adds another layer of financial shock.

6. Rising Insurance Premiums

After a major illness, many families see their health insurance premiums rise significantly. Employers may pass more of the cost to employees, or individuals may face higher rates when purchasing private coverage. These increases arrive just as finances are already stretched thin. Over time, rising premiums become one of the long-term financial shocks families must budget for. They represent a lasting consequence of an already difficult health crisis.

7. Mental Health and Counseling Costs

The stress of dealing with a major illness often extends to mental health. Counseling, therapy, or medication may be necessary for both the patient and family members. Insurance coverage for these services can be limited, leaving families to pay out of pocket. These costs are easy to overlook but add up quickly. The emotional strain paired with the financial shocks can feel overwhelming.

8. Debt From Credit Card Use

When savings run out, many families turn to credit cards to cover expenses. High interest rates make repayment difficult, and balances grow faster than expected. This type of debt is one of the most common financial shocks after a major illness. What starts as a temporary solution can spiral into long-term financial hardship. Without careful planning, families may struggle for years to pay down the debt.

9. Impact on Retirement Savings

To cover costs, some families dip into retirement accounts or stop making contributions altogether. This creates one of the longest-lasting financial shocks, since it reduces future security. Early withdrawals often come with penalties and taxes, further shrinking the amount available. Missing years of contributions also means missing years of growth. The impact can derail retirement plans for decades.

10. Legal and Administrative Expenses

Finally, financial shocks often appear in the form of legal and paperwork-related costs. Families may need to update wills, establish powers of attorney, or handle medical billing disputes. Hiring professionals to navigate these complexities adds unexpected expenses. Even small legal fees can feel overwhelming when paired with other financial shocks. These hidden costs remind families that illness affects every corner of life.

Preparing for the Unseen Costs of Illness

A major illness doesn’t just challenge health—it creates lasting financial shocks that can threaten long-term stability. While no one can predict every expense, awareness and preparation make a difference. Building emergency savings, reviewing insurance policies, and planning for caregiving needs help reduce the impact. Families who plan ahead recover financially faster and with less stress. Protecting both health and wealth is essential to moving forward after hardship.

Have you or someone you know faced unexpected financial shocks after a major illness? What strategies helped you manage them? Share your experiences in the comments.

What to Read Next…

  • 5 Overlooked Costs of Long-Term Care That Shock Families
  • Why Do High Earners Still Struggle With Emergency Savings
  • 8 Hidden Costs of Raising Children That Are Rarely Discussed
  • Could Pet Ownership Now Be More Expensive Than Raising Kids
  • 8 Unexpected Costs That Come With Aging Parents
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Health & Wellness Tagged With: Credit card debt, family finances, financial shocks, healthcare planning, major illness costs, medical expenses, retirement savings

Could Wealth Actually Shorten Your Life Expectancy

September 12, 2025 by Catherine Reed Leave a Comment

Could Wealth Actually Shorten Your Life Expectancy
Image source: 123rf.com

Money is often viewed as the key to a longer, healthier life, offering better access to healthcare, safer neighborhoods, and less financial stress. But surprisingly, having wealth can sometimes create circumstances that actually shorten your life expectancy. From the pressures of maintaining financial success to the lifestyle risks that come with abundance, money isn’t always the blessing it appears to be. In fact, for some people, wealth introduces challenges that quietly chip away at their health and longevity. Here are several surprising ways money could work against your well-being.

1. Stress from High-Pressure Lifestyles

Wealth often comes with demanding careers and the stress of maintaining status. High achievers may face long hours, intense deadlines, and the constant pressure to outperform peers. Chronic stress is well known to shorten your life expectancy by increasing risks of heart disease, high blood pressure, and other serious conditions. Even when financial problems aren’t the issue, the demands of wealth creation can wear down the body. The very pursuit of success may undermine health in the long run.

2. Risky Habits Fueled by Excess

Having money opens the door to indulgence, and sometimes those indulgences turn into risky habits. From excessive drinking to recreational drug use, wealthy individuals may face temptations that chip away at their health. Over time, these behaviors can shorten your life expectancy by contributing to addiction, organ damage, or accidents. Even luxury dining can become problematic when it leads to overeating or unhealthy diets. The freedom that comes with wealth often carries hidden risks.

3. Lack of Physical Activity

Modern wealth provides comfort, but sometimes comfort leads to inactivity. Wealthy individuals may rely heavily on cars, assistants, or technology to do tasks for them. Over time, this lack of movement can shorten your life expectancy by increasing risks of obesity, diabetes, and cardiovascular disease. Gyms and personal trainers may be available, but not everyone makes full use of them. Convenience can quietly become a health liability.

4. Social Isolation and Loneliness

Surprisingly, wealth can create distance from others rather than connection. Some wealthy people struggle to form genuine relationships, unsure if others are interested in them or their money. This isolation contributes to loneliness, which research shows can shorten your life expectancy as much as smoking or obesity. Without strong social support, health declines more rapidly with age. In this way, wealth can sometimes act as a barrier to meaningful human connection.

5. Workaholism That Disrupts Balance

Another way wealth may shorten your life expectancy is through the culture of overwork. Many high earners push themselves relentlessly, often sacrificing sleep, exercise, and downtime in the process. While this drive can generate financial success, it also undermines physical and mental health. The body and mind need recovery time, and ignoring those needs leads to burnout. When wealth depends on constant effort, longevity often suffers.

6. Increased Risk-Taking Behavior

Having significant financial resources often gives people a sense of invincibility. Wealthy individuals may engage in high-risk activities like extreme sports, reckless driving, or speculative investments that carry personal consequences. While these risks provide thrills, they also have the potential to shorten your life expectancy if something goes wrong. The ability to afford recovery doesn’t eliminate the danger of serious injury or fatal accidents. Sometimes financial security breeds unnecessary recklessness.

7. Pressure to Maintain Appearances

Wealth comes with social expectations that can weigh heavily on individuals. The pressure to maintain appearances—whether through luxury homes, cars, or endless commitments—creates ongoing stress. Over time, this stress contributes to mental and physical health decline. Trying to “keep up” in wealthy circles may not sound like a health risk, but it can shorten your life expectancy by amplifying anxiety and tension. The cost of appearances isn’t always financial—it can also be measured in years of life lost.

8. Inherited Health Risks Through Generations

Sometimes wealth allows unhealthy patterns to pass from one generation to the next. Children raised in wealthy households may adopt the same indulgences, sedentary habits, or reliance on convenience as their parents. These patterns can lead to health risks that shorten your life expectancy later in life. Financial resources can provide better opportunities, but without guidance, they may encourage unhealthy behaviors. Money alone doesn’t guarantee healthier outcomes for future generations.

Wealth Should Work for Your Health, Not Against It

Wealth may offer comfort, opportunity, and security, but without balance, it can also shorten your life expectancy in surprising ways. Stress, isolation, risky habits, and overwork all contribute to health decline, no matter how much money is in the bank. The key is learning to use financial resources to build healthier lifestyles rather than letting them feed unhealthy ones. By prioritizing balance, connection, and well-being, wealth can truly support longevity instead of undermining it.

Do you believe wealth makes it harder or easier to live a longer life? Share your thoughts in the comments below.

What to Read Next…

Could Hidden Medical Fees Be the Biggest Threat to Savings

7 Money Mistakes That Quietly Break Middle-Class Budgets

10 Financial Risks of Starting a Side Hustle Too Quickly

6 Unexpected Fees That Sneak Into Hospital Bills

10 Tactics for Building an Emergency Fund from Scratch

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Health & Wellness Tagged With: financial stress, health and money, lifestyle choices, longevity risks, Personal Finance, shorten your life expectancy, wealth and health

Could Hidden Medical Fees Be the Biggest Threat to Savings

September 9, 2025 by Travis Campbell Leave a Comment

medical money
Image source: pexels.com

When you’re planning your finances, you probably think about rent, groceries, retirement, and maybe even a vacation fund. But there’s a sneaky danger that can quietly drain your accounts: hidden medical fees. These unexpected charges can hit anyone, regardless of how carefully they budget. Medical bills can be confusing, full of surprise costs, and often arrive long after you’ve received care. For many families, these fees are not just frustrating—they can threaten long-term savings goals.

It’s easy to assume your insurance will cover most expenses, but that’s not always the case. Even a simple visit to the doctor can result in bills you didn’t anticipate. If you’re not prepared, hidden medical fees can unravel years of careful saving. Let’s break down where these fees come from, how they catch people off guard, and what you can do to protect your savings.

1. Out-of-Network Surprises

One of the most common sources of hidden medical fees is out-of-network providers. You might visit a hospital that’s in your insurance network but later get a bill from an anesthesiologist or lab that isn’t. These out-of-network charges can be hundreds or even thousands of dollars, and they often aren’t obvious until the bill arrives.

Even if you ask about coverage ahead of time, it’s not always clear if every provider involved in your care is covered. This makes medical expenses unpredictable and can seriously impact your savings. Understanding your plan and asking for a list of all providers involved before a procedure can help, but it’s not a guarantee.

2. Unclear Pricing and Billing Codes

Hospitals and clinics often use complex billing codes that make it hard to know what you’re really being charged for. You might receive a bill for a procedure you thought was routine, only to find out that a specific code triggered a higher fee. Sometimes, a simple blood test or scan can carry additional “facility fees” you didn’t expect.

Because pricing isn’t always transparent, it’s easy to get caught off guard. These hidden medical fees can add up quickly, especially if you have a chronic condition or need follow-up care. Always request an itemized bill and review each charge. If something looks off, call the billing department to ask for clarification or corrections.

3. High Deductibles and Copays

Many insurance plans now come with high deductibles and larger copays. This means you pay more out of pocket before your insurance even kicks in. If you’re healthy, you might not notice this cost right away. But one unexpected emergency or surgery can leave you with a hefty bill.

These hidden medical fees often sneak up on people who assume their premiums are buying peace of mind. In reality, you might be responsible for thousands of dollars before your coverage starts. Planning for these potential expenses is key to protecting your savings from sudden medical costs.

4. Prescription Drug Costs

Prescription medications are a major source of hidden medical fees. Even if you have insurance, not all drugs are covered at the same rate. Some medications require a higher copay or aren’t covered at all, leaving you with a big surprise at the pharmacy counter.

Pharmacies sometimes substitute a brand-name drug for a generic, or vice versa, affecting your final cost. Always ask if there’s a cheaper alternative and check with your insurer to see what’s covered. Shopping around at different pharmacies can also reveal significant price differences for the same medication.

5. Emergency Room Visits

The emergency room is notorious for high and unpredictable bills. In a crisis, you don’t have time to check which hospitals are in-network. After treatment, you might get multiple bills from different doctors and departments—many of which could be out-of-network.

Hidden medical fees from emergency care can devastate your savings, especially if you don’t have a financial cushion. Some states have passed laws to limit surprise billing, but gaps remain. If you’re billed unexpectedly, ask about financial assistance programs or payment plans. Don’t ignore these bills—they can go to collections and hurt your credit.

6. Preventive Care Confusion

Many insurance plans advertise “free” preventive care, but there are often catches. For example, a routine screening might be covered, but if your doctor finds something and runs additional tests, those might not be. Suddenly, your free checkup comes with a bill attached.

This fine print can lead to hidden medical fees that chip away at your savings. Always clarify what’s included in preventive services before your appointment. If you’re unsure, call your insurance company for details.

Taking Control of Hidden Medical Fees

Hidden medical fees can quietly undermine even the best savings plan. They’re rarely obvious, often confusing, and can arrive when you least expect them. The good news is, you have options. Start by understanding your insurance plan in detail and keeping records of all medical visits and bills. Don’t hesitate to negotiate charges or ask for payment plans if needed.

Consider building a dedicated health savings fund or looking into a Health Savings Account (HSA) if you qualify. These accounts offer tax benefits and can help buffer the impact of unexpected medical costs. Ultimately, staying proactive and informed is your best defense against hidden medical fees eating away at your savings.

Have you ever been hit with unexpected medical charges? How did you handle it? Share your experience or tips in the comments below!

What to Read Next…

  • Can An Unpaid Medical Bill Really Lead To Property Seizure?
  • What Happens When A Medical Emergency Outpaces Your Emergency Fund?
  • 7 Financial Assumptions That Collapse After One Health Emergency
  • 7 Hidden Fees That Aren’t Labeled As Fees At All
  • Are Retirement Homes Quietly Charging Hidden Admission Fees?
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Health & Wellness Tagged With: health insurance, Hidden Fees, medical bills, Personal Finance, savings, unexpected expenses

5 Overlooked Costs of Long-Term Care That Shock Families

September 5, 2025 by Travis Campbell Leave a Comment

overlooked costs of long-term care
Image Source: 123rf.com

Planning for long-term care is something most families hope to put off as long as possible. Yet, when the need arises, the financial reality can hit hard. Many people focus on the obvious expenses—like nursing home fees or in-home caregivers. But the true cost of long-term care goes far beyond these visible charges. It’s the overlooked costs of long-term care that often catch families off guard, straining budgets and creating stressful decisions.

These hidden expenses can quickly add up, even for those who thought they were prepared. Insurance may not cover everything, and government programs often have strict limitations. Understanding what to expect can help families make more informed choices. Here are five overlooked costs of long-term care that shock families, and what you can do to avoid surprises.

1. Home Modifications and Accessibility

One of the most common overlooked costs of long-term care is the need to adapt a home for safety and accessibility. Most homes aren’t designed for wheelchairs, walkers, or people with limited mobility. Families often face expenses for ramps, stairlifts, grab bars, widened doorways, and bathroom modifications. Even seemingly minor changes, like non-slip flooring or better lighting, can add up to thousands of dollars.

These changes aren’t just about comfort—they’re about safety and independence. Yet, Medicare and many private insurance policies rarely cover these upgrades. That means families must pay out of pocket, often on short notice, when a loved one’s condition suddenly changes.

2. Unpaid Family Caregiver Costs

Another hidden cost comes from family members who step in to provide care. While this may seem like a way to save money, the reality is more complicated. Relatives often reduce work hours or quit jobs entirely to care for a loved one. This leads to lost wages, reduced retirement contributions, and even lost health insurance.

There’s also the emotional toll and potential out-of-pocket expenses—like transportation, meals, or supplies. The financial impact of unpaid caregiving is significant, yet it’s easy to underestimate. Families can benefit from researching support programs, such as resources for caregivers, to ease the burden.

3. Transportation and Travel Expenses

Getting to and from medical appointments, therapy sessions, and social activities can be a logistical and financial challenge. Long-term care often involves frequent trips to doctors, specialists, or day programs. If the person receiving care cannot drive, families may need to arrange for taxis, ride-sharing, or specialized medical transport.

These costs are rarely covered by insurance, especially if the trips are not considered medically necessary. In rural areas, the problem can be worse, with longer distances and fewer options. The overlooked costs of long-term care related to transportation can quietly drain savings over time.

4. Non-Covered Medical Supplies and Services

Many families are surprised by the number of medical supplies and services not covered by insurance. Adult diapers, wound care supplies, special nutritional shakes, and certain medications can all become recurring expenses. Over-the-counter products, like creams or adaptive utensils, add to the tally.

In addition, some therapies—like massage, dental care, or vision services—are often excluded from coverage. These non-covered costs can total hundreds of dollars each month. Planning ahead and checking what’s actually included in your insurance can help avoid sticker shock.

5. Legal and Financial Planning Fees

Long-term care often brings a wave of paperwork: power of attorney documents, living wills, estate plans, and Medicaid eligibility applications. Hiring professionals, such as elder law attorneys or financial planners, is common and sometimes necessary. Their expertise protects assets and ensures the person’s wishes are honored.

However, these services come at a price—hourly fees, flat rates, or retainer agreements. For families already stretched by care costs, these legal and financial planning fees can feel like a surprise punch to the budget. Still, skipping them can lead to bigger problems later, including missed benefits or legal disputes.

How to Prepare for the Overlooked Costs of Long-Term Care

Facing the overlooked costs of long-term care may feel daunting, but there are ways to prepare. Start by having honest conversations with family members about expectations and potential needs. Research what your insurance actually covers, and don’t assume government programs will fill in every gap. Consider creating a dedicated savings fund for unexpected care expenses.

It’s also wise to consult with professionals early, before a crisis hits. An elder law attorney or a trusted financial advisor can help you navigate the maze of options and avoid costly mistakes. By planning ahead, you can reduce the financial shock and focus on what matters most—caring for your loved one.

Have you encountered any hidden or surprising costs of long-term care in your own family? Share your experience in the comments below.

What to Read Next…

  • Why Your Long Term Care Policy Might Be Useless After Age 75
  • 5 Financial Habits That Quietly Void Long Term Care Policies
  • Are Retirement Homes Quietly Charging Hidden Admission Fees?
  • 10 Services Adult Children Regret Paying For Their Parents
  • Why Some Elder Care Homes Are Requiring Adult Children To Cosign
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Health & Wellness Tagged With: caregiving, elder care, family finances, Long-term care, retirement planning, unexpected expenses

How Can Medical Bills Wipe Out Savings Faster Than a Market Crash

August 30, 2025 by Travis Campbell Leave a Comment

medical bills
Image source: pexels.com

When people think about major threats to their savings, a market crash is often the first thing that comes to mind. But for many Americans, medical bills can wipe out savings even faster and more unexpectedly. Health emergencies rarely come with warnings, and the resulting expenses can be overwhelming. Unlike market downturns, which may recover over time, medical debt can be immediate, relentless, and deeply personal. Understanding why medical bills pose such a significant financial risk is crucial for anyone who wants to protect their hard-earned savings. Let’s break down the main reasons why medical bills can wipe out savings faster than a market crash.

1. The Sheer Size and Unpredictability of Medical Expenses

Medical bills can be shockingly high, especially for emergencies or serious illnesses. Even with insurance, out-of-pocket costs can soar into the tens or hundreds of thousands of dollars. A sudden diagnosis or accident doesn’t offer the chance to plan or save in advance. Unlike a market crash, which typically unfolds over weeks or months, medical expenses can hit all at once. This unpredictability makes it nearly impossible to prepare adequately, and savings can disappear overnight.

This reality highlights why the keyword “medical bills” is so important: they don’t just threaten your financial stability—they can drain your entire safety net before you have a chance to react.

2. Insurance Doesn’t Always Protect You

Many assume that having health insurance means they’re safe from financial harm. Unfortunately, that’s not always true. High deductibles, copays, coinsurance, and uncovered treatments can add up quickly. Some policies have strict limits or narrow provider networks, leaving patients responsible for a large share of the costs.

Even for common procedures, surprise medical bills can occur when a provider is out-of-network, even if the hospital is in-network. This leaves many families facing bills they never expected. In contrast, during a market crash, your investments may lose value, but you don’t typically owe more money out of pocket.

3. Immediate Payment Demands and Aggressive Collections

Hospitals and medical providers often expect prompt payment. If you can’t pay right away, unpaid medical bills are quickly sent to collections. Aggressive collection tactics can add stress and financial strain, sometimes leading to wage garnishment or legal action.

Unlike financial losses in the stock market, where you may have time to recover, medical debt can become a crisis almost immediately. The speed at which these bills move to collections makes it hard to negotiate or come up with alternative solutions before your savings are depleted.

4. Loss of Income Compounds the Problem

Serious illness or injury doesn’t just bring large medical bills—it can also mean time away from work. If you’re unable to earn income while recovering, you’re forced to rely on your savings for both living expenses and medical costs. This double hit can empty even a well-prepared emergency fund in a matter of months.

Market crashes are stressful, but unless you sell investments at a loss, you still hold the assets. With medical bills, the cash leaves your account, and your ability to replenish it is often compromised at the worst possible time.

5. Interest and Fees Accelerate Debt Growth

Once medical bills are turned over to collections, interest, late fees, and penalties can begin to pile up. This makes the original debt grow much faster, increasing the financial burden. Even small bills can grow into large debts if not addressed quickly.

Market crashes can erode the value of your investments, but they don’t create additional debt. Medical bills, on the other hand, can snowball into an unmanageable financial problem if not resolved promptly.

6. Limited Legal Protections Compared to Investment Losses

There are more safeguards in place to protect investors from catastrophic loss than there are for people facing medical debt. For example, the FDIC protects bank deposits, and there are regulations aimed at reducing market manipulation. But with medical bills, there are few protections. Bankruptcy is often the last resort, and it comes with long-term consequences for your credit and financial future.

This lack of a safety net means that medical bills can wipe out savings with little warning or opportunity for recourse. It’s a risk that’s all too real for millions of Americans.

What You Can Do to Protect Yourself

Understanding how medical bills can wipe out savings faster than a market crash is the first step toward protecting yourself. Start by reviewing your health insurance carefully—know your deductible, out-of-pocket maximum, and what’s covered. Build an emergency fund that accounts for potential medical expenses, not just routine emergencies. Consider supplemental insurance or health savings accounts if they fit your situation.

If you receive a large bill, don’t ignore it. Negotiate with providers, ask for financial assistance, or set up a payment plan.

Medical bills are a unique threat to financial security. By planning ahead and acting quickly when faced with large expenses, you can reduce the risk of having your savings wiped out by unexpected health costs. Have you ever faced a medical bill that threatened your savings? Share your story or tips in the comments below.

What to Read Next…

  • Can an Unpaid Medical Bill Really Lead to Property Seizure?
  • What Happens When a Medical Emergency Outpaces Your Emergency Fund?
  • 5 Emergency Repairs That Could Force You Into Debt Overnight
  • 7 Financial Assumptions That Collapse After One Health Emergency
  • 7 Costs Retirees Refuse to Pay in 2025 and How You Can Follow Their Lead
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Health & Wellness Tagged With: debt collection, emergency fund, health insurance, market crash, medical bills, Personal Finance, savings

Advance Care Directives: Top Q&A Queries from Google Trends

August 23, 2025 by Catherine Reed Leave a Comment

Advance Care Directives: Top Q&A Queries from Google Trends
Image source: 123rf.com

When it comes to healthcare planning, many people avoid tough conversations until it’s too late. Yet, advance care directives give families clarity, reduce stress, and ensure a person’s wishes are followed during medical emergencies. With more people searching online for answers, Google Trends reveals common questions families ask about these important documents. Whether you’re caring for aging parents, planning for your own future, or simply curious, understanding the basics can make all the difference. Here are the top Q&A queries about advance care directives and what you should know before creating one.

1. What Is an Advance Care Directive?

One of the most common questions people search for is simply what an advance care directive is. In short, it’s a legal document that outlines your preferences for medical care if you cannot speak for yourself. These directives often include choices about life support, resuscitation, and comfort measures. By documenting your wishes, you relieve your loved ones from making difficult decisions under pressure. This makes advance care directives a vital tool for protecting both your health and your family’s peace of mind.

2. How Is an Advance Care Directive Different from a Living Will?

Google data shows many people confuse advance care directives with living wills. While related, they are not identical. A living will focuses specifically on your preferences for end-of-life care, while advance care directives cover a broader range of medical decisions. In addition to outlining treatment choices, they can also designate a healthcare proxy to make decisions on your behalf. Knowing this distinction helps families better prepare for different medical situations.

3. Who Can Create an Advance Care Directive?

Another popular query is whether advance care directives are only for the elderly or terminally ill. The truth is, any adult can and should create one. Life is unpredictable, and medical crises can happen at any age. By completing a directive early, you ensure your preferences are clear, no matter what the future holds. This proactive step brings peace of mind for both you and your loved ones.

4. Do Advance Care Directives Vary by State?

People also want to know if advance care directives look the same across the country. The answer is no—laws and forms vary from state to state. Each state may have its own requirements for witnesses, notarization, or the exact language used. That’s why it’s important to complete a directive based on your state of residence. Fortunately, most state-specific forms are available online and are easy to access.

5. Can You Change an Advance Care Directive?

One of the top searches highlights concern about making the wrong decision. The good news is that advance care directives can be updated at any time as long as you are mentally capable. People often revise them after major life events like marriage, divorce, or a new diagnosis. Making changes is as simple as completing a new directive and ensuring healthcare providers and family members have copies. This flexibility helps you stay in control as circumstances evolve.

6. Does an Advance Care Directive Include Financial Decisions?

A common misconception is that advance care directives cover both medical and financial matters. In reality, they only apply to healthcare decisions. For financial management, you would need a durable power of attorney or similar legal document. Advance care directives strictly guide doctors and healthcare providers on treatment options. Knowing this helps families avoid confusion and ensures all aspects of planning are properly covered.

7. Who Should Have a Copy of Your Directive?

One of the most practical questions people ask is where to keep the completed document. Advance care directives should be shared with your primary care doctor, local hospital, and close family members. Some people also give copies to trusted friends or upload them to online medical records. Keeping it hidden in a drawer at home won’t help in an emergency. Making sure it’s accessible ensures your wishes are honored when it matters most.

8. Are Advance Care Directives the Same as DNR Orders?

Many searchers confuse advance care directives with “Do Not Resuscitate” (DNR) orders. While they overlap, they are not identical. A DNR specifically tells doctors not to perform CPR if your heart stops, while advance care directives provide broader instructions on multiple treatments. You can include a DNR request within a directive, but they remain separate documents. Understanding this difference ensures your preferences are fully respected.

9. Do You Need a Lawyer to Complete an Advance Care Directive?

Finally, people often ask if legal help is required to set up a directive. The truth is, most advance care directives do not require an attorney and can be completed using free state-provided forms. That said, some families choose to consult a lawyer if their situation is complex. At the very least, reviewing the document with a healthcare provider is a good idea. The process is simpler and less intimidating than many assume.

Why Everyone Should Ask These Questions Now

Advance care directives are not just for the elderly—they are a smart, responsible step for anyone who wants to take control of their medical care. By addressing these common questions, you can avoid confusion, reduce family stress, and make sure your wishes are followed. The laws and forms may vary by state, but the benefits of preparation remain the same everywhere. Taking action now means peace of mind for you and clarity for your loved ones. In the end, advance planning is one of the greatest gifts you can give your family.

Have you completed your own advance care directive, or are you still considering it? Share your experiences and questions in the comments below.

Read More:

Are Your Medical Wishes Legally Enforceable Across State Lines?

Retirees Face $172,500 in Healthcare Costs—And Many Haven’t Saved for It

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.
Filed Under: Health & Wellness Tagged With: advance care directives, end-of-life planning, Estate planning, family preparation, healthcare planning, living will, medical decisions

  • « Previous Page
  • 1
  • …
  • 3
  • 4
  • 5
  • 6
  • 7
  • …
  • 9
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework