• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for investing news

The Definition of Irony (or Why You Should Know What You’re Doing)

October 13, 2011 by The Other Guy 2 Comments

I know sometimes I might sound a little cranky (like yesterday, for example).  But here’s a good reason why….I can’t make this stuff up.

Some back story:

As an advisor, one of the most common requests I’d receive was to help someone choose which funds to pick inside their workplace retirement plan.

Most companies have one – either a 401(k), 403(b), SEP, SIMPLE, or something…  Each of these plans was sold to the company owner by a salesperson financial advisor.

Who picks which funds are appropriate to include in the account?  Who makes the (hopefully) long list of choices you and I can oogle while we decide which is best for your retirement?  The owner chooses, but she is handed a list by the  salesperson financial advisor.  99 percent of the time, the owner doesn’t hav the time or inclination to second guess the choices, so they accept the “professional” recommendation.  If you work for a large corporation…then who picks the funds?  A committee…combined with the salesperson financial advisor.

What happens when your 401(k) fund choices just plain suck?  Do you have any repercussions? 

Apparently, you do.  And this is where our story begins……

At Ameriprise Financial, (they’re a middle-of-the-road financial “planning” firm) employees are eligible for their own 401(k) plan.  One of the nice bonuses for those working in the industry, is that you may happen to have an in-house mutual fund department.  Ameriprise does.  Awesome!  And, you may have your very own retirement plan operation.  Ameriprise does.  Cool beans! 

When you sell funds for a living, you would suspect there’d be awesome choices in your plan…right?  You’d skip to work every day, whistling with joy and pinching yourself that you work for the company that knows how to deliver the bacon when it comes to retirement plans.  It’s kind of like owning the golden goose.

But it isn’t.

According to Nathan Hale at CBS MoneyWatch, Ameriprise funds inside of the Ameriprise 401(k) suck SO BAD that employees are SUING the company to get out.

Wait.  Did I read that correctly?

Financial advisors are suing their own company for forcing them to eat their own cooking?  HA HA HA HA.

That, folks, is the definition of irony.

It may also be why Joe’s had a case of the crankies.

This is specifically why planning your own future is non-negotiable.  If you want to achieve your goal, know what you’re doing yourself.  It’s okay if you need to hire an advisor, but don’t just hand them the keys to your car, jump in the back and expect to reach the place you want to go! 

Do your own homework.  In this case, the stuff that’s peddled by these salespersons financial advisors is so atrocious, they wouldn’t own it themselves (the cynical part of me thinks they might still sell it to their mother, though, if there’s a bonus in it).

Don’t let a salesperson tell you to “stay the course, Mr. Smith.  It’ll be OK”  if it clearly isn’t the case. Over the next several weeks, I’m going to show you some of the cool tools you can use for FREE on the internet to do your own homework. Even if you have an advisor, you should know how to double-check her work. 

That should be exciting, huh?  For now, I’m going to keep giggling to myself about this story.
Filed Under: investing news, Planning Tagged With: 401k plans, 403b plans, Ameriprise, Ameriprise employees sue, irony, who knew?

Federal Reserve Report: Hang On For Rough Ride…

September 26, 2011 by The Other Guy 1 Comment

Here’s a depressing recent headline. Today the Federal Reserve Bank of San Francisco released a report predicting that the financial markets are unlikely to be strong for the next…drum roll please…16 years!

Can this be accurate?

The report, titled “Boomer Retirement: Headwind for U.S. Equity Markets?” illustrates long-range, historical data which suggests that as the boomer generation moves into retirement, they’ll pull an increasing amount of money out of equity funds.  This can only mean increased pressure on stocks for years to come.

This is classic ‘supply & demand’ economics at work here, folks. 

Roughly 10,000 baby-boomers turn 60 EVERY DAY, a trend that will continue for the foreseeable future.  As each of these 10,000 individuals leaves the workforce, they need money to spend in retirement.  Where will their meals come from?  That’s right.  Their spending money will come, in part, from investment portfolios.

As the report points out “…to finance retirement, they are likely to sell off acquired assets, especially risky assets.  A looming concern is that this massive sell-off might depress equity values.”

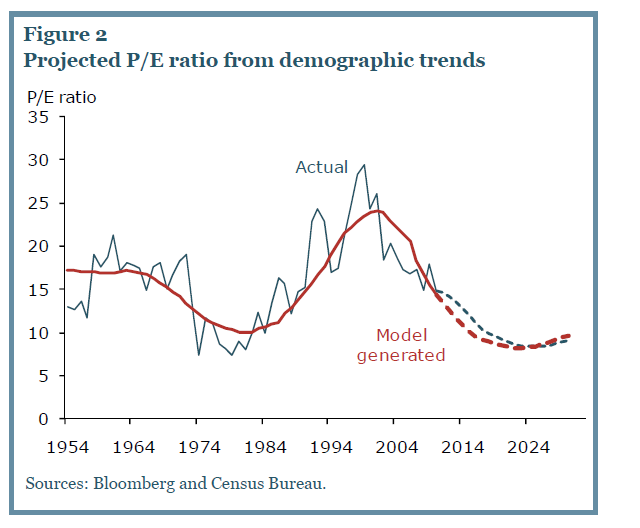
Take a look at this projection:

Chart of projected P/E ratio from demographic trends, actual vs. model generated, 1954 on. Source: Bloomberg, Census Bureau According to the research in this report, P/E ratios, an indicator of potential stock prices, is slated to continue downward through the early 2020s before rebounding in the latter half of that decade.

“Figure 2 shows that P/E should decline persistently from about 15 in 2010 to about 8.4 in 2025, before recovering to 9.14 in 2030.”

The report continues: “The model-generated path for real stock prices implied by demographic trends is quite bearish.  Real stock prices follow a downward trend until 2021, cumulatively declining 13% relative to 2010…real stock prices are not expected to return to their 2010 levels until 2027.”

Ouch.  That could sting a little.

So what does this data imply?

Should we all be in bonds until 2030?  Quite the contrary.  There will likely still be bullish trends throughout the upcoming cycle, so it pays to be vigilant. 

Instead, I believe this heralds the end of “buy and hold and you’ll be fine” investing.

This mean you’ll need to be cognizant of market trends and invest accordingly.  What does your advisor think about this report?  In all likelihood, he’s never heard of it, and will probably say something like “Just invest and stick with the plan, and you’ll be OK.”

You can do better.  If you just pay attention to the signs, you can profit from both sides of the market, both the ups and downs.  You just have to pay attention.

If you’d like to read this report for yourself, it’s available here or type in http://www.frbsf.org/publications/economics/letter/2011/el2011-26.html to read for yourself.

I’m interested in your thoughts…post your comments below.

Filed Under: investing news, successful investing Tagged With: federal reserve, investing, investing news, market report, San Francisco reserve, stock market, stocks, trends

  • « Previous Page
  • 1
  • 2
  • 3

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework