• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Finance

8 Circumstances Where You Really Need Financial Advice and Where to Find It

April 7, 2025 by Travis Campbell Leave a Comment

money on table
Image Source: unsplash.com

Navigating your financial journey alone can sometimes feel like sailing through stormy waters without a compass. While many financial decisions can be handled independently, certain life events and financial complexities demand professional guidance. Recognizing when you need expert financial advice is crucial for protecting your wealth and securing your future. This article explores eight specific situations where seeking professional financial advice isn’t just helpful—it’s essential.

1. Major Life Transitions Require Financial Recalibration

Life transitions often trigger the need for comprehensive financial planning. Marriage, divorce, or the birth of a child fundamentally changes your financial responsibilities and goals. The death of a spouse can leave you navigating complex financial decisions while grieving. Career changes, especially those involving significant salary adjustments or relocation, necessitate a fresh look at your financial strategy. A financial advisor can help you adjust your financial plan during these transitions, ensuring your new life chapter starts on solid financial footing.

2. Inheritance Management Demands Strategic Planning

Receiving an inheritance often comes with emotional and financial complexities that require professional guidance. The sudden influx of assets may include investments, property, or retirement accounts that each carry different tax implications and management requirements. Poor inheritance management decisions can lead to unnecessary tax burdens or missed growth opportunities that diminish the inheritance’s value. A financial advisor can help you integrate inherited assets into your existing financial plan while respecting any wishes the benefactor may have had. Professional guidance ensures you honor the gift by managing it responsibly while maximizing its potential to support your financial goals.

3. Retirement Planning Becomes Increasingly Complex

Retirement planning involves more than simply saving money—it requires strategic decision-making about investment allocations, withdrawal rates, and timing. As retirement approaches, mistakes become costlier with less time to recover from market downturns or planning errors. Questions about Social Security optimization, pension options, and healthcare planning require specialized knowledge that most individuals don’t possess. A financial advisor can create a comprehensive retirement income strategy that addresses longevity risk, inflation, and market volatility. Professional guidance becomes particularly valuable when transitioning from the accumulation phase to the distribution phase of retirement planning.

4. Tax Optimization Requires Specialized Knowledge

Tax laws change frequently and contain numerous complexities that can significantly impact your financial situation. High-income earners, business owners, and those with diverse investment portfolios face particularly complicated tax scenarios. Strategic tax planning can legally reduce your tax burden through techniques like tax-loss harvesting, charitable giving strategies, and retirement account optimization. A financial advisor with tax expertise can coordinate with your accountant to implement tax-efficient investment strategies and withdrawal plans. Professional guidance ensures you’re not paying more in taxes than legally required while avoiding costly mistakes that could trigger IRS scrutiny.

5. Estate Planning Protects Your Legacy and Loved Ones

Estate planning goes beyond basic will creation to encompass comprehensive strategies for transferring wealth efficiently. Without proper planning, your assets may be distributed according to state laws rather than your wishes, potentially creating family conflicts. Estate taxes can significantly reduce the wealth transferred to your heirs without strategic planning techniques in place. A financial advisor can work with estate attorneys to create a cohesive plan that addresses wealth transfer, tax minimization, and charitable giving goals. Professional guidance ensures your estate plan remains updated as laws change and your family circumstances evolve over time.

6. Investment Management During Market Volatility

Market volatility tests even the most disciplined investors, often triggering emotional decisions that can damage long-term returns. Research consistently shows that individual investors underperform market indices largely due to behavioral biases and poor timing decisions. Complex investment vehicles like options, alternative investments, and tax-advantaged accounts require specialized knowledge to utilize effectively. A financial advisor provides an objective perspective during market turbulence, helping you stick to your long-term strategy rather than reacting to short-term fluctuations. Professional guidance becomes particularly valuable during major market corrections when emotional decision-making can lead to locking in losses.

7. Business Ownership Creates Unique Financial Challenges

Business owners face unique financial challenges that blur the line between personal and business finances. Succession planning, business valuation, and exit strategies require specialized expertise to execute effectively. Retirement planning becomes more complex for business owners who often have much of their net worth tied up in their business. A financial advisor with business expertise can help create strategies for business growth while ensuring personal financial security. Professional guidance can help business owners balance reinvesting in their business with diversifying their personal wealth to reduce concentration risk.

8. Special Needs Planning Requires Long-Term Vision

Families caring for individuals with special needs face unique financial planning challenges that extend far into the future. Government benefits for individuals with disabilities often have strict asset and income limitations that require careful financial structuring. Special needs trusts and ABLE accounts must be properly established and funded to provide for a loved one without jeopardizing their eligibility for benefits. A financial advisor with special needs expertise can coordinate with legal professionals to create a comprehensive care plan. Professional guidance ensures continuity of care and financial support even after parents or primary caregivers are no longer able to provide it.

Securing Your Financial Future: Taking the Next Step

Finding the right financial advisor requires understanding the different types of professionals and their compensation models. Fee-only fiduciary advisors offer conflict-free advice without commission incentives, while robo-advisors provide low-cost automated guidance for simpler situations. Professional designations like CFP® (Certified Financial Planner), CFA (Chartered Financial Analyst), or ChFC (Chartered Financial Consultant) indicate specialized training and ethical standards. Before committing, interview multiple advisors about their experience with situations similar to yours and their communication style. Remember that the best financial advice relationship is one built on trust, clear communication, and alignment with your specific needs and goals.

Have you faced any of these financial circumstances? What was your experience working with a financial advisor, or how did you handle the situation on your own? Share your insights in the comments below!

Read More

Help Me Help You: What Your Financial Advisor Wishes You’d Admit About Your Money Habits

Your Friend Makes More Money Than You—Now What? Dealing with Financial Jealousy

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Finance Tagged With: Estate planning, financial advice, financial advisor, Investment management, Planning, retirement planning, tax planning, Wealth management

Retirees Are Firing Their Financial Advisors—Here’s the Surprising Reason Why

April 7, 2025 by Travis Campbell Leave a Comment

retirees looking at the ocean
Image Source: unsplash.com

In an unexpected trend sweeping across retirement communities nationwide, financial advisors are being shown the door by their long-term clients. This shift isn’t happening because of poor investment returns or high fees—though those factors certainly play a role. The surprising catalyst behind this exodus reveals a fundamental change in how today’s retirees view their financial futures and what they expect from professional guidance. Understanding this phenomenon could save your retirement strategy from costly missteps and help you determine whether your current financial relationship is truly serving your needs.

1. The Trust Gap Is Widening Between Advisors and Retirees

The relationship between financial advisors and their retired clients has historically been built on a foundation of trust and expertise. Many retirees are discovering their advisors have been operating under outdated models that prioritize product sales over genuine financial planning. According to a recent survey by Vanguard, nearly 60% of retirees who switched advisors cited “lack of transparency” as their primary motivation. Technology has empowered retirees to verify information independently, making it easier to spot discrepancies between what they’re told and what research reveals. The generational shift toward self-education means today’s retirees are more financially literate than previous generations, enabling them to ask tougher questions. This knowledge gap closure has exposed situations where some advisors simply cannot justify their recommendations when pressed for evidence-based reasoning.

2. One-Size-Fits-All Retirement Strategies No Longer Satisfy

Modern retirees are rejecting cookie-cutter financial plans that fail to address their unique circumstances and goals. The traditional “4% withdrawal rule” and other standardized approaches are increasingly viewed as outdated oversimplifications that don’t account for longer lifespans and changing economic conditions. Personalization has become non-negotiable, with retirees expecting strategies tailored to their specific health situations, family dynamics, and lifestyle aspirations. Many advisors still rely heavily on age-based asset allocation formulas rather than developing truly customized approaches based on individual risk tolerance and objectives. Retirees are increasingly seeking advisors who demonstrate genuine curiosity about their lives and develop financial strategies that reflect their personal values, not just mathematical formulas.

3. Fee Structures Are Finally Coming Under Scrutiny

The veil has been lifted on the true cost of financial advice, prompting many retirees to question the value they receive relative to fees paid. Traditional percentage-based advisory fees that seemed reasonable during wealth accumulation phases can represent significant dollar amounts when applied to retirement portfolios. According to a study by NerdWallet, the average American pays between $502,407 and $936,390 in investment fees over their lifetime. Retirees are increasingly gravitating toward fee-only fiduciaries who eliminate conflicts of interest inherent in commission-based models. The rise of low-cost robo-advisors and digital platforms has established new benchmarks for what basic investment management should cost. This fee awareness has forced many retirees to ask the uncomfortable question: “What exactly am I paying for, and is it worth it?”

4. Communication Styles Are Creating Generational Disconnects

Today’s retirees expect advisors to communicate in ways that respect their intelligence and technological competence. Many advisors still rely on intimidating jargon and technical terminology that creates unnecessary barriers to understanding. Retirees report frustration with advisors who speak condescendingly or assume limited financial knowledge based solely on age. The frequency of communication has become another pain point, with many retirees expecting more regular updates than quarterly meetings or annual reviews. Digital natives entering retirement expect advisors to leverage technology for more efficient communication while still maintaining the personal touch that builds relationship trust.

5. Retirement Goals Have Evolved Beyond Simple Wealth Preservation

The definition of retirement success has fundamentally changed, leaving some advisors struggling to adapt their approaches. Modern retirees increasingly prioritize experiences over assets, seeking financial strategies that enable active lifestyles rather than merely preserving wealth. Environmental and social impact considerations have become important factors in investment decisions for many retirees, who want portfolios aligned with their values. Healthspan—not just lifespan—has emerged as a critical planning factor, with retirees seeking advisors who understand the financial implications of longevity and wellness. Many advisors remain fixated on traditional metrics like portfolio size rather than the more meaningful measure of how finances support quality of life. Retirees are seeking professionals who understand that money is merely a tool for living rather than an end goal in itself.

Finding True Financial Partnerships in Retirement

The exodus from traditional advisory relationships doesn’t mean retirees are abandoning professional guidance altogether—they’re simply becoming more discerning consumers. The most successful retirement planning relationships now resemble partnerships rather than the paternalistic models of the past. Advisors who thrive in this new landscape demonstrate genuine empathy, technological competence, and a willingness to collaborate rather than dictate. Transparency has become the cornerstone of trust, with successful advisors proactively disclosing all fees, potential conflicts of interest, and the reasoning behind recommendations. The future belongs to advisors who position themselves as retirement lifestyle designers rather than merely investment managers.

Have you noticed changes in your relationship with your financial advisor as you’ve approached or entered retirement? What qualities would make you reconsider your current financial guidance arrangement?

Read More

Best Free Financial Advice

In Defense of Financial Advisor Fees

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Finance Tagged With: fee transparency, fiduciary responsibility, financial advisors, modern retirement, retirement income, retirement planning

These 6 States Have The Highest Rates of Poverty

April 4, 2025 by Latrice Perez Leave a Comment

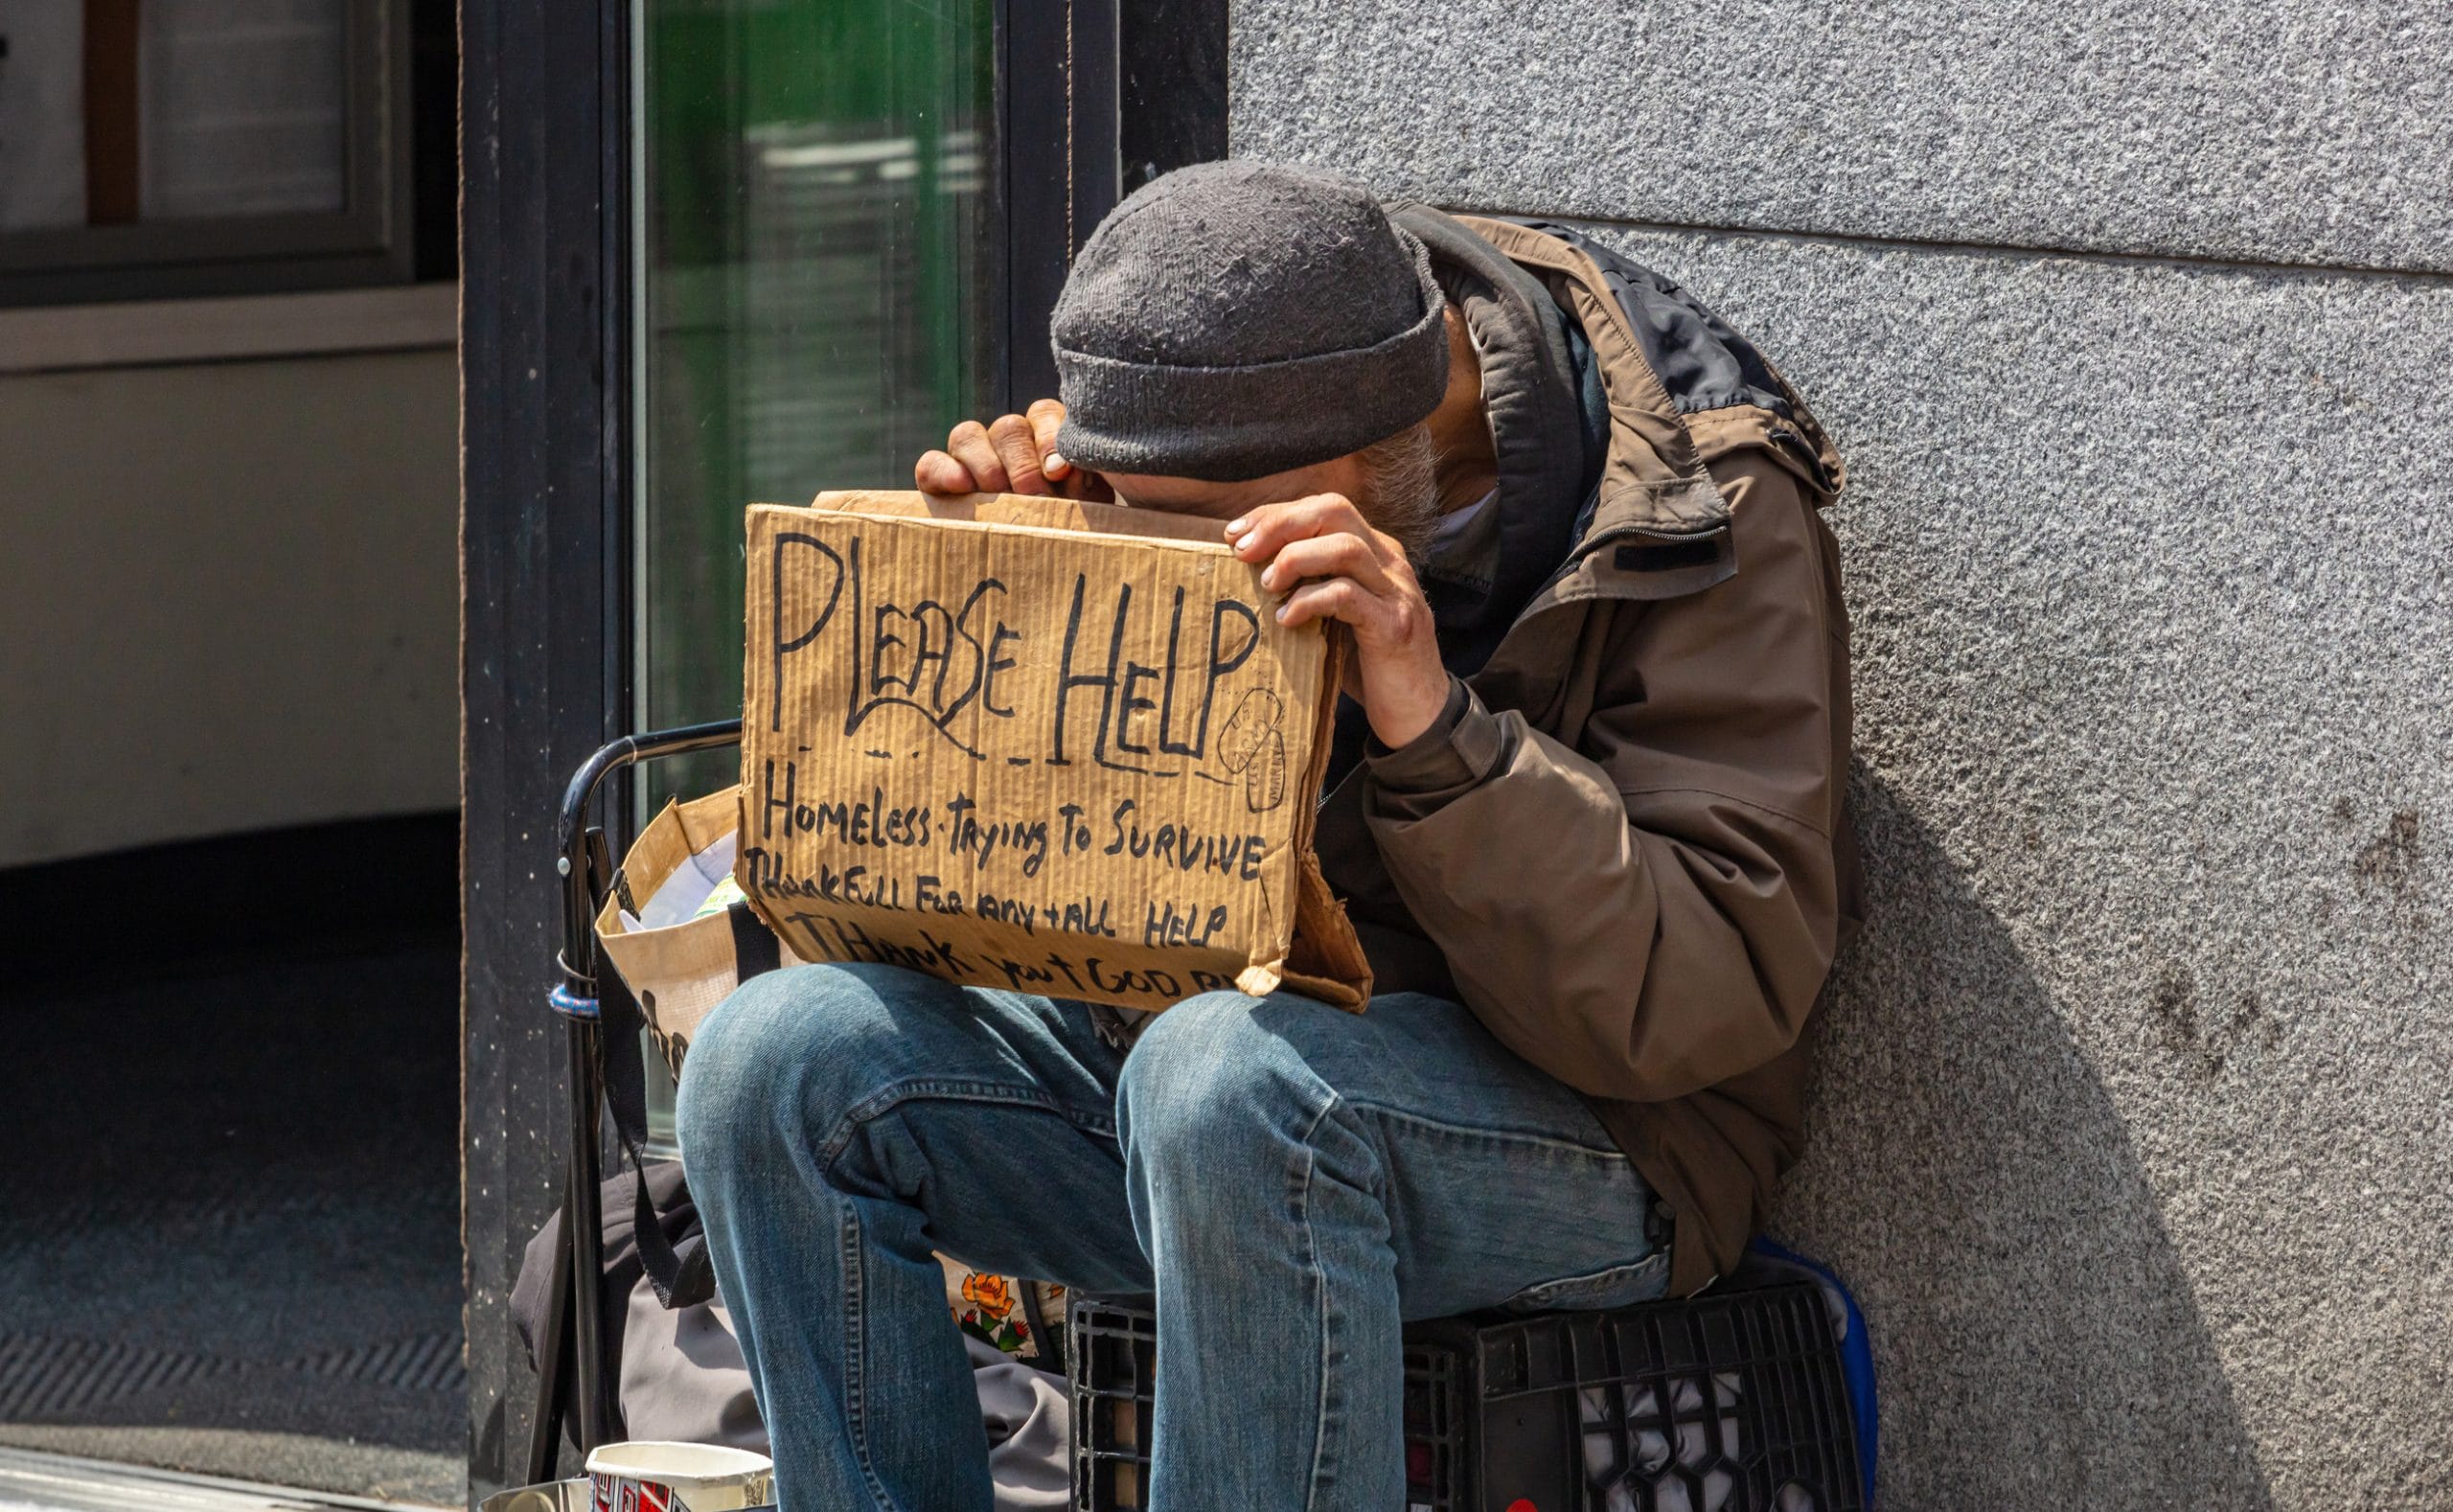
Homeless man holding a cardboard sign, asking for help, Manhattan downtown, sunny day in spring
Image Source: 123rf.com

Poverty remains a persistent challenge across the United States, affecting millions of individuals and families each year. While poverty rates vary significantly from state to state, certain regions face more pressing economic difficulties than others. Understanding these disparities is crucial for addressing systemic issues and developing solutions that uplift vulnerable communities. In this article, we’ll explore the six states with the highest poverty rates and what factors contribute to their struggles.

1. Mississippi

Mississippi consistently ranks as the state with the highest poverty rate in the U.S. The lack of diversified industries and limited access to quality education perpetuate economic hardships. Rural communities are particularly affected, with limited job opportunities compounding the issue. Many residents rely on agriculture and low-wage jobs that fail to provide long-term stability. Addressing these challenges requires a focus on education, job training, and infrastructure development.

2. Louisiana

Louisiana faces significant economic challenges due to natural disasters, limited access to healthcare, and an overreliance on low-paying industries. Hurricane damage over the years has disrupted communities and contributed to high unemployment rates. Additionally, many families struggle to afford basic needs, with rural areas experiencing the most severe impacts. Investing in disaster resilience and expanding economic opportunities could provide long-term relief. Addressing poverty in Louisiana also requires tackling systemic inequalities in healthcare and education.

3. New Mexico

New Mexico’s poverty rate is driven by a combination of high unemployment and limited access to educational resources. Many rural communities face infrastructure challenges, making it difficult for residents to access jobs or vocational training. A lack of well-paying industries further contributes to widespread economic struggles. Supporting initiatives that promote education and workforce development could help break the cycle of poverty. Community-driven programs have shown promise in addressing these systemic issues.

4. West Virginia

West Virginia
Image Source: 123rf.com

West Virginia has long struggled with poverty due to the decline of coal mining and limited economic diversification. Many residents have been unable to transition to new industries, leading to high unemployment rates. The state also faces challenges in healthcare access, which exacerbates economic difficulties for families. Supporting renewable energy initiatives and investing in education could help create sustainable job opportunities. Long-term change will require collaborative efforts from local and state leaders.

5. Arkansas

Arkansas is another state grappling with high poverty rates, particularly in rural regions where job opportunities are scarce. Limited access to higher education and healthcare services creates additional hurdles for families trying to escape poverty. Many households rely on government assistance to meet basic needs, but systemic improvements are needed to address root causes. Expanding access to affordable childcare and job training programs could provide a pathway to economic stability. Local leaders play a critical role in implementing change.

6. Kentucky

Kentucky’s poverty issues stem from high unemployment rates and limited access to education in rural areas. The state also faces challenges with substance abuse, which can contribute to economic instability for affected families. Revitalizing struggling communities requires a focus on healthcare, education, and economic development. Programs aimed at addressing addiction and supporting workforce readiness could help reduce poverty rates over time. A multi-faceted approach is key to creating meaningful change in Kentucky.

The Six States Aren’t The Only Places

While poverty affects these six states most acutely, it’s an issue that touches every corner of the United States. Addressing the root causes of poverty requires collaborative efforts from policymakers, community organizations, and individuals. By investing in education, healthcare, and economic development, we can create a more equitable future.

Which strategies do you believe are most effective for combating poverty? Share your thoughts and ideas in the comments below!

Read More:

12 Ways Your “Poverty Mentality” Is Hurting Your Financial Future

10 Myths About Poverty That Prevent Progress


Headshot of Latrice Perez
Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Finance Tagged With: economic challenges, poverty rates, rural poverty, state-by-state analysis, systemic inequality, U.S. poverty

9 States Where Social Security Benefits May Be at Risk

April 2, 2025 by Latrice Perez Leave a Comment

Concept of funding for social security drying up with loss of income to trust fund after market crash
Image Source: 123rf.com

Imagine relying on your Social Security benefits to cover essential expenses, only to discover that changes in your state’s policies might reduce the amount you receive. For many Americans, this scenario is becoming a concerning reality. While Social Security is a federal program, certain state-level actions and proposals can significantly influence the benefits you depend on. In this article, we’ll explore nine states where recent developments may impact your Social Security payments and what you can do to stay informed.

1. Texas

In Texas, over 32,000 residents who still receive Social Security payments via paper checks are affected by a federal mandate transitioning to electronic payments. This shift aims to reduce costs and prevent fraud but may disrupt the financial routines of many vulnerable recipients. Texans relying on paper checks must adapt to direct deposit or prepaid cards by September 30, 2025. ​

2. Colorado

Approximately 6,300 Coloradans are impacted by the same federal order ending paper Social Security checks. The transition to digital payments poses challenges, particularly for those without easy access to banking services or the internet. Beneficiaries must make the switch by September 30, 2025, to avoid payment disruptions.

3. Iowa

In Iowa, proposed state budget reallocations could affect funding for programs supporting older adults. Governor Kim Reynolds’ initiative to fund full-time child care for 4-year-olds by diverting resources from existing early childhood programs may indirectly impact services that seniors rely on, though the direct effect on Social Security benefits remains uncertain.

4. Utah

Utah’s Governor Spencer Cox has proposed eliminating the state’s Social Security tax in the 2025 budget. While this move could save approximately 150,000 Utahns about $950 annually, it would reduce state revenue by $143.8 million each year, potentially affecting other state-funded programs.

5. Michigan

drawing of american state of michigan on chalkboard, drawn by chalk
Image Source: 123rf.com

Michigan residents have expressed concerns over potential Social Security cuts amid federal efforts to reduce spending. During town halls, constituents voiced fears about decreased access to benefits due to office closures and federal worker layoffs. Lawmakers have assured voters that Social Security will remain unaffected, but apprehensions persist. ​

6. Florida

Florida, with its significant retiree population, is closely monitoring federal discussions on Social Security reforms. Proposals to raise the retirement age or adjust benefit calculations could disproportionately affect Floridians. State officials are advocating for measures that protect their senior residents from potential benefit reductions.​

7. Nevada

Nevada’s retirees are attentive to federal policy changes that may impact Social Security. Discussions around modifying benefit formulas or taxation policies could have significant implications for the state’s senior population. Local advocacy groups are mobilizing to ensure that any changes consider the needs of retirees.​

8. South Dakota

In South Dakota, state officials are evaluating the potential impact of federal Social Security reforms on their residents. While no specific state-level changes have been proposed, the state’s seniors are encouraged to stay informed and engaged with ongoing policy discussions that could affect their benefits.​

9. Wyoming

Wyoming, known for its low tax burden, is also home to many retirees who depend on Social Security. Any federal adjustments to the program could have outsized effects here. State leaders are monitoring developments and considering strategies to support their senior residents amid potential changes,

State Level Actions and Proposals Can Influence Benefits

While Social Security is primarily a federal program, state-level actions and proposals can influence how benefits are administered and taxed. Staying informed about both federal and state developments is crucial to ensure you receive the benefits you’ve earned. Engaging with local advocacy groups and communicating with state representatives can help protect and enhance your Social Security benefits.​

Are you experiencing changes to your Social Security benefits in your state? Share your thoughts and experiences in the comments below.

Read More:

Are There Any Social Security Spousal Benefits Loopholes Left?

11 Key Changes to Your Social Security Benefits After Losing a Spouse

Headshot of Latrice Perez
Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Finance Tagged With: Colorado, Florida, Iowa, Michigan, Nevada, retirement benefits, Social Security, South Dakota, state policies, Texas, Utah, Wyoming

Could Wealth Inequality Destroy Democracy? The Warning Signs Are Already Here

February 28, 2025 by Latrice Perez Leave a Comment

Wealth Inequality
Image Source: 123rf.com

Wealth inequality has existed for centuries, but in recent years, the gap between the rich and the poor has grown at an alarming rate. As the ultra-wealthy consolidate their power, everyday citizens are left struggling to make ends meet. This growing disparity isn’t just about economics—it threatens the very foundation of democracy itself. When a small fraction of society holds disproportionate financial power, the political system begins to cater to their interests, leaving the majority without a voice.

The Rise of the Economic Elite

In modern democracies, money plays a crucial role in politics. From funding political campaigns to influencing policy decisions, wealth grants access to power in ways that most people can’t match. The wealthiest individuals and corporations donate large sums to political candidates, often ensuring that those in office prioritize their interests. This shift turns democratic governance into a system where policies are dictated by the economic elite rather than the will of the people.

Voter Suppression and Political Apathy

When people feel that their voices no longer matter, they become disengaged. Voter turnout declines, and those who do participate often feel powerless against a system that caters to the wealthy. In some cases, policies are deliberately designed to make it harder for lower-income citizens to vote, such as strict voter ID laws or limited polling locations in poorer areas. As a result, democracy weakens because the electorate no longer represents the full spectrum of society.

The Disintegration of the Middle Class

A thriving middle class is essential for a stable democracy. However, as wealth concentrates at the top, the middle class shrinks. Wages stagnate while the cost of living continues to rise, making it difficult for families to afford housing, healthcare, and education. This economic strain leads to frustration, anger, and resentment toward the political system, creating an environment ripe for social unrest.

The Influence of Corporate Power

Wealth and Politics
Image Source: 123rf.com

Large corporations have gained unprecedented influence over government policies. Lobbying efforts allow industries to push for laws that benefit their bottom line, often at the expense of workers and consumers. When lawmakers prioritize corporate profits over public welfare, trust in the government erodes. This cycle fosters an environment where ordinary citizens feel powerless against corporate-backed legislation.

The Rise of Populism and Extremism

When people feel that the system no longer works for them, they seek alternatives. This frustration often fuels the rise of populist leaders who promise radical change. While some populist movements advocate for meaningful reforms, others exploit public anger for personal gain. This shift can lead to extreme policies, weakened democratic institutions, and even authoritarian tendencies as leaders consolidate power under the guise of protecting the people.

Can Democracy Survive the Wealth Divide?

Despite these alarming trends, democracy is not doomed. However, reversing the damage requires significant effort. Campaign finance reform, progressive taxation, and policies that support economic mobility can help level the playing field. Strengthening voting rights and ensuring fair representation can also restore faith in the system. Ultimately, democracy thrives when power is distributed fairly, and addressing wealth inequality is a crucial step toward achieving that balance.

How do you feel about the current wealth divide in our country? How do you feel this inequality should be addressed. Let us know in the comments below.

Read More:

9 Reasons Why Baby Boomers Aren’t Leaving Much Wealth Behind

12 Private Clubs Only the Wealthy Can Afford

Headshot of Latrice Perez
Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Finance Tagged With: campaign finance reform, corporate power, democracy, economic divide, middle class decline, political influence, populism, voter suppression, wealth inequality

  • « Previous Page
  • 1
  • …
  • 23
  • 24
  • 25

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework