• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for retirement savings

10 Personal Finance Lessons People Learn the Hard Way

January 22, 2026 by Brandon Marcus Leave a Comment

These Are 10 Personal Finance Lessons People Learn the Hard Way
Image source: shutterstock.com

Money lessons rarely arrive politely. They crash into life during overdraft alerts, awkward conversations, or that sinking feeling after opening a credit card statement. Most of us don’t learn personal finance from calm instruction; we learn it from experience, stress, and a few “well, that didn’t work” moments.

The upside is that these lessons stick. They change habits, sharpen judgment, and turn past mistakes into future wisdom. Here are ten personal finance lessons people commonly learn the hard way, usually after their wallet has already taken a hit.

1. Spending More Than You Earn Always Catches Up

Living beyond your income feels manageable at first, especially when credit fills the gaps. Bills get paid, life looks normal, and the problem seems distant. Over time, though, the math becomes unavoidable. Interest compounds, balances grow, and flexibility disappears.

Many people only grasp this lesson after losing sleep over money or juggling due dates. Once learned, it often leads to tracking expenses, setting limits, and respecting the simple truth that income sets the ceiling.

2. An Emergency Fund Is Not Optional

Emergencies are rude, unpredictable, and expensive. Cars break down, jobs vanish, and medical bills appear without warning. Without savings, even small surprises can spiral into debt.

People usually learn this after relying on credit cards for emergencies and struggling to recover. A basic emergency fund provides breathing room and better choices. It turns crises into inconveniences instead of financial disasters.

3. Credit Cards Are Tools, Not Extra Income

Credit cards make spending feel painless, which is exactly the danger. Swiping now and worrying later often leads to balances that linger for years. Interest rates quietly punish unpaid balances month after month.

Many people realize this only after paying far more in interest than the original purchase cost. Used carefully, credit cards can build credit and offer protections. Used carelessly, they become very expensive loans.

4. Lifestyle Inflation Can Sabotage Raises

Earning more money feels like progress, and it is. The trap appears when spending rises just as fast. Bigger paychecks often bring bigger apartments, nicer cars, and more subscriptions.

At some point, people notice they feel just as broke as before, despite earning more. This lesson usually arrives with frustration and confusion. Keeping lifestyle inflation in check allows raises to actually improve financial security.

5. Ignoring Retirement Early Is Costly

Retirement feels far away, especially in your twenties and thirties. It’s easy to delay saving while focusing on current needs. Years later, people realize how powerful time and compound growth could have been. Catching up requires much larger contributions and sacrifices.

This lesson hits hardest when projections reveal uncomfortable gaps. Starting early, even with small amounts, dramatically reduces future stress.

6. Insurance Matters More Than It Seems

Insurance feels boring until the moment it’s desperately needed. Skipping coverage can save money short term, but the risk is enormous. Accidents, illnesses, and disasters can erase years of savings instantly.

Many people learn this lesson after paying out of pocket for something insurance would have covered. Proper coverage protects not just money, but stability and peace of mind. It’s about risk management, not optimism.

7. Not All Debt Is Created Equal

Debt often gets treated as a single category, but its impact varies widely. High-interest consumer debt drains finances quickly, while lower-interest debt can sometimes be strategic.

People often learn this after struggling to escape credit card balances while managing other obligations. Understanding interest rates and repayment terms changes priorities. It encourages attacking the most expensive debt first. This clarity can speed up financial recovery dramatically.

8. Small Purchases Add Up Faster Than Expected

Daily habits quietly shape financial outcomes. Coffee runs, delivery fees, and impulse buys seem harmless in isolation. Over months, they can consume hundreds or thousands of dollars.

Many people only notice after reviewing statements and feeling shocked by the totals. This lesson isn’t about deprivation. It’s about awareness and choosing what truly adds value.

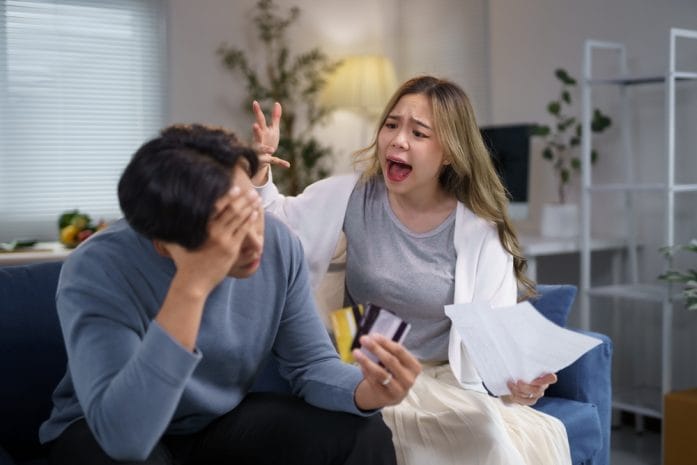
9. Money Stress Affects Relationships

Financial problems rarely stay contained to spreadsheets. They spill into conversations, decisions, and emotional well-being. Couples and families often clash over spending, saving, and priorities.

People usually recognize this lesson after tension builds or trust erodes. Open communication and shared goals reduce conflict. Managing money together requires honesty, compromise, and patience.
These Are 10 Personal Finance Lessons People Learn the Hard Way
Image source: shutterstock.com

10. No One Cares More About Your Money Than You Do

Advice comes from everywhere, but responsibility rests with the individual. Employers, banks, and even well-meaning friends have their own interests.

Many people learn this after blindly following guidance that didn’t fit their situation. Taking ownership means learning basics, asking questions, and paying attention. Confidence grows with knowledge. Ultimately, financial control starts with personal accountability.

Turning Hard Lessons Into Lasting Wins

Personal finance mistakes can sting, but they also teach clarity and resilience. Each hard-earned lesson strengthens future decisions and builds confidence over time. Money management isn’t about perfection; it’s about progress and awareness.

Everyone’s journey includes missteps, and those stories matter. Feel free to give your thoughts or add your own experiences in the comments section below.

You May Also Like…

Risk Proaction: 5 Steps to Stress-Test Your Finances for Worst-Case Scenarios

5 Lessons Young People Should Know About Investing

7 Old-School Life Lessons Only Today’s 50-Somethings Still Remember

5 Valuable Lessons Learned From Market Crashes Historically

7 Personality Clues That Predict Divorce Before It Happens

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: Debt, debt payoff, eliminating debt, emergency fund, emergency funds, finance, finance lessons, financial goals, financial lessons, lessons, Life, Lifestyle, Lifestyle Inflation, Money, money anxiety, money issues, money plans, money stress, overspending, Personal Finance, purchases, Retirement, retirement accounts, retirement plan, retirement planning, retirement savings, small purchases, Smart Spending, spending

10 Money Decisions That Feel Urgent Later in Life

January 20, 2026 by Brandon Marcus Leave a Comment

These Are 10 Money Decisions That Feel Urgent Later in Life
Image source: shutterstock.com

Money has a way of turning into a silent, persistent pressure cooker. One day, you’re breezing through your twenties thinking, “I’ll deal with that later,” and the next, you’re staring at a spreadsheet and wondering why no one warned you about the little things that spiral into life-altering dilemmas.

We all make financial decisions that feel trivial at the moment, but they suddenly scream for attention decades down the line. Some of them hit like a surprise plot twist in your favorite show—except this time, it’s your bank account. Let’s dive into ten decisions you might be putting off, but that could demand urgent attention later.

1. Not Starting Retirement Savings Early

Delaying retirement savings is the classic “I’ll start tomorrow” trap. Compound interest is like a quiet superhero; it’s powerful, but only if you give it time to work. Even small contributions in your twenties can balloon into life-changing sums by your sixties, while waiting too long means you’re playing catch-up with every paycheck.

Many people underestimate how much they need for retirement, assuming Social Security or pensions will cover the gap. By the time you realize you should’ve started, the pressure to save aggressively can feel suffocating. Starting now, even modestly, gives your future self a serious advantage.

2. Ignoring Emergency Funds

Life is unpredictable, and bills don’t care about your plans. Skipping an emergency fund can turn a minor car repair, medical bill, or job loss into a full-blown crisis. Financial advisors usually recommend three to six months’ worth of living expenses, but even a small cushion is better than none. Without it, you might find yourself relying on high-interest credit cards or loans, which can snowball faster than you expect. Building a safety net gradually doesn’t hurt your present, but it pays off immensely later. Once emergencies arise, the peace of mind from having a buffer is priceless.

3. Letting Debt Go Unmanaged

Debt has a sneaky way of multiplying if ignored. Student loans, credit cards, and personal loans accumulate interest that often outpaces inflation, meaning your balance grows even as you pay. Many people put off tackling debt thinking it’s “manageable,” until it becomes a heavy anchor on everything else in life. Addressing it early allows for strategic repayment plans, potential refinancing, or consolidation, which all reduce stress down the road. Unmanaged debt can limit your choices, from buying a home to investing in your future. Facing it head-on today saves headaches, sleepless nights, and financial strain tomorrow.

4. Skipping Health Insurance Planning

Health expenses are unpredictable, but skipping or underestimating insurance is a major pitfall. Medical bills can spiral into six figures unexpectedly, particularly in later adulthood when preventive care and chronic conditions become more common. Some young adults feel invincible and avoid paying for coverage, only to discover that a serious illness or accident can wipe out savings in months. Adequate health insurance acts as a protective shield, not just for emergencies but for everyday medical maintenance. Planning now avoids the scramble and financial jeopardy that often feels urgent in midlife.

These Are 10 Money Decisions That Feel Urgent Later in Life
Image source: shutterstock.com

5. Neglecting Long-Term Care Considerations

Long-term care isn’t just for the very elderly—it’s a planning step that many overlook. Assisted living, home modifications, or in-home help can be costly, and these expenses tend to rise faster than inflation. Without preparation, families often face emotional and financial stress simultaneously. Options like long-term care insurance or dedicated savings accounts give more control and flexibility later. It might feel remote in your thirties or forties, but thinking ahead keeps your independence intact. Ignoring it can turn what could have been a smooth transition into a financial and logistical scramble.

6. Underestimating Lifestyle Inflation

Lifestyle inflation happens quietly as income rises: bigger rent, fancier cars, more frequent vacations. While rewarding yourself is natural, unchecked spending increases your baseline expenses faster than your wealth grows. Suddenly, saving or investing feels impossible because the “new normal” consumes every extra dollar. Being mindful of lifestyle inflation allows you to balance enjoyment with growth, ensuring your future self isn’t stressed over missed opportunities. Small choices today—like saving raises instead of spending them all—can compound into financial freedom later.

7. Postponing Estate Planning

No one likes thinking about death, but delaying estate planning is a costly oversight. Wills, trusts, and beneficiary designations protect loved ones and prevent legal chaos. Without a plan, assets can be tied up in court, creating delays and expenses for heirs. Estate planning also includes powers of attorney and healthcare directives, which matter far sooner than most expect. Tackling this early ensures clarity and reduces emotional strain during difficult times. Your future self—and your family—will thank you for thinking ahead.

8. Ignoring Tax-Advantaged Accounts

401(k)s, IRAs, HSAs—these aren’t just buzzwords. Tax-advantaged accounts can significantly boost wealth over decades, but ignoring them leaves money on the table. Many people focus on today’s spending and forget the exponential benefits of tax savings and compounding. Starting contributions early maximizes these accounts’ power and gives more flexibility for major life goals. Failing to use them is like leaving a bonus paycheck unclaimed every year. When you realize the opportunity cost decades later, it can feel like a wake-up call you wish you had earlier.

9. Avoiding Financial Education

Understanding basic finance isn’t glamorous, but skipping it creates a lifetime of stress. Knowing how interest works, how to invest, and how to read financial statements arms you with control and confidence. Many people make avoidable mistakes simply from ignorance—like high fees, bad investments, or missed deductions. Lifelong learning about money turns uncertainty into strategy. The earlier you start, the fewer surprises and regrets you’ll face. Knowledge compounds just like money; the sooner you invest in it, the bigger the payoff.

10. Delaying Conversations About Money With Loved Ones

Family money conversations are awkward, but postponing them can lead to misunderstandings, resentment, or missed opportunities. From inheritance plans to joint expenses or household budgeting, clear communication reduces stress. Many people wait for emergencies to bring up finances, which adds pressure and emotional strain. Early discussions establish expectations, foster cooperation, and prevent financial surprises. Talking openly might feel uncomfortable now, but it saves a lifetime of tension later.

Reflect And Engage

Money is more than numbers—it’s freedom, stress, opportunity, and sometimes, a sneaky source of regret if we ignore it. The choices we make today ripple through the decades, shaping our options, comfort, and peace of mind.

Which of these ten decisions resonates with your life most? Have you already faced some of these challenges or learned lessons the hard way? Drop your thoughts or personal stories in the comments.

You May Also Like…

Could Giving Money to Friends Be the Worst Investment Choice

Why Do People Feel Guilty Spending Money Even on Necessitiesd

9 Money Assumptions That No Longer Work in Today’s Economy

How Can Student Loans Quietly Shape Life Decisions for Decades

What Are The Worst Choices You Can Make As A New Investor?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: 401(k), Debt, debt payoff, eliminating debt, emergency funds, Estate planning, financial choices, financial decisions, health insurance, healthcare costs, Life, Lifestyle, Lifestyle Inflation, Money, money choices, money decisions, money issues, Retirement, retirement account, retirement savings

10 Financial Wake-Up Calls People Experience After Age 55

January 13, 2026 by Brandon Marcus Leave a Comment

These Are 10 Financial Wake-Up Calls People Experience After Age 55
Image Source: Shutterstock.com

Turning 55 can feel like stepping onto a financial rollercoaster you didn’t exactly buy a ticket for. One minute, you’re comfortably cruising through your career, and the next, a cascade of bills, taxes, and retirement worries hits like a surprise drop. Life doesn’t hand out a manual at this age, but it does offer a series of wake-up calls that can either jolt you into action or leave you scrambling.

From unexpected medical expenses to realizing your retirement savings aren’t quite what you thought, these financial alarms are loud, unavoidable, and—if you pay attention—highly motivating.

1. Retirement Savings Suddenly Look Smaller Than You Remembered

It’s a jolt when you finally sit down and do the math. All those years of socking away money in 401(k)s, IRAs, and other accounts suddenly don’t stretch as far as you imagined. Inflation has quietly chipped away at your purchasing power, and market dips may have erased gains you thought were untouchable. Many people realize they need to either work longer, invest smarter, or tighten spending.

This isn’t a panic button moment; it’s a wake-up call to take control. Reviewing your savings strategies and adjusting contributions—even at this stage—can make a huge difference. The key is to confront the numbers head-on instead of hiding from them.

2. Health Costs Start to Take a Bigger Bite

Health insurance premiums, prescription costs, and specialist visits tend to rise sharply after 55. Even people who’ve been careful with their budgets can be caught off guard by the sheer scale of medical expenses. Preventive care and early screenings become non-negotiable, but they add up. Without a solid plan, a few unexpected procedures can throw off months of financial stability. Long-term care insurance or a robust health savings account (HSA) can help, but realizing these costs is a serious wake-up call for planning. Suddenly, the question shifts from “Can I afford a vacation?” to “Can I handle an emergency hospital stay?”

3. Social Security Decisions Feel Overwhelming

At some point after 55, Social Security creeps into conversations and planning. The decisions—when to start taking benefits, how it will impact taxes, and how it interacts with retirement savings—can be more complicated than expected. Many people underestimate the long-term effects of claiming early or delaying benefits. It’s a critical moment to study options and potentially speak with a financial advisor. Understanding how Social Security works now can prevent regrets later. For many, the realization hits: timing really is everything, and small decisions now can create a huge impact in retirement.

4. Debt Suddenly Feels Heavier

Debt that seemed manageable in your 40s or early 50s can feel like a mountain as you approach retirement. Mortgage balances, credit card debt, and lingering personal loans suddenly become stress points. The closer you get to retirement, the more urgent it is to minimize these obligations. Interest payments that once seemed tolerable can consume a large portion of your budget. Many people feel a mix of guilt and motivation as they face the reality of carrying debt into the next chapter of life. Aggressive debt reduction plans or refinancing can offer a sense of relief and control.

5. Housing Plans Become Pressing

Whether you’re thinking about downsizing, relocating, or aging in place, housing becomes a financial and emotional focus after 55. The cost of maintenance, property taxes, and potential renovations can take a bigger chunk out of your budget than expected. Many realize their dream retirement home might require more saving—or compromise—than they imagined. This wake-up call forces a reckoning: your living situation affects not just comfort but financial stability. Planning early allows you to explore options like reverse mortgages or equity strategies without panic. Home is more than walls; it’s a financial cornerstone.

6. Taxes Get More Complicated

As income streams diversify through investments, side businesses, or retirement distributions, taxes become less predictable. People over 55 often discover that they may owe more than expected, especially with withdrawals from retirement accounts. Capital gains, RMDs (required minimum distributions), and changes in tax law can create surprises. Ignoring taxes until April is a risky strategy now. Smart planning—deductible contributions, tax-efficient withdrawals, or professional guidance—becomes critical. It’s a wake-up call to stop procrastinating and understand the intricacies of your financial footprint.

7. Long-Term Care Planning Isn’t Optional

The reality of needing long-term care—whether at home or in a facility—becomes real after 55. The costs are staggering, often exceeding savings for many. Without planning, a sudden health crisis can wipe out decades of careful financial preparation. Long-term care insurance or creating a dedicated fund can mitigate this risk, but most people realize too late that they should have started sooner. It’s one of the clearest wake-up calls: your health and independence may depend on proactive financial moves. Preparing for the unexpected transforms fear into strategy.

These Are 10 Financial Wake-Up Calls People Experience After Age 55
Image Source: Shutterstock.com

8. Lifestyle Inflation Becomes More Noticeable

At 55, you may have reached peak earnings, but lifestyle inflation can be stealthy. Vacations, hobbies, and daily comforts that once felt reasonable now compete with retirement savings. It’s a wake-up call to examine discretionary spending with a sharper eye. Many people realize they’ve adjusted their spending upward alongside income, leaving less room for true financial security. Conscious budgeting and thoughtful choices can help preserve the life you want without derailing your future. It’s a subtle but significant alarm that money habits matter at every age.

9. Inheritance And Estate Planning Become Real

Suddenly, questions about wills, trusts, and estate planning feel urgent. Even if you’ve never thought about these details, turning 55 often triggers a deep awareness of legacy. Without proper planning, assets may not pass on according to your wishes, and loved ones could face unnecessary stress or tax burdens. It’s a wake-up call to organize documents, designate beneficiaries, and consider estate strategies. Addressing these issues proactively is empowering. It ensures that your financial journey includes not just personal security but also care for the people you love.

10. The Urgency Of Financial Education Hits Hard

Many people realize that their knowledge of investments, taxes, and retirement planning was patchy at best. Suddenly, you’re faced with decisions that have real consequences for decades ahead. This wake-up call is about empowerment: learning how money works now can drastically improve outcomes. Seminars, books, advisors, and courses are no longer optional—they’re essential. The earlier you embrace financial literacy, the more options you preserve. After 55, understanding the rules of money isn’t just smart—it’s critical to freedom and peace of mind.

Your Thoughts And Experiences

Financial wake-up calls after 55 can feel intimidating, but they’re also a chance to take control and make intentional choices. Each challenge—whether it’s retirement planning, health costs, or estate preparation—is an opportunity to reassess, adjust, and act strategically.

Have you encountered one of these wake-up calls? How did it change the way you approach money? Your reflections and experiences can provide insight for others navigating this exciting but complex stage of life.

Drop your thoughts in the comments below and let’s spark a conversation about smart financial moves after 55.

You May Also Like…

8 Home Upgrades Seniors Are Choosing Over Moving Into Facilities

Funding Gap: 8 Ways Rising College Costs Are Changing Mid-Life Financial Planning

Why Does Retirement Feel More Expensive Than People Planned For

How a Solid Estate Plan Can Protect Your Finances

12 Capital-Gains Surprises When You Sell the Family Home After 55


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: bad financial habits, Debt, debt payoff, finance, finances, financial choices, financial decisions, financial wake-up calls, general finance, health costs, healthcare, healthcare costs, housing, paying off debt, Planning, retire, retiree, retirees, Retirement, retirement savings, Social Security, taxes

Savings Repair: 4 Moves to Catch Up if You’re Within 10 Years of Retirement

January 6, 2026 by Brandon Marcus Leave a Comment

Savings Repair: 4 Moves to Catch Up if You're Within 10 Years of Retirement
Image Source: Shutterstock.com

The countdown clock is louder than ever, your retirement date is no longer abstract, and suddenly every financial decision feels like it matters more. That mix of urgency and possibility can be electrifying rather than terrifying, because this is the phase where smart moves still create dramatic results. You are not late to the game; you are simply entering the high-impact round where focus beats perfection.

With roughly a decade left, your choices can still compound, protect, and accelerate your future lifestyle. This is the moment to stop worrying about what didn’t happen earlier and start executing a plan that works right now.

1. Maximize Catch-Up Contributions Everywhere Possible

If you are 50 or older, retirement accounts unlock special catch-up contributions that act like turbo boosters for your savings. Workplace plans such as 401(k)s and 403(b)s allow higher annual limits, and IRAs offer extra contribution room as well. These increases may seem modest year to year, but over a decade they can translate into tens of thousands of additional dollars working for you.

Automating contributions removes emotion from the process and keeps progress steady. The real win is consistency, because every extra dollar invested now has less time to wait and more urgency to grow.

2. Get Ruthlessly Strategic With Your Investment Mix

As retirement approaches, investment strategy shifts from pure growth toward a balance of growth and protection. This does not mean abandoning stocks entirely, but it does mean understanding your risk tolerance with fresh eyes. A diversified mix of equities, bonds, and cash-like assets can help smooth volatility while still pursuing returns.

Rebalancing annually keeps your portfolio aligned with your goals rather than market noise. The objective is not to beat the market, but to arrive at retirement with confidence and stability.

3. Delay Retirement By Months, Not Decades

Working a little longer can have an outsized effect on your retirement readiness, even if the delay is shorter than you expect. Each extra working year means more savings, fewer years of withdrawals, and potentially higher Social Security benefits. Even part-time or consulting work can reduce pressure on your nest egg in early retirement. This approach offers flexibility rather than sacrifice, especially if you enjoy what you do. Sometimes the most powerful financial move is simply buying yourself a bit more time.

4. Shrink Future Expenses Before They Shrink You

Reducing expenses late in your career is about intention, not deprivation. Paying off high-interest debt, downsizing thoughtfully, or relocating strategically can dramatically lower your required retirement income. Every dollar you do not need to spend is a dollar you do not need to save or withdraw. Health care planning, including HSAs and insurance reviews, deserves special attention in this stage. Designing a leaner, smarter lifestyle now gives you control rather than forcing adjustments later.

Savings Repair: 4 Moves to Catch Up if You're Within 10 Years of Retirement
Image Source: Shutterstock.com

Your Comeback Window Is Wide Open

Being within ten years of retirement is not a deadline, it is a launchpad. The actions you take now can rewrite expectations and replace anxiety with momentum. Progress at this stage comes from clarity, commitment, and a willingness to adjust old habits. Everyone’s path looks different, and real-world experiences often reveal strategies no spreadsheet can capture.

Jump into our comments section below and add your perspective or personal journey to keep the conversation moving.

You May Also Like…

Savings Leap: 9 Mid-Life Moves That Boost Long-Term Retirement Odds

Income Stability: 6 Retirement Income Moves That Aren’t as Safe as They Seem

At What Age Should You Seriously Start Thinking About Retirement?

Retirement Redflag: 6 Withdrawal Moves That Could Drain Your Nest Egg Fast

5 Surprising Risks of Keeping Large Savings at Home

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: 401(k), 401k contributions, 401k plans, contributions, expenses, Investment, retire, retiree, retirees, Retirement, retirement accounts, retirement plans, retirement savings

Risk Scenario: 8 What-Ifs Every Pre-Retiree Should Consider

January 5, 2026 by Brandon Marcus Leave a Comment

Risk Scenario: 8 What-Ifs Every Pre-Retiree Should Consider
Image Source: Shutterstock.com

The countdown to retirement can feel like the opening credits of an adventure movie, all promise and possibility. You’ve worked hard, dreamed big, and imagined mornings without alarms and afternoons without meetings. But every great adventure needs a smart plan, because surprises love to crash the party when expectations get comfy.

This is where risk scenarios step in, not to scare you, but to sharpen your instincts and strengthen your strategy. Think of this as a fast-paced tour through eight “what-ifs” that can make or break your retirement story.

1. What If The Market Drops Right After You Retire?

Sequence-of-returns risk is real, and timing matters more than most people expect. A sharp downturn early in retirement can permanently dent a portfolio. Withdrawals during losses lock in damage and reduce future recovery power. Diversification helps, but flexibility helps even more. Having cash reserves or adjustable spending can change everything.

2. What If You Live Much Longer Than Planned?

Longevity is a gift, but it comes with a price tag. Many people underestimate how long retirement can actually last. A 30-year retirement is no longer unusual. Running out of money late in life is one of the biggest fears pre-retirees face. Planning for a longer horizon adds resilience and confidence.

3. What If Healthcare Costs Explode?

Healthcare is often the wildcard expense nobody fully nails down. Premiums, deductibles, and out-of-pocket costs can stack up fast. Long-term care is especially expensive and often overlooked. Medicare helps, but it does not cover everything. Building a healthcare buffer can prevent painful trade-offs later.

Risk Scenario: 8 What-Ifs Every Pre-Retiree Should Consider
Image Source: Shutterstock.com

4. What If Inflation Stays Higher Than Expected?

Inflation quietly erodes purchasing power year after year. Even modest inflation can double expenses over a long retirement. Fixed incomes feel the squeeze first and hardest. Growth assets can help offset rising costs. Ignoring inflation risk is like planning a road trip without checking fuel.

5. What If Taxes Change In Retirement?

Tax rules are not carved in stone, and future rates are uncertain. Retirement income can come from many buckets with different tax treatments. Poor withdrawal sequencing can trigger unnecessary taxes. Required minimum distributions may push income higher than expected. Smart tax planning can stretch savings further.

6. What If Family Needs Financial Help?

Adult children, aging parents, or unexpected family crises can shift priorities overnight. Emotional decisions often override carefully crafted budgets. Helping loved ones feels right, but it has real financial consequences. Boundaries protect both relationships and retirement security. Planning for generosity prevents resentment and regret.

7. What If Your Lifestyle Costs More Than Expected?

Retirement spending rarely drops in a straight line. Travel, hobbies, and home projects often surge early on. Lifestyle creep can sneak up disguised as well-earned fun. Tracking spending reveals patterns before they become problems. Intentional choices keep enjoyment high and stress low.

8. What If Cognitive Decline Or Fraud Becomes A Risk?

Aging can bring cognitive changes that affect financial decisions. Scammers often target retirees with alarming precision. Simple mistakes can snowball into major losses. Trusted contacts and safeguards provide critical protection. Planning for this risk is an act of self-respect.

Turning What-Ifs Into Confidence

Retirement planning is not about predicting the future perfectly but about preparing for it wisely. These what-ifs are not warnings of doom, they are invitations to think clearly and act proactively. When you face risks head-on, they lose much of their power. Your retirement story deserves flexibility, foresight, and a little courage.

Feel free to add your own experiences or lessons in the comments below and keep the conversation going.

You May Also Like…

Income Stability: 6 Retirement Income Moves That Aren’t as Safe as They Seem

Savings Leap: 9 Mid-Life Moves That Boost Long-Term Retirement Odds

Expense Overflow: 4 Retirement Bills That Catch People Off Guard

In Your 30s? Here Are 3 Simple Tips to Start Planning for Retirement

Could Rising Interest Rates Force You To Delay Retirement Longer Than Planned?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: investing risk, market, plans, retire, retiree, retirees, Retirement, retirement account, retirement planning, retirement savings, risk, risk scenario, stock market

Tax Foresight: 6 Planning Moves That Could Save You Money Soon

January 5, 2026 by Brandon Marcus Leave a Comment

Tax Foresight: 6 Planning Moves That Could Save You Money Soon
Image Source: Shutterstock.com

Fireworks don’t usually go off when someone mentions taxes, but this is where the story flips. Smart tax planning can feel like unlocking a secret level where the rewards are real cash, less stress, and way more control. Instead of scrambling at filing time, a little foresight lets you play offense, not defense, with your money.

These moves aren’t about loopholes or gimmicks; they’re about using existing rules wisely and confidently. Listen closely, because the right planning today can make future-you very glad you paid attention.

1. Maximize Retirement Contributions Early

Putting more into retirement accounts can reduce taxable income while building long-term wealth at the same time. Contributions to traditional 401(k)s and IRAs are often tax-deductible, which can lower what you owe this year. Starting early in the year spreads the impact across paychecks and feels less painful than a late rush. Many employers also match contributions, which is essentially free money with tax advantages. Over time, tax-deferred growth can turn consistent planning into serious savings.

2. Harvest Investment Losses Strategically

Tax-loss harvesting allows investors to sell underperforming assets to offset taxable gains elsewhere. This move can help reduce capital gains taxes without changing long-term investment strategy. Losses beyond gains may even offset a portion of ordinary income, within IRS limits. Timing matters, especially around year-end and wash sale rules. Done carefully, this strategy turns market dips into a planning advantage instead of a frustration.

3. Use Health Accounts As Stealth Tax Shields

Health Savings Accounts are one of the most tax-efficient tools available when paired with eligible health plans. Contributions are typically pre-tax, growth is tax-free, and qualified withdrawals avoid taxes entirely. Few accounts offer this triple benefit, which makes HSAs powerful long-term planning vehicles. Funds can roll over year after year, unlike flexible spending accounts. Treating an HSA as an investment account can quietly protect thousands from future taxes.

4. Time Income And Deductions With Intention

When income or expenses can be shifted, timing becomes a powerful planning lever. Deferring income to a later year may reduce exposure to higher tax brackets. Accelerating deductions, like charitable gifts or business expenses, can increase immediate tax benefits. This approach works especially well for freelancers, business owners, and retirees with flexible income streams. Thoughtful timing can smooth out tax bills and prevent unpleasant surprises.

Tax Foresight: 6 Planning Moves That Could Save You Money Soon
Image Source: Shutterstock.com

5. Take Credits Seriously, Not Casually

Tax credits directly reduce taxes owed, making them more valuable than deductions in many cases. Credits for education, childcare, energy efficiency, and dependent care can add up quickly. Eligibility rules matter, so awareness is key to claiming what’s allowed. Some credits are refundable, meaning they can boost refunds even if taxes owed are low. Missing credits often means leaving real money on the table.

6. Review Withholding And Estimated Payments Regularly

Withholding that’s too high gives the government an interest-free loan, while too low can trigger penalties. Regular reviews help align payments with actual tax obligations as life changes. Job shifts, side income, bonuses, and investments can all throw off estimates. Adjusting throughout the year keeps cash flow predictable and stress levels lower. This simple habit can prevent last-minute panic and unexpected bills.

Plan Ahead And Stay Curious

Tax planning doesn’t require obsession, but it does reward attention and curiosity. Each move builds on the idea that informed choices today can unlock savings sooner than expected. Everyone’s situation is different, which makes learning from others especially valuable.

If you’ve tried any of these strategies or learned something the hard way, the comments section below is waiting. Your experiences might spark someone else’s next smart move.

You May Also Like…

Income Threshold: 4 Hidden Taxes That Hit Once You Cross Certain Limits

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

9 Financial Dangers of Ignoring Property Taxes

Tax Surge: 4 Income Types That Trigger Hidden Tax Bills

Income Stability: 6 Retirement Income Moves That Aren’t as Safe as They Seem

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Tax Planning Tagged With: 401(k), deductions, filing taxes, health accounts, Income, income taxes, retirement accounts, retirement contributions, retirement savings, tax planning, tax plans, tax tips, taxes

Tax Breakthrough: 6 Little-Known Credits Still Available This Year

January 3, 2026 by Brandon Marcus Leave a Comment

Tax Breakthrough: 6 Little-Known Credits Still Available This Year
Image Source: Shutterstock.com

Tax season doesn’t have to feel like a slog through paperwork and headaches. In fact, it can be downright thrilling if you know where to look. While most taxpayers chase the usual deductions, a treasure trove of little-known credits quietly waits to boost your refund—or shrink your bill.

These hidden gems could save you hundreds, even thousands, if you’re savvy enough to claim them. Buckle up, because we’re diving into six tax credits that might just make this your happiest filing season yet.

1. The Saver’s Credit That Rewards Retirement Contributions

Many Americans overlook the Saver’s Credit, which gives eligible taxpayers a dollar-for-dollar reduction for contributions to retirement accounts. If you’ve been diligently feeding a 401(k) or IRA, this credit could be a delightful bonus. It’s especially helpful for lower- to moderate-income filers, who can see up to $1,000 (or $2,000 if married) deducted right off their taxes. Unlike deductions that only reduce taxable income, this credit directly reduces the amount you owe. Don’t let your diligent saving go unrewarded—this one is worth a careful look.

2. The Residential Energy Efficient Property Credit

Going green might save the planet and your wallet. The Residential Energy Efficient Property Credit rewards homeowners who install solar panels, solar water heaters, or certain wind and geothermal systems. Depending on the year and technology, it can cover a substantial portion of installation costs. What’s more, this credit is non-refundable, meaning it can significantly lower your tax bill without you needing to wait for a refund. If you’ve been considering energy upgrades, this credit is a golden incentive.

3. The Adoption Credit For Growing Families

Adopting a child comes with emotional rewards, but the financial side can be daunting. Enter the Adoption Credit, designed to ease adoption-related expenses such as agency fees, court costs, and travel. For 2026, families can claim up to tens of thousands of dollars per child, depending on expenses. It’s non-refundable, but it can carry forward for five years if your credit exceeds your tax liability. This credit ensures that welcoming a child into your home doesn’t drain your wallet as much as it might otherwise.

4. The Child And Dependent Care Credit

Daycare isn’t cheap, but the Child and Dependent Care Credit can turn part of that cost into a tax-saving opportunity. It applies to children under 13 or other dependents who need care while you work or look for work. The credit can cover a significant percentage of expenses, with higher benefits for lower-income households. Recent updates have increased the maximum credit and expanded eligibility, making it more accessible than ever. Parents juggling work and care now have a legitimate financial lifeline during tax season.

5. The Lifetime Learning Credit For Continuing Education

Education isn’t just for kids—it can be a strategic tax tool for adults, too. The Lifetime Learning Credit allows taxpayers to deduct up to $2,000 for qualified tuition and related expenses per year. Unlike the American Opportunity Credit, this one has no limit on the number of years you can claim it. Courses don’t have to be part of a degree program, opening doors for professional certifications and skill upgrades. For anyone looking to advance their career while easing tax burdens, this credit is a hidden gem.

6. The Earned Income Tax Credit For Low-To-Moderate Earners

The Earned Income Tax Credit (EITC) is one of the most powerful tools for boosting refunds, yet it often flies under the radar. Available to low- and moderate-income workers, the EITC amount varies based on income, filing status, and number of qualifying children. Eligible filers can receive thousands of dollars, sometimes more than they paid in federal taxes during the year. Many miss this credit simply because they assume it’s too complicated to claim. Don’t overlook it—this is a serious opportunity for a financial boost.

Tax Breakthrough: 6 Little-Known Credits Still Available This Year
Image Source: Shutterstock.com

Your Thoughts On These Hidden Credits

Tax credits like these are proof that careful planning can transform tax season from a chore into a strategic win. With proper research, anyone can uncover benefits that might otherwise go unclaimed.

Which of these credits have you taken advantage of, or which ones are you considering this year? Drop your experiences and insights in the comments section below so other readers can learn from your story.

You May Also Like…

Income Threshold: 4 Hidden Taxes That Hit Once You Cross Certain Limits

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

9 Financial Dangers of Ignoring Property Taxes

Risk Proaction: 5 Steps to Stress-Test Your Finances for Worst-Case Scenarios


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: adoption, children., dependents, Earned Income Tax Credit, filing taxes, retirement account, retirement contributions, retirement savings, Tax, tax credits, tax season, taxes

Asset Underused: 4 Plays Advisors Say Most Investors Overlook

January 1, 2026 by Brandon Marcus Leave a Comment

Asset Underused: 4 Plays Advisors Say Most Investors Overlook
Image Source: Shutterstock.com

Investing isn’t just about buying the latest hot stock or following every headline that flashes across your phone. The smartest investors often win not by chasing the obvious, but by exploiting the hidden opportunities that most people ignore. While many focus on the loud, flashy moves, there’s a quiet arsenal of tools that can supercharge wealth if used correctly.

Financial advisors call them the “underused assets”—those strategies that are hiding in plain sight but overlooked by everyday investors. These four plays could transform how you think about growing and protecting your money.

1. Tax-Loss Harvesting For Extra Gains

Most investors don’t realize that losses aren’t just setbacks—they can be powerful tools when strategically applied. Tax-loss harvesting allows you to sell underperforming investments to offset gains elsewhere, which can reduce your taxable income without hurting your overall portfolio growth. Many people fear selling at a loss, but when used wisely, this strategy can save thousands each year and even free up capital for new opportunities.

Advisors stress timing and record-keeping, since the IRS has specific rules, like the wash-sale rule, that need to be followed. Ignoring tax-loss harvesting is like leaving money on the table every year—money that could otherwise compound in your portfolio.

2. Dividend Reinvestment Plans That Compound Wealth

Dividends are often treated as spare change, but reinvesting them automatically can transform small payouts into massive gains over decades. Dividend Reinvestment Plans (DRIPs) allow investors to use the dividends they receive to purchase more shares without paying additional fees. This creates a snowball effect, where your earnings generate more earnings without you lifting a finger. Many investors take dividends as cash, missing out on the compounding power that can exponentially grow a portfolio. Advisors note that even moderate reinvestments can significantly outperform portfolios where dividends are left untouched over long periods.

3. Asset Location Strategies To Minimize Taxes

Where you hold an investment can be just as important as what you hold. Asset location is the strategic placement of investments across taxable accounts, tax-deferred accounts, and tax-free accounts to optimize tax efficiency. For example, placing bonds in tax-deferred accounts and stocks in taxable or tax-free accounts can reduce yearly tax bills and accelerate wealth growth.

Many investors ignore this nuance, assuming it doesn’t matter, but advisors insist that a thoughtful approach to account placement can save tens of thousands of dollars over a lifetime. Understanding asset location turns basic portfolio allocation into a precision tool for maximizing net returns.

4. Retirement Catch-Up Contributions For Late Starters

Investors who start late often panic and think it’s too late to catch up on retirement savings, but catch-up contributions can make a huge difference. Once you reach 50, the IRS allows higher annual contributions to 401(k)s and IRAs, giving you a turbo boost for retirement planning.

Many people aren’t aware of this, or they underestimate its power, leaving a critical opportunity underused. Advisors say this move not only increases contributions but also leverages years of compounded growth before retirement. Even a few extra thousand dollars each year can dramatically alter the trajectory of your nest egg if applied consistently.

Asset Underused: 4 Plays Advisors Say Most Investors Overlook
Image Source: Shutterstock.com

Start Using Hidden Plays Today

These four strategies aren’t just theoretical—they’re actionable plays that investors can implement immediately to strengthen portfolios, reduce taxes, and accelerate growth. Ignoring them means leaving potential gains untapped and growth slower than it could be. Financial advisors consistently see clients succeed dramatically once they start using these underused assets effectively.

Now it’s your turn to take control, examine your own strategies, and see where hidden opportunities may lie. We want to hear your experiences or tips on maximizing overlooked investment plays in the comments section below.

You May Also Like…

Regulation Corner: 6 Hurdles Advisors Expect Clients to Face Next Year

Asset Pivot: 6 Real-World Allocation Moves Advisors Are Using This Month

Asset Exposure: 6 Categories of Investments That Might Be Over-Represented

Regulation Checklist: 9 Conversations Advisors Are Having With Clients Right Now

Asset Migration: 5 Emerging Market Trends Retirees Should Know Before January


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Financial Advisor Tagged With: advice, assets, Dividends, finance, finances, financial advisor, financial advisors, financial choices, financial decisions, invest, investing, Investor, investors, reinvestment, retirement account, retirement savings, tax losses, taxes

Could Rising Interest Rates Force You To Delay Retirement Longer Than Planned?

December 26, 2025 by Brandon Marcus Leave a Comment

Could Rising Interest Rates Force You To Delay Retirement Longer Than Planned?
Image Source: Shutterstock.com

The thrill of retirement often feels like standing at the edge of a diving board, ready to leap into years of freedom, adventure, and late-morning pancakes. But what if the water below has suddenly shifted? Rising interest rates might seem like an abstract economic term, reserved for financial headlines or talking heads in suits, but they can ripple directly into your retirement plans.

Suddenly, the cozy vision of early retirement, stress-free vacations, and endless hobbies can feel like it’s slipping further away. Understanding how interest rates interact with your finances could be the difference between retiring when you want and postponing your dreams for several more years.

How Rising Interest Rates Impact Your Investments

Interest rates are the invisible force that shapes the value of everything from savings accounts to stocks and bonds. When rates climb, the price of existing bonds generally falls, because new bonds are paying more, making older ones less attractive. Stock markets can also react, as higher borrowing costs for companies can slow growth and reduce profits. Retirees who rely on investment portfolios may find their nest egg growing more slowly, or even shrinking in real terms. The effect can be especially jarring for those counting on fixed-income investments to fund living expenses in retirement.

The Connection Between Mortgages And Retirement Timing

If you have a mortgage or are considering buying a home before retirement, rising interest rates can directly affect your monthly payments. Higher rates mean higher interest costs, leaving less disposable income to funnel into retirement accounts. Those planning to downsize or relocate may face increased financing costs, making the move less feasible. Even homeowners who are mortgage-free can feel the indirect effects, as property values may stagnate or fall with rate hikes. In short, your dream retirement home might not be as affordable as you initially calculated.

Inflation And Its Sneaky Role In Retirement

Interest rates often rise in response to inflation, and inflation can quietly erode the purchasing power of your savings. A dollar saved today may not buy as much in a few years, forcing retirees to withdraw more to maintain their lifestyle. This effect is compounded if your income sources, like pensions or social security, are fixed. Rising rates alone aren’t the culprit—it’s the combination of inflation and rates that can pressure your retirement timeline. Retirees may need to rethink their budgets, adjust expectations, or work a few extra years to protect their standard of living.

How Retirement Accounts Respond To Rate Changes

Different retirement accounts respond differently to interest rate fluctuations. Traditional 401(k)s and IRAs invested heavily in bonds can lose value when rates rise, while accounts tilted toward equities might see volatility without guaranteed losses. Fixed annuities or CDs may suddenly look more attractive because new contracts pay higher returns. Understanding the composition of your retirement portfolio is critical to avoid being caught off guard. Regular portfolio reviews can reveal opportunities to rebalance investments in a way that mitigates risk while taking advantage of higher interest rates.

The Psychological Effect Of Delayed Retirement

The idea of working longer than planned can be emotionally taxing. Many people plan retirement with a set age in mind, and adjusting to a later exit can feel like losing control. Stress and anxiety can creep in, affecting health and overall quality of life. Some retirees may rush into retirement prematurely, taking bigger financial risks to make up for lost time. Recognizing the mental and emotional aspects of a delayed retirement can help you make more rational decisions during uncertain financial periods.

Could Rising Interest Rates Force You To Delay Retirement Longer Than Planned?
Image Source: Shutterstock.com

Strategies To Stay On Track Despite Rising Rates

Even if interest rates are rising, there are proactive strategies to protect your retirement goals. Diversifying your investments across stocks, bonds, and alternative assets can cushion against rate-driven losses. Delaying withdrawals from retirement accounts or scaling back discretionary spending can help your savings last longer. Refinancing high-interest debt before rates spike is another practical move. Consulting with a financial advisor who understands the current economic landscape can provide tailored advice and prevent costly mistakes.

Considering Partial Retirement Or Flexible Work

Not every delay in retirement has to be a complete setback. Partial retirement, consulting, or part-time work can help bridge the income gap while maintaining lifestyle goals. Flexible work options reduce the stress of abrupt financial changes and provide a cushion against rate volatility. Many retirees discover that phased retirement offers personal fulfillment and additional savings simultaneously. This approach can also allow your investments to recover and grow more effectively during periods of uncertainty.

The Importance Of Emergency Funds And Safety Nets

Rising interest rates can test even the most disciplined savers, making robust emergency funds more essential than ever. Liquidity ensures you aren’t forced to tap retirement accounts prematurely, which can incur taxes and penalties. Keeping a cash cushion also provides peace of mind during periods of market volatility. Adequate reserves allow you to navigate unexpected expenses without derailing long-term retirement plans. A solid safety net is one of the few financial shields entirely within your control.

Preparing For The Unexpected

Economic environments are unpredictable, and interest rates are just one piece of the puzzle. Health issues, market crashes, or family responsibilities can all impact your retirement timeline. Being flexible and having contingency plans can turn potential setbacks into manageable adjustments. Monitoring both macroeconomic trends and personal finances is crucial to staying ahead. Ultimately, preparation and adaptability are your best allies in preserving the retirement you’ve envisioned.

Your Thoughts On Retirement Timing

Rising interest rates are more than a headline—they’re a tangible factor that can affect how and when you retire. By understanding the interplay between rates, investments, inflation, and lifestyle, you can make informed decisions to protect your future. Strategies such as diversification, flexible work, and robust emergency funds can mitigate the pressure to delay retirement. The key is to stay proactive and consider how small adjustments today can preserve your dreams for tomorrow.

Let us know your thoughts or experiences with interest rates affecting retirement in the comments section below.

You May Also Like…

Pension Shock: 9 Myths About Social Security That Could Derail Your Retirement

Savings Sprint: 9 Ways to Catch Up on Retirement Savings Before December Ends

Debt Overhang: 8 Ways Carrying Debt Into Retirement Can Undermine Your Progress

6 Vital Signs Your Advisor Isn’t Putting Your Interests First

Are There Undisclosed Conflicts of Interest Lurking In My Brokerage Firm?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: delayed retirement, economic challenges, economic changes, economy, government policy, Inflation, interest rates, mortgage, mortgages, retire, retiree, retirees, Retirement, retirement accounts, retirement savings, retirement timing

Savings Base: 6 Foundational Moves That Keep Retirement Plans Stable

December 25, 2025 by Brandon Marcus Leave a Comment

Savings Base: 6 Foundational Moves That Keep Retirement Plans Stable
Image Source: Shutterstock.com

Retirement planning doesn’t have to feel like a dusty, boring lecture on spreadsheets and interest rates. In fact, it can be thrilling—like plotting the ultimate adventure where you’re both the architect and the explorer. Imagine being in full control of your financial future, where every move you make today builds a fortress for tomorrow. The key to making this journey exciting and stress-free lies in creating a solid “savings base,” a set of foundational moves that ensure your retirement plans don’t wobble, even when the economy tosses a few curveballs your way.

Let’s dive in and uncover six essential steps that make your financial future rock-solid and surprisingly fun to manage.

1. Start With A Clear Retirement Vision

The first step in building a sturdy savings base is knowing exactly what you’re aiming for. Ask yourself how you want to live, where you want to live, and what lifestyle will make your retirement truly enjoyable. Having a clear vision allows you to estimate how much money you will need and what strategies to deploy. This isn’t about daydreaming—it’s about creating a realistic, detailed roadmap that guides every financial decision you make. A vivid retirement vision keeps your motivation high, turning the abstract concept of “saving money” into a tangible, exciting goal.

2. Build An Emergency Fund First

Before diving into investments, make sure you have a safety net in place. An emergency fund acts as your financial shock absorber, keeping you from derailing your retirement plans when unexpected expenses arise. Ideally, this fund should cover three to six months of living costs, tucked safely in an easily accessible account. Having this buffer reduces stress and allows you to make long-term investment decisions without panic. Think of it as the first brick in your fortress: solid, reliable, and absolutely essential.

3. Max Out Tax-Advantaged Accounts

Tax-advantaged accounts like 401(k)s, IRAs, and Roth IRAs are not just a financial cliché—they’re a supercharged way to grow your savings faster. Contributions often reduce your taxable income now or let your investments grow tax-free, depending on the account type. Maxing out these accounts may feel challenging, but even incremental increases over time add up to impressive long-term gains. The magic of compound interest works best in these vehicles, turning small, consistent contributions into a powerful wealth-building engine. Think of these accounts as your secret weapon in the quest for retirement security.

4. Diversify Investments Wisely

Putting all your eggs in one basket is a recipe for stress and instability. A diversified portfolio—mixing stocks, bonds, real estate, and even alternative assets—helps reduce risk and smooth out market volatility. Diversification doesn’t mean overcomplicating; it means smartly balancing growth and security. The goal is to ensure your investments work together, protecting your savings even when one sector falters. A well-diversified portfolio acts like a shock-resistant foundation, giving your retirement plan stability and peace of mind.

5. Control Debt Aggressively

Debt is a sneaky enemy of retirement security, quietly eroding your ability to save and invest. High-interest debt, like credit cards, should be prioritized and eliminated as fast as possible. Mortgage and student loans require strategic planning, but even these should be managed carefully to avoid long-term financial strain. Reducing debt frees up more money for investments and gives you psychological freedom, too. Think of paying off debt as reinforcing the beams of your financial fortress—every dollar reduced strengthens the structure of your future.

6. Review And Adjust Regularly

No plan is perfect forever; life changes, markets fluctuate, and priorities shift. Regularly reviewing your retirement plan ensures you’re on track and able to adapt to new circumstances. Quarterly or annual check-ins allow you to rebalance investments, adjust contributions, and correct course before small issues turn into big problems. This proactive approach keeps your savings base dynamic, not stagnant, and ensures you’re always in control. Treat these check-ins like tuning a high-performance engine—small tweaks now prevent breakdowns later.

Savings Base: 6 Foundational Moves That Keep Retirement Plans Stable
Image Source: Shutterstock.com

Take Charge Of Your Retirement Stability

Building a stable retirement plan isn’t just a matter of luck—it’s about intentional, consistent actions that protect and grow your savings. By creating a clear vision, securing an emergency fund, maximizing tax-advantaged accounts, diversifying investments, managing debt, and reviewing progress regularly, you give your financial future the stability it deserves. Every step you take today builds confidence, security, and flexibility for tomorrow.

Your retirement can be exciting, secure, and full of possibilities when you commit to these foundational moves. Readers, tell us your experiences, successes, or lessons learned in the comments section below.

You May Also Like…

Savings Sprint: 9 Ways to Catch Up on Retirement Savings Before December Ends

Savings Sprint: 9 Ways to Catch Up on Retirement Savings Before December Ends

Asset Migration: 5 Emerging Market Trends Retirees Should Know Before January

Debt Overhang: 8 Ways Carrying Debt Into Retirement Can Undermine Your Progress

Is Your Retirement Timeline Still Safe If The Market Drops Again Before New Year’s Eve?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: 401(k), diversification, diversify, IRAs, retire, retiree, retirees, Retirement, retirement account, retirement plan, retirement savings, Roth IRAs, savings account

  • « Previous Page
  • 1
  • …
  • 5
  • 6
  • 7
  • 8
  • 9
  • …
  • 13
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework