• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for home buying

Here’s What is Cost To Buy A Home in 2000

May 17, 2025 by Travis Campbell Leave a Comment

hand holding key against house background
Image Source: 123rf.com

Buying a home is one of the biggest financial decisions most people will ever make. But have you ever wondered what buying a home in 2000 actually cost? Whether you’re a first-time buyer, a seasoned homeowner, or just curious about how the real estate market has changed, understanding the cost to buy a home in 2000 can offer a valuable perspective. It’s not just about nostalgia—comparing past and present home prices can help you make smarter decisions today. It’s fascinating to see how much the market has shifted in just a few decades. Let’s take a trip down memory lane and break down what it really cost to buy a home in 2000, and what that means for you now.

1. The National Median Home Price in 2000

Back in 2000, the national median home price was about $119,600, according to the U.S. Census Bureau. That number might sound shockingly low compared to today’s prices, but it’s important to remember that wages, interest rates, and the overall economy were very different. The cost of buying a home in 2000 was much more accessible for many families, especially when compared to the rapid price increases seen in the years since. This figure is a great starting point if you’re comparing your current home search to what your parents or older siblings experienced.

2. Mortgage Rates Made a Big Difference

Interest rates played a considerable role in the cost of buying a home in 2000. At the start of the millennium, the average 30-year fixed mortgage rate hovered around 8%. While that’s higher than the historic lows we’ve seen in recent years, it was actually considered reasonable at the time. Higher rates meant higher monthly payments, even lower home prices. For example, a $120,000 mortgage at 8% interest would result in a monthly payment of about $880 (excluding taxes and insurance). Understanding how mortgage rates impact affordability is crucial, whether you’re looking back or planning your next move.

3. Down Payments and Loan Options

In 2000, the standard down payment was typically 20%, though some buyers qualified for FHA loans with as little as 3% down. A typical buyer must save around $24,000 for a median-priced home. The cost to buy a home in 2000 wasn’t just about the sticker price but also about how much cash you needed upfront. While there were fewer low-down-payment options than today, programs for first-time buyers were becoming more common. If you’re saving for a home now, it’s helpful to know that buyers in 2000 faced similar challenges when scraping together a down payment.

4. Closing Costs and Other Fees

Beyond the purchase price and down payment, buyers in 2000 also had to budget for closing costs. These typically ranged from 2% to 5% of the home’s price, covering things like loan origination fees, title insurance, and inspections. A $120,000 home meant an additional $2,400 to $6,000 out of pocket. The cost to buy a home in 2000 included these “hidden” expenses, which often caught first-time buyers by surprise. Today, closing costs remain a significant part of the home-buying process, so planning for them early is wise.

5. Regional Price Differences

Like today, the cost of buying a home in 2000 varied widely depending on where you lived. Home prices in the Midwest and South were often well below the national median, sometimes under $100,000. Meanwhile, buyers in places like California or the Northeast faced much steeper prices, with some markets already pushing past $200,000 for a modest home. These regional differences highlight why it’s important to look beyond national averages and consider your local market when considering affordability.

6. The Impact of Inflation

It’s easy to look at the cost to buy a home in 2000 and feel a pang of envy, but don’t forget about inflation. Adjusted for inflation, that $119,600 median price is roughly equivalent to about $210,000 in today’s dollars. While homes were still more affordable by many measures, the gap isn’t quite as dramatic as it first appears. This perspective can help you set realistic expectations and appreciate the long-term value of real estate as an investment.

7. Wages and Affordability

One of the most important factors in the cost of buying a home in 2000 was how much people earned. The median household income in 2000 was about $42,000. That means the typical home costs about 2.8 times the average annual income. By comparison, today’s home prices are often five or six times the median income, making affordability a much bigger challenge. If you’re feeling squeezed by today’s market, you’re not alone—wages simply haven’t kept pace with rising home prices.

8. What You Got for Your Money

Homes built or bought in 2000 were often smaller and had fewer amenities than many new builds today. The average new home was about 2,000 square feet, with three bedrooms and two bathrooms. The cost to buy a home in 2000 got you a comfortable, functional space, but not necessarily the open floor plans, granite countertops, or smart home features that are common now. If you’re house hunting today, it’s worth considering what features matter most to you and where you might be willing to compromise.

Looking Back to Move Forward

Reflecting on the cost to buy a home in 2000 isn’t just an exercise in nostalgia—it’s a powerful reminder of how much the housing market has changed, and how important it is to plan carefully. While prices have risen and affordability has become more challenging, understanding the past can help you make smarter decisions for your future. Whether you’re saving for your first home or thinking about moving up, knowing what it cost to buy a home in 2000 can inspire you to set realistic goals and stay focused on what matters most.

How does your experience compare to the cost of buying a home in 2000? Share your thoughts or stories in the comments below!

Read More

8 Hidden Costs of Buying a Home

How Much House Can I Afford? Use This House Affordability Calculator

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Real Estate Tagged With: affordability, first-time buyers, home buying, Housing Market, Inflation, mortgage rates, real estate history

12 Ways to Buy A Million Dollar House Even With A Modest Budget

May 15, 2025 by Travis Campbell Leave a Comment

mansion
Image Source: pexels.com

Are you dreaming of living in a million dollar house but feel like your budget is holding you back? You’re not alone. With soaring real estate prices, the idea of owning a luxury home can seem out of reach for many. But what if there were creative, practical ways to make that dream a reality—even if you don’t have a seven-figure bank account? The good news is, there are! Whether you’re a first-time buyer or looking to upgrade, these strategies can help you unlock the doors to a million dollar house without breaking the bank. Let’s dive into twelve actionable ways you can make it happen.

1. Expand Your Search to Up-and-Coming Neighborhoods

One of the smartest ways to buy a million dollar house on a modest budget is to look beyond the most popular zip codes. Up-and-coming neighborhoods often offer luxury homes at a fraction of the price you’d pay in established areas. Property values can rise quickly as these neighborhoods grow, turning your purchase into a savvy investment. Keep an eye on local development plans, new businesses, and infrastructure improvements—these are often signs a neighborhood is on the rise.

2. Consider a Fixer-Upper

Buying a fixer-upper can be a golden ticket to owning a million dollar house for less. Homes that need some TLC are typically priced lower, giving you the chance to build equity as you renovate. You can transform a dated property into your dream home with a clear vision and a solid renovation plan. Just be sure to budget for repairs and consult with contractors before making an offer.

3. Pool Resources with Family or Friends

Co-buying with trusted family members or friends is becoming more common, especially in high-cost markets. By pooling your resources, you can afford a larger down payment and qualify for a bigger mortgage, making a million dollar house more attainable. Ensure a clear legal agreement is in place to outline ownership shares and responsibilities.

4. Leverage Low Down Payment Loan Programs

You don’t always need a 20% down payment to buy a million dollar house. Many lenders offer low down payment options, especially for first-time buyers. Programs like FHA, VA, and certain conventional loans can help you get into a high-value home with as little as 3-5% down.

5. House Hack Your Way In

House hacking means buying a multi-unit property, living in one unit, and renting out the others. The rental income can help cover your mortgage, making it easier to afford a million dollar house. This strategy works especially well in markets where duplexes, triplexes, or homes with accessory dwelling units are available.

6. Negotiate Seller Concessions

Don’t be afraid to negotiate! In a buyer’s market, sellers may be willing to cover closing costs, pay for repairs, or even lower the price. These concessions can free up cash for your down payment or renovations, making a million dollar house more accessible.

7. Look for Off-Market Deals

Some of the best deals never hit the MLS. Off-market properties—sometimes called “pocket listings”—are homes for sale that aren’t publicly advertised. Working with a well-connected real estate agent can help you find these hidden opportunities and potentially score a million dollar house below market value.

8. Explore Creative Financing Options

Creative financing can open doors that traditional mortgages can’t. Options like seller financing, lease-to-own agreements, or assumable mortgages can help you buy a million dollar house with less cash up front. Each option has pros and cons, so consult a financial advisor to see what fits your situation.

9. Maximize Your Credit Score

A higher credit score can unlock better mortgage rates and terms, saving you thousands over the life of your loan. Before shopping for a million dollar house, check your credit report, pay down debts, and avoid taking on new loans. Even a small boost in your score can make a big difference in your buying power.

10. Invest in Pre-Construction or New Developments

Buying a home before it’s built—known as pre-construction—can offer significant savings. Developers often offer lower prices and incentives to early buyers. While there’s some risk involved, getting in early can help you secure a million dollar house at a discount before prices rise.

11. Downsize Your Expectations (Temporarily)

If your budget is tight, consider buying a smaller million dollar house or one with fewer amenities. Focus on location and potential for future upgrades. As your finances improve, you can renovate or expand, turning your starter luxury home into your forever dream house.

12. Build Sweat Equity

If you’re handy, doing some of the renovation work yourself can save thousands. From painting to landscaping, sweat equity can help you afford a million dollar house by reducing labor costs. Just be realistic about your skills and time commitment.

Turning Dreams Into Reality: Your Path to a Million Dollar House

Buying a million dollar house with a modest budget isn’t just a fantasy—it’s a goal within reach if you’re willing to think creatively and act strategically. You can unlock doors you never thought possible by exploring alternative neighborhoods, leveraging unique financing options, and being open to fixer-uppers or co-buying. Remember, the journey to your dream home is as important as the destination. With patience, research, and a willingness to try new approaches, your million dollar house could be closer than you think.

What strategies have you considered or tried to buy a million dollar house? Share your thoughts and experiences in the comments below!

Read More

5 Ways to Save Up to Buy a House

8 Hidden Costs of Buying a Home

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Real Estate Tagged With: budgeting, first-time buyers, home buying, investing, million dollar house, Mortgage Tips, Personal Finance, Real estate

Here’s What it Cost To Buy A Home in 2025

May 13, 2025 by Travis Campbell Leave a Comment

Miniature house on old book with house key in girl hand over blurred tropical beach background, property and real estate investment business, house insurance
Image Source: 123rf.com

Buying a home has always been a significant milestone—and a major financial commitment. But in 2025, the landscape for homebuyers has shifted in ways that might surprise you. Whether you’re a first-time buyer, a seasoned investor, or just curious about the current market, understanding what it really costs to buy a home in 2025 is essential. With interest rates, home prices, and even the types of homes people buy all changing, it’s more important than ever to know what you’re getting into. Let’s break down the real costs, the hidden fees, and the smart moves you can make to get the most for your money. If you’re considering moving this year, this guide is for you.

1. The National Median Home Price in 2025

The first thing most buyers want to know is: what’s the average price of a home right now? In 2025, the national median home price will have reached approximately $420,000, according to the latest National Association of Realtors data. This is a significant jump from just a few years ago, reflecting both inflation and ongoing demand in many markets. While some regions—like the Midwest—still offer homes below the national median, hot markets on the coasts and in major cities are seeing prices well above $600,000. If you’re house hunting, it’s crucial to research your local market and set realistic expectations for your budget.

2. Mortgage Rates: Higher, But Not Sky-High

Mortgage rates have been a rollercoaster over the past few years. In 2025, the average 30-year fixed mortgage rate hovers around 6.5%. While this is higher than the historic lows of the early 2020s, it’s not as high as some feared. The difference in rates can mean hundreds of dollars more (or less) in your monthly payment, so it pays to shop around. Consider locking in your rate if you find a good deal, and don’t forget to factor in points, lender fees, and closing costs when comparing offers.

3. Down Payments: What’s Expected in 2025?

The traditional 20% down payment is still the gold standard, but in 2025, many buyers are putting down less. The average down payment for first-time buyers is now closer to 8-10%, thanks to various loan programs and assistance options. However, putting down less than 20% usually means paying for private mortgage insurance (PMI), which can add $100 or more to your monthly bill. If you can save up for a larger down payment, you’ll lower your monthly costs and improve your chances of getting a better mortgage rate.

4. Closing Costs: The Hidden Price Tag

It’s easy to focus on the sticker price of a home, but don’t forget about closing costs. In 2025, buyers can expect to pay between 2% and 5% of the home’s purchase price in closing costs. On a $420,000 home, that’s $8,400 to $21,000. These costs include loan origination fees, title insurance, appraisal, and taxes. Some buyers can negotiate with sellers to cover part of these costs, but in a competitive market, you may need to budget for the full amount yourself.

5. Homeowners’ Insurance and Property Taxes

Once you own your home, the costs don’t stop. Homeowners’ insurance and property taxes are ongoing expenses that vary widely depending on where you live. In 2025, the average annual homeowners insurance premium is about $1,500, but it can be much higher in areas prone to natural disasters. Property taxes also range from less than 1% to over 2% of your home’s value each year. Research these costs in your area and factor them into your monthly budget.

6. Maintenance and Repairs: The Unseen Expenses

Every homeowner knows that maintenance and repairs are part of the deal. Experts recommend budgeting at least 1% of your home’s value annually for upkeep. For a $420,000 home, that’s $4,200 annually. This covers everything from routine maintenance like HVAC servicing to unexpected repairs like a leaky roof. Setting aside a home maintenance fund can help you avoid financial surprises.

7. The Impact of Location and Lifestyle

Where you buy matters just as much as what you buy. In 2025, urban homes tend to cost more but may offer savings on commuting and amenities. Suburban and rural areas often have lower home prices but may come with higher transportation costs or fewer services. When choosing a location, consider your lifestyle, work situation, and long-term plans. Sometimes, paying a bit more for a home in a walkable neighborhood or near public transit can save you money (and stress) in the long run.

8. New Construction vs. Existing Homes

In 2025, new construction homes are more popular than ever but often come with a premium price tag. The average new home costs about 10-15% more than a comparable existing home. However, new builds may offer energy efficiency, lower maintenance costs, and modern amenities that can save you money over time. When deciding between new and existing homes, weigh the upfront cost against potential long-term savings.

9. First-Time Buyer Programs and Assistance

Don’t overlook the many programs designed to help first-time buyers. In 2025, there are more options than ever, from down payment assistance grants to special loan programs with lower interest rates. Check with your state or local housing authority, and explore federal options like FHA, VA, or USDA loans. These programs can make homeownership more accessible, especially if you’re struggling to save for a down payment or qualify for a conventional loan.

Making Your Move in 2025: Smart Strategies for Today’s Homebuyers

Buying a home in 2025 is a big investment, but with the right information and a clear plan, it’s absolutely achievable. Start by understanding the true cost to buy a home in 2025, from the purchase price to the hidden fees and ongoing expenses. Shop around for the best mortgage rates, explore assistance programs, and don’t be afraid to negotiate. Most importantly, choose a home and a location that fit your lifestyle and long-term goals. The market may be challenging, but with preparation and flexibility, you can find a home that works for you without breaking the bank.

What’s your experience with buying a home in 2025? Share your story or tips in the comments below!

Read More

8 Hidden Costs of Buying a Home

How Much House Can I Afford? Use This House Affordability Calculator

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Real Estate Tagged With: 2025 housing market, first-time buyers, home buying, homeownership, mortgage rates, Personal Finance, Real estate

6 Ways HOA’s Get You Trapped Into Their Outrageous Fees

May 12, 2025 by Travis Campbell Leave a Comment

Apartment building with covered entrances against cloudy sky on a winter day
Image Source: 123rf.com

If you’ve ever dreamed of living in a picture-perfect neighborhood, you’ve probably considered a home in a community governed by a Homeowners Association (HOA). On the surface, HOAs promise manicured lawns, sparkling pools, and a sense of order. But behind those white picket fences, many homeowners discover a different reality: a maze of rules and, more alarmingly, a web of outrageous fees. These fees can sneak up on you, drain your wallet, and leave you feeling powerless. Understanding how HOAs operate—and how they can trap you financially—is crucial for anyone considering buying into an HOA community. Let’s pull back the curtain and explore the six sneaky ways HOAs get you stuck with their fees, so you can protect your hard-earned money and make smarter decisions.

1. Mandatory Membership and Non-Negotiable Dues

When you buy a home in an HOA community, membership isn’t optional—it’s a requirement. This means you’re automatically on the hook for monthly or annual dues, regardless of whether you use the amenities or agree with the board’s decisions. These fees can increase yearly, often outpacing inflation, and you have little say. According to the Foundation for Community Association Research, the average monthly HOA fee in the U.S. is about $250, but it can soar much higher in some areas. Before you sign on the dotted line, make sure you understand exactly what you’re committing to and how much those dues could rise over time.

2. Special Assessments That Hit When You Least Expect

You might not be prepared for special assessments even if you budget for regular HOA dues. These are one-time fees levied when the HOA needs extra cash for big projects—think roof replacements, pool repairs, or unexpected legal battles. Special assessments can run into the thousands, and you’re legally obligated to pay them. Many homeowners are blindsided by these charges, especially if the HOA hasn’t managed its reserve funds well. Always ask for the HOA’s financial statements and reserve study before buying to gauge the likelihood of future assessments.

3. Hidden Fees for Everyday Activities

HOAs are notorious for tacking on extra fees for things you might assume are included. Want to rent the clubhouse for a birthday party? There’s a fee. Need a parking permit for a guest? That’ll cost you. Some HOAs even charge for pool keys, mailbox replacements, or using the tennis courts. These hidden fees can add up quickly and catch new homeowners off guard. Review the HOA’s fee schedule carefully and ask current residents about any surprise charges they’ve encountered.

4. Fines for Rule Violations—Big and Small

One of the most frustrating ways HOAs get you trapped is through fines for breaking community rules, no matter how minor. Did you forget to bring in your trash can by 10 a.m.? That could be a $50 fine. Paint your front door the wrong shade of blue? Another fine. These penalties can escalate if not paid promptly, sometimes leading to legal action or even a lien on your property. According to Nolo, HOAs have broad authority to enforce rules and collect fines, so reading the community’s covenants, conditions, and restrictions (CC&Rs) before moving in is essential.

5. Legal Fees Passed Directly to Homeowners

If you ever find yourself in a dispute with your HOA—whether over a landscaping issue or a contested fine—you could be responsible for the association’s legal fees, not just your own. Many HOA agreements include clauses that allow the board to recover legal costs from homeowners, even if the dispute is minor. This can quickly turn a small disagreement into a financial nightmare. Before buying, review the HOA’s governing documents for legal fee provisions and consider consulting a real estate attorney to understand your risks.

6. Escalating Fees with Little Oversight

HOA boards are typically made up of volunteers, and while many are well-intentioned, some lack the financial expertise to manage large budgets. This can lead to poor decision-making, mismanagement of funds, and, ultimately, higher fees for everyone. Sometimes, boards may hire expensive management companies or contractors without proper oversight, passing those costs directly to homeowners. Attend HOA meetings, review budgets, and get involved in board elections to help keep your fees in check.

Don’t Let HOA Fees Catch You Off Guard

Living in an HOA community can offer perks, but going in with your eyes wide open is vital. Outrageous HOA fees can quickly make your dream home a financial burden if you’re not careful. The best defense is doing your homework: read all documents, ask tough questions, and talk to current residents. Remember, it’s tough to get out of these obligations once you’re in. By understanding how HOAs operate and where their fees come from, you can make a more informed decision and avoid getting trapped.

Have you ever been surprised by an HOA fee or assessment? Share your story or advice in the comments below!

Read More

15 Mistakes You’re Making Destroying Your Home’s Value

Home Insurance: The Smart Way to Protect Your Home and Finances

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Real Estate Tagged With: HOA fees, HOA fines, home buying, homeowners association, Personal Finance, Real estate, special assessments

5 Things that Can Happen If You Buy A Home WIth A Solar Lease

May 12, 2025 by Travis Campbell Leave a Comment

solar panels on home
Image Source: unsplash.com

Buying a home is one of the biggest financial decisions you’ll ever make, and every detail matters—including whether the house comes with a solar lease. As solar panels become more popular, more homes on the market have existing solar leases attached. While lower energy bills and a greener lifestyle are appealing, a solar lease can introduce unexpected twists to your home buying journey. If you’re not careful, you could end up with more complications than you bargained for. Understanding the ins and outs of a solar lease is essential before you sign on the dotted line.

So, what exactly can happen if you buy a home with a solar lease? Let’s break down the five most important things you need to know, so you can make a confident, informed decision.

1. You May Inherit the Solar Lease—And Its Terms

When you buy a home with a solar lease, you’re not just getting the house—you’re also taking on the existing solar lease agreement. This means you’ll be responsible for the monthly payments, maintenance obligations, and any other terms set by the solar company. Unlike owning solar panels outright, a solar lease is a long-term contract, often lasting 15 to 25 years. Before you fall in love with that sun-powered home, ask the seller for a copy of the solar lease and read it carefully. Look for details about payment amounts, annual escalator clauses (which can increase your payments each year), and what happens if you want to buy out the lease early.

It’s also wise to check if the solar lease is transferable and whether the solar company requires a credit check or approval process for new homeowners. Some buyers have been caught off guard by strict transfer requirements or hidden fees. Understanding the lease terms is crucial to avoid surprises down the road.

2. Selling the Home Later Can Get Complicated

A solar lease can make selling your home more challenging. Potential buyers may hesitate to take on a lease they didn’t negotiate, especially if the terms aren’t favorable or the payments are high. Some buyers may even walk away from the deal if they’re uncomfortable with the solar lease, limiting your pool of interested buyers and potentially lowering your home’s resale value.

If you plan to sell in the future, be prepared to explain the benefits and obligations of the solar lease to prospective buyers. You might need to offer incentives, such as covering a portion of the remaining lease payments or negotiating with the solar company to transfer the lease smoothly. According to Consumer Reports, homes with solar leases can take longer to sell compared to those with owned solar panels.

3. Your Mortgage Approval Could Be Affected

Did you know that a solar lease can impact your ability to get a mortgage? Some lenders view solar leases as additional debt, which can affect your debt-to-income ratio and, in some cases, your loan approval. The lease payments may be factored into your monthly obligations, potentially reducing the amount you can borrow or even disqualifying you from certain loan programs.

It’s important to talk to your lender early in the process and provide them with all the details about the solar lease. Some lenders are more familiar with solar leases than others, so working with a mortgage professional who understands these agreements can make a big difference. If you’re using a government-backed loan, such as an FHA or VA loan, be aware that there may be additional requirements for homes with solar leases. The Federal Housing Administration has specific guidelines for properties with leased solar panels, so ensure you comply before moving forward.

4. You Might Not Get All the Energy Savings You Expect

One of the main reasons people are drawn to homes with solar panels is the promise of lower energy bills. However, the savings aren’t always as significant as you might hope with a solar lease. Lease payments can sometimes offset much of the energy savings, especially if the lease includes annual payment increases. Additionally, if your household’s energy usage is lower than the system’s output, you may not fully benefit from the solar power generated.

Reviewing the home’s past utility bills and comparing them to the solar lease payments is a good idea. Ask the seller for at least a year’s worth of energy statements to get a clear picture of the actual savings. Remember, the solar lease company’s projections may be optimistic, so rely on real numbers whenever possible. If you’re hoping to maximize your energy savings, consider whether buying a home with a solar lease is the best option for your financial goals.

5. Maintenance and Repairs May Not Be Your Responsibility—But Read the Fine Print

One potential advantage of a solar lease is that the solar company typically handles maintenance and repairs. This can save you time, money, and hassle if something goes wrong with the system. However, reading the lease carefully is important to understand exactly what’s covered. Some leases include comprehensive maintenance, while others may have exclusions or require you to pay for certain repairs.

If a storm or other event damages the solar panels, find out whether your homeowner’s insurance or the solar company is responsible for repairs. Clarify who pays for removal and reinstallation if you need to replace your roof. Knowing these details upfront can help you avoid unexpected costs and keep your home running smoothly.

Making a Smart Move with a Solar Lease

Buying a home with a solar lease isn’t necessarily a bad idea, but it does require extra diligence and a clear understanding of what you’re signing up for. You can decide whether it fits your financial goals and lifestyle by carefully reviewing the lease terms, talking to your lender, and weighing the pros and cons. Remember, a solar lease can offer benefits like predictable energy costs and professional maintenance, but it can also introduce selling, financing, and actual savings complications. The key is to go in with your eyes wide open and ask plenty of questions.

Have you ever bought or sold a home with a solar lease? Share your experiences or questions in the comments below!

Read More

First Time Home Buyer? Here’s Your Guide to the Home Loan Process

8 Hidden Costs of Buying a Home

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Real Estate Tagged With: energy savings, home buying, homeownership, mortgages, Personal Finance, Real estate, solar lease, solar panels

8 Cities Where a Buyer Can Still Get a Great Deal on a Home

March 28, 2025 by Latrice Perez Leave a Comment

Confident realtor showing house for sale to newlywed young couple, outside
Image Source: 123rf.com

In today’s fluctuating real estate market, finding affordable housing can be challenging. However, several cities in the United States continue to offer excellent opportunities for buyers seeking value without sacrificing quality of life. This article explores eight cities that provide affordable home options alongside vibrant communities and promising economic growth. Whether you are a first-time homebuyer or looking to relocate, these markets offer a blend of affordability and livability. Read on to discover where you might find your ideal home at a great price.

1. Pittsburgh, Pennsylvania

Pittsburgh stands out as a city where a large percentage of home listings are affordable. Its average home value remains well below national averages, making it a prime target for budget-conscious buyers. The city boasts a rich cultural scene, robust job market, and strong community ties. These factors combine to create a highly attractive environment for homeownership. Pittsburgh’s blend of affordability and quality of life makes it a top contender for buyers seeking value.

2. St. Louis, Missouri

St. Louis offers a diverse housing market with many affordable options available. The city’s historical charm and vibrant neighborhoods add to its appeal. Economic stability and a range of recreational activities contribute to its overall attractiveness for buyers. Affordable housing in St. Louis makes it an ideal location for those looking to invest in property without overspending. Its accessibility and community spirit further enhance its real estate market.

3. Buffalo, New York

Buffalo presents buyers with attractive home prices and a market that remains accessible despite economic challenges. The city is known for its rich history and cultural heritage, which contribute to a unique living experience. Proximity to natural attractions like Niagara Falls adds recreational value. Buffalo’s affordable real estate, combined with its community-oriented atmosphere, makes it an excellent option for buyers. The potential for growth in the region continues to draw in savvy homebuyers.

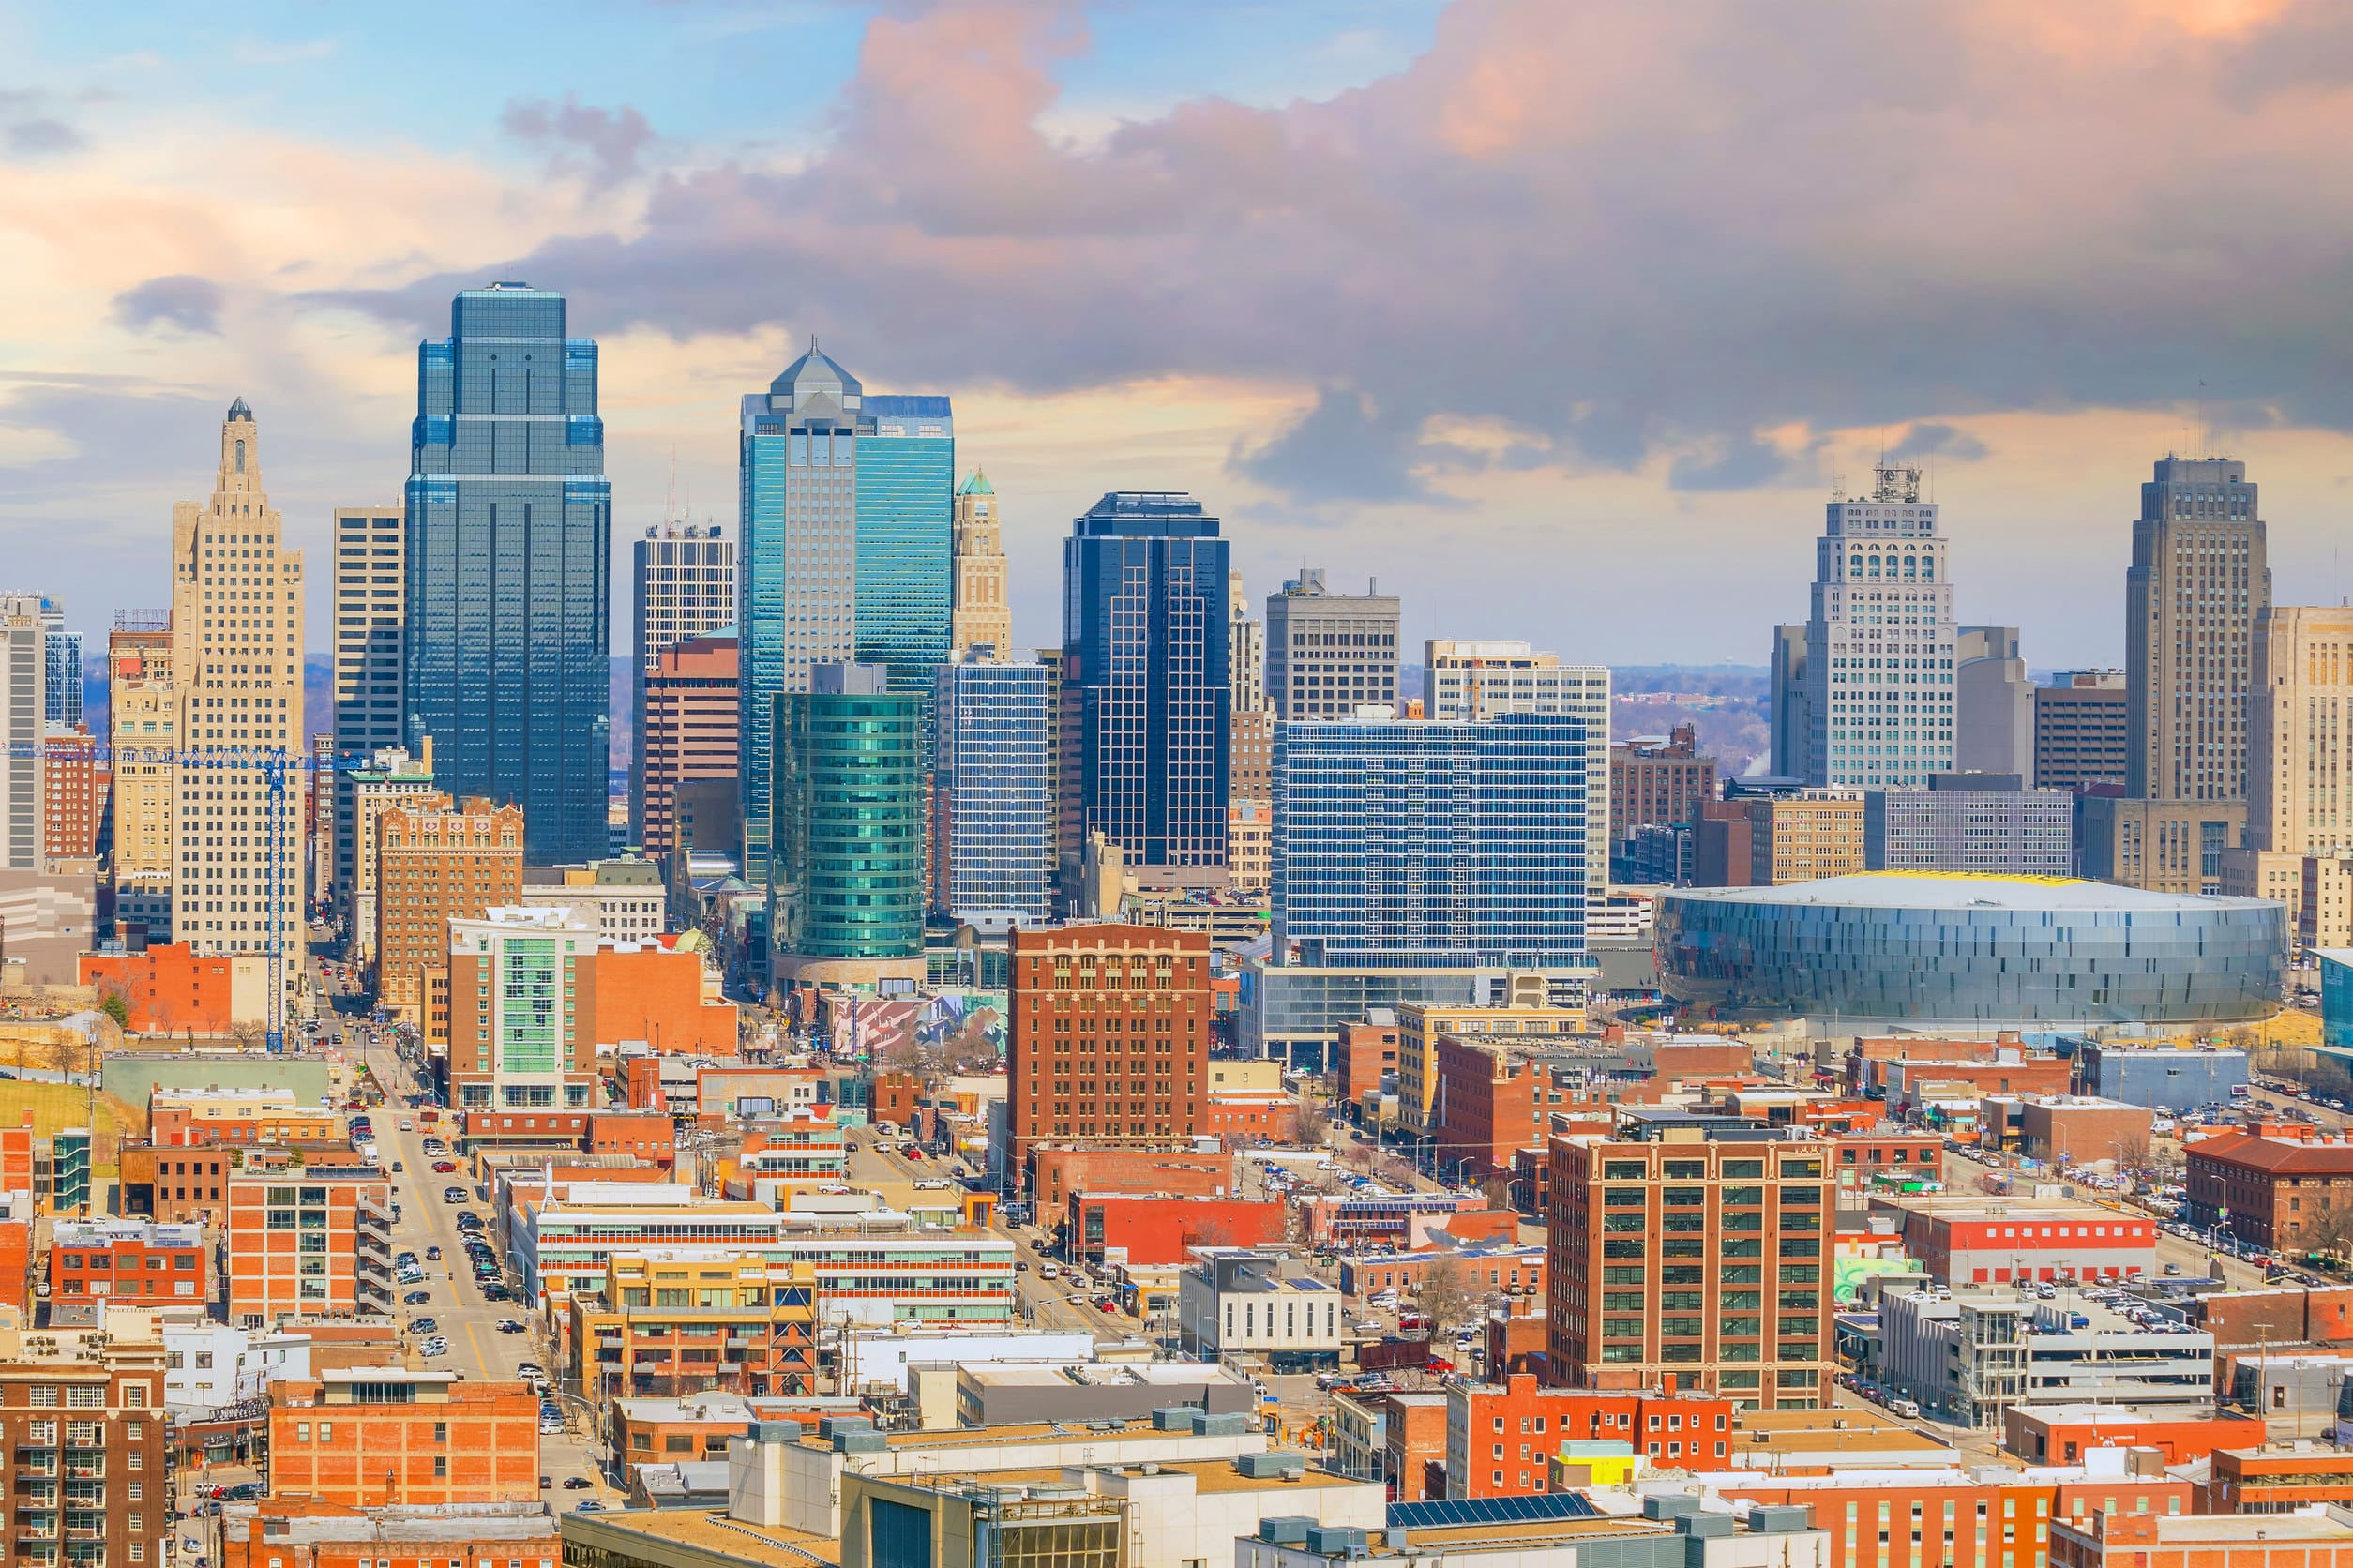
4. Kansas City, Kansas

Kansas City
Image Source: 123rf.com

Kansas City, Kansas offers a blend of urban and suburban living with affordable housing options. The city’s median home prices remain competitive, attracting buyers looking for both value and a strong job market. Its cultural attractions and community events add to its overall livability. The balance between affordability and quality of life makes Kansas City an appealing destination for homeownership. This city continues to draw attention from buyers seeking a well-rounded living environment.

5. Cleveland, Ohio

Cleveland is recognized for its low cost of living and accessible real estate market. Home values in Cleveland are notably affordable, offering a range of options for various budgets. The city’s diverse neighborhoods and rich history provide a unique living experience. A strong sense of community and local amenities further enhance its appeal to buyers. Cleveland’s affordability and quality of life make it a standout choice in the housing market.

6. Detroit, Michigan

Detroit has been experiencing a resurgence, with revitalized neighborhoods and a growing arts scene. The city offers affordable home prices that attract both investors and first-time buyers. Detroit’s evolving market presents opportunities for significant growth and future value appreciation. The combination of affordability and potential makes Detroit an exciting prospect for homebuyers. Its transformation continues to foster a promising environment for property investment.

7. Champaign, Illinois

Champaign, home to the University of Illinois, offers a vibrant community with affordable housing options. The presence of a major educational institution contributes to cultural and economic vitality. Home prices in Champaign remain accessible, making it attractive to young professionals and families alike. The city’s blend of affordability, education, and community spirit creates a compelling case for homeownership. Its consistent demand and quality of life further solidify its position as a buyer-friendly market.

8. Peoria, Illinois

Peoria features one of the most cost-effective housing markets, with median home values that appeal to budget-conscious buyers. The city offers a mix of urban and suburban living, providing a balanced lifestyle. A strong sense of community and local amenities contribute to its overall attractiveness. Peoria’s affordability makes it an excellent option for those looking to invest in real estate without breaking the bank. Its economic stability and community vibe continue to make it a solid choice for homebuyers.

Affordable Housing Opportunities

While the national real estate market may seem daunting, these eight cities demonstrate that affordable homeownership is still within reach. Each city offers its unique blend of affordability, amenities, and quality of life. Buyers can find great deals without compromising on essential features that enhance daily living. Exploring these markets might just lead you to the home of your dreams at a price that fits your budget.

Are you considering purchasing a home in one of these cities? Share your thoughts and experiences in the comments below!

Read More:

Forget Traditional Home Ownership: 12 Alternative Housing Options That Can Give You Real Financial Freedom

9 U.S. Cities Falling Apart Faster Than You Think

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Real Estate Tagged With: affordable housing, city living, home buying, Housing Market, property investment, real estate deals

  • « Previous Page
  • 1
  • 2
  • 3
  • 4

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework