• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.

5 Great Ways to Make Your Tax Refund Work for You

April 17, 2017 by Emilie Burke Leave a Comment

Tax season is wrapping up, and if you’re expecting a nice refund check to hit your bank account any day, you’ll need a plan for how to use it so you don’t waste it away. If the thought of that extra money coming your way is already burning a hole in your pocket, you may want to think about using it in a way that will be financially beneficial to you instead.


Let your money work for you. What does your current financial situation look like?  Can your refund check offer you a little more security? Here are some basic financial priorities that you may want to consider using your refund for.

Pay Off Those High-Interest Loans and Credit Cards

If you’re trying to work yourself out of debt, your tax refund can help you reduce or eliminate your high-interest debt that’s costing you more. Use your refund to pay off any loans or credit cards with a low balance.  Or, consolidate high-interest accounts and put your refund towards any transfer or early payoff fees to help eliminate paying more in interest.  Take a look at your high-interest student loans, car loans, or credit card debt and determine the best way to pay these down or pay them off completely.

Start An Emergency Fund

If you don’t already have a healthy emergency fund, now is the time to start.  If you do have one, but the balance isn’t as high as you’d like, your refund check can give it a healthy boost.  If you don’t have an emergency fund, you’re just one unexpected expense away from getting in debt. You should have at least six to eight months’ worth of your salary set aside. Saving that much can take months if you’re only able to set aside a little bit each month, but your refund can help you to quickly build that fund and provide some peace of mind.

Refinance or Make Improvements

If a lower interest rate is available it will help lower your monthly mortgage payment, but refinancing has closing costs and other fees associated with it.  Using your refund to refinance your home will save you money each month on your mortgage; money that can be better spent on something else.

If you have a good mortgage rate already, take a look at your house. Does your air conditioning system need to be replaced? Maybe energy-efficient appliances will help you pay less in utility bills. Making improvements around your home can significantly increase its value and make it more comfortable to live in.

Buy Life Insurance

When you’re young, you tend to feel pretty confident that there’s always going to be time to take care of the ones you love.  Life insurance is usually overlooked. But if you’re married and you have a family or you’re planning one, a term life policy will offer them protection should the unthinkable happen to you. For a few hundred dollars, your tax refund can make sure your family is protected.

Spend It On Something You Need

Is your car in need of repair? Have you been putting off a visit to the doctor’s office? Let your refund help you get these essentials taken care of.

Why spend all of your refund on things you don’t really need when you can use it to save you money and give you peace of mind?

Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: budget tips

How much diversification is too much diversification?

April 10, 2017 by Emilie Burke Leave a Comment

We have all heard financial investors preach on the importance of having a diversified portfolio. Not only does this maximize our profit, but it also protects us from risk by having more than one type of stock. Diversification is important to our success in the investment world. However, how much diversification is too much? How many stocks do you need to own before you are adequately diversified and is there a magical number? There comes a point where your portfolio can become over-diversified. It is important to find and maintain a healthy balance of diversity.

Pinterest graphic over ocean waves: "How Much Diversification Is Too Much Diversification?"

What is Diversification and Why is It Important?

Diversification occurs when investors intentionally own stocks in different companies, industries and geographic locations. They are intentional about this in order to reduce their risks within the market. If one industry or location struggles, there is still balance and growth overall in their stocks and investments. They are protected.

This is important because the investor will have a healthier and more profitable experience. When one stock struggles, the others may thrive. This will help protect them from major drops in the market.

If you have ever heard the saying, “Don’t put all your eggs in one basket,” then you will have a better understanding of this theory.

The investor is choosing to have more than one basket, so that if one gets dropped, he doesn’t lose all of his profits. He is choosing not to depend on one stock or company for all of his success.

However, sometimes too much diversification can hurt you rather than help.

So…

What is the Magic Number?

According to the Modern Portfolio Theory, or MPT, your portfolio achieves maximum diversity when your purchase your 20th stock.  The MPT found, after strenuous research, that you can only eliminate your risk so much before it begins to plateau. This plateau typically occurs after your stocks add up to the sum of twenty.

However, remember that the number 20 is not magical on its own. Owning twenty stocks will not automatically give your optimal diversity and maximum profit alone. Instead, your 20 stocks must be diverse and well-chosen. They should come from different locations, industries and sectors. Twenty stocks from the same company will not give you the diversity that you are aiming for.

What About Mutual Funds?

Although mutual funds can be safe and profitable, they will not necessarily give you optimal diversification. Although the fund may invest in many different companies, many funds are still sector specific. Although you may be diversified in a particular sector, you do not have diversification across the board when it comes to different industries. If you are looking for something more diverse across the board, look into owning a balanced fund. They own stocks across the entire market.

When owning a mutual fund, it also can be a dangerous way to fall into over-diversification. Many large mutual funds own hundreds of different stocks, and therefore, so do you. Be sure to research what your mutual fund owns and keep tabs on how diverse it is.


Diversification is vital, but only to a certain extent. Be smart and vigilant when deciding where to invest your money. Find the happy balance that you are looking for.


Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: Investing

Two Ways to Automate Your Savings

April 3, 2017 by Emilie Burke Leave a Comment


If you struggle saving money, or hate having to take the time and brainpower to save each week, automated savings apps have the potential to rock your world.

The apps are designed with the user in mind, making saving money so easy that you do not have to do a single thing. Saving is transformed from an impossible goal to a mindless everyday occurrence.

Pinterest graphic over a pile of coins: "Two Ways to Automate Your Savings"

Digit

Digit is a savings app that links to your banking account to put aside money for you. Their slogan is “Save money, without thinking about it.”

Digit has become increasingly popular with younger generations and with individuals who struggle to save. Rather than having to decide whether you want to save or splurge at the end of the month, extra money is taken out in small increments throughout the month.

Digit is the perfect friend for heavy spenders; the app is able to track your spending habits and monitor your income. Then, they occasionally pull aside money (never large sums) that you will not need for your routine expenses. Typically, this removal happens once or twice a week. It is never so frequent that it will affect your budget. The money is then kept in the app in a savings account. The app is able to send out text updates so that you are aware each time saving occurs.

If you need quick access to the savings, a short text to digit can have the money back into your account within one business day. No harm done! They have a no overdraft guarantee, your money is insured, and there is no need to set up a new savings account when you sign up.

You’re probably wondering… “So how much is this going to cost me?”

Digit is completely free, and a great tool for getting a jump start on your savings. Although you don’t receive interest, Digit is now doing something called cash bonuses, which is basically the same thing.

Right now, Digit is only US based, and is not available with all banking institutions (although it is with many). If you do not have much money, you will not save as much, but it doesn’t hurt to give it a shot!

Acorns

Acorns is another automated savings app that works by rounding up all your transactions to the nearest dollar. It puts all the spare change into investments for you. They help you pick which portfolio you are putting your money into, and instead of hoarding your savings, you begin to invest.

Acorns is all automatic, virtually pain-free and easy, and has no transaction fees. It allows you to make money off of your money. Acorns is perfect for beginners who know little about investing; you do little, and they take care of the hard work!

However, Acorns charges a monthly fee: $1.00 per month for accounts under $5,000, and 0.25% per year for accounts over $5,000. Students and individuals under the age of 24 can have these fees waived.

As with any investment, there is always the chance of losing money, rather than making.


Give one of these two automated savings apps a try and reap the benefits. Saving money no longer has to be difficult and painful. Slow down your spending habits, better your finances and put away savings.

It is way too easy to spend money when it is just sitting around in our checking account. Take control of the situation and do not leave it there tempting you.

Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: money management

Do robo-advisors do better than humans?

March 27, 2017 by Emilie Burke Leave a Comment

Robo-advisors  are completely automated systems online that help you to invest your money. Robots, if you will. They are becoming increasingly popular with the younger generations, specifically those with less investment experience. Younger individuals getting their feet wet in the investment industry are turning to robo-advisors for all their financial advice.

You tell the robo-advisors what is important to you, and they do all the tough calculations. (Don’t worry, they’re using solid logarithms and criteria.) Many give general investment advice, and others help you plan for your retirement and reach other specific financial goals.

Pinterest graphic over a keyboard: "Do Roboadvisors Do Better Than Humans?"

Although at first I was very skeptical of roboadvisors, I have tried one, Betterment, and found it to be extremely beneficial for me- a girl who initially had very little financial knowledge. They have minimal fees, and give you the flexibility that many investors need. You don’t have to be investment-savvy, and are still able to profit greatly from your investments. It is fairly safe and fool-proof.

However, due to the automation of them, roboadvisors are less unique and personalized. Every single individual is unique, with specific goals and situational differences. It is hard to explain all of that to a computer. Life is complicated; not everything is cut and dry… So, are roboadvisors better than humans who give investment advice?

That answer depends majorly on your individual situation. If the automation’s cookie-cutter approach is not ideal for you, a human interaction may be more beneficial. Humans are able to give you one on one advice, and sit down and listen to your concerns.

However, robo-advisors arguably can save you significant sums of money. Let’s discuss some specific situations, and which advisement technique would be best to use.

When to Use a Robo-Advisor:

  • When you don’t need direct contact and one-on-one interaction. If you’re comfortable with the computer screen, this is a perfect fit for you.
  • When you want to save money. Fees are generally much lower with roboadvisors than with human advisors.
  • When traditional investment advisors have high requirements. If you cannot find a human advisor who does not require steep minimum requirements, try a robo-advisor.
  • When you want to be less in control, and have someone else take care of things for you. If you are looking for a hands-off approach, here it is.

When to Use a Traditional Advisor:

  • If you prefer face-to-face interactions and one on one contact, robo-advisors are not the way to go.
  • If you prefer to not do everything online, including money transactions, then you need to sit down with a traditional advisor. For older generations who are not familiar with technology, robo-advisors may be much more difficult to operate.
  • When you disagree with your robo-advisor, or find that it is not fully benefiting your unique financial situation, switch to a traditional advisor.
  • Lastly, use a human advisor when you want to be more hands-on with your investments. You can be the one in control.

Decide which option is the best fit for you. If you cannot decide, give robo-advisors a chance. You can always go back to the traditional route. Regardless, keep investing. Your future will be brighter.

Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: Investing

Blue Apron Company Profile and Review

March 17, 2017 by Emilie Burke 1 Comment

Blue Apron is a meal delivery service that delivers fresh ingredients for three or your ordered number of meals to your door. Their motto is “Food is better when you start from scratch.” I think we would all agree!

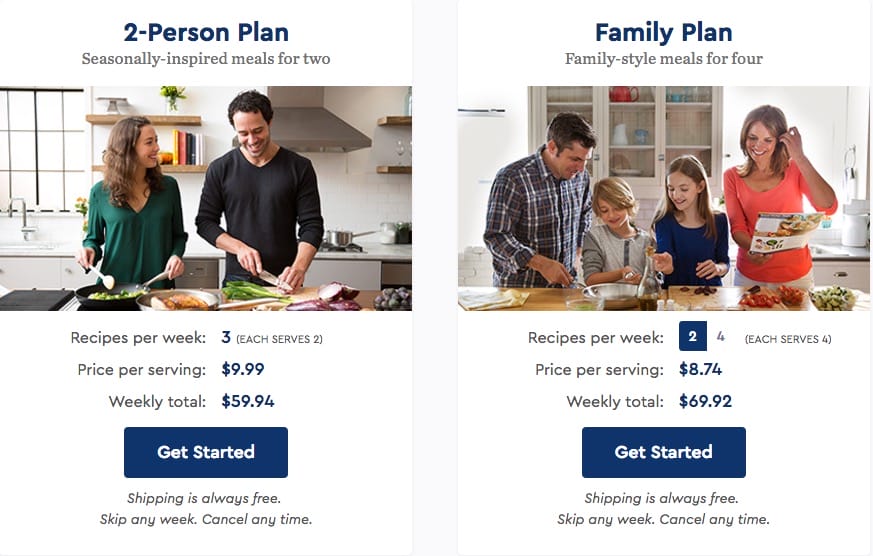
Food quality makes a huge difference in the meals we eat. While preparing food from scratch can sound appealing, it can be time consuming. Especially in households with two working members, it can seem almost impossible. Blue Apron fills a market need. For slightly more than regular groceries, as low as $8.57 per serving according to their website, they provide a premium meal experience at a less-than-premium price.

Blue Apron was founded in 2012. Since its founding, the company has raised roughly 194 million dollars, with its most recent rounding being a $135 million Series D raised in June 2015. Some estimates say the company has between 500 and 1000 employees with its 3 founders still holding C-level executive positions. They have been featured in The Wall Street Journal, Good Morning America, Tech Crunch, and The Washington Post, as well as many others.

blue apron company profile and review

Blue Apron allows you to see what the price-per-serving cost of a meal is. This allows you to compare the price for Blue Apron to your groceries. Thing is, though, that Blue Apron can’t be compared to your groceries. You see, groceries are just food, but Blue Apron is a service!

You’re not only getting all the ingredients you need to make dinner, but you’re also getting the lack of a hassle- less groceries to worry about and less mind space to let dinner take up. Blue Apron, though, is not like going out to eat. You still have to do the cooking and the cleaning yourself.

The cost of Blue Apron reflects its middle ground between between going out to eat and just making a “regular” meal at home. The price, at $8.74 to $9.99 per meal, reflects that middle ground. It’s cheaper than $16/meal at some restaurants but nicer than the $4/meal you’re probably managing with your groceries when you make some dinner.

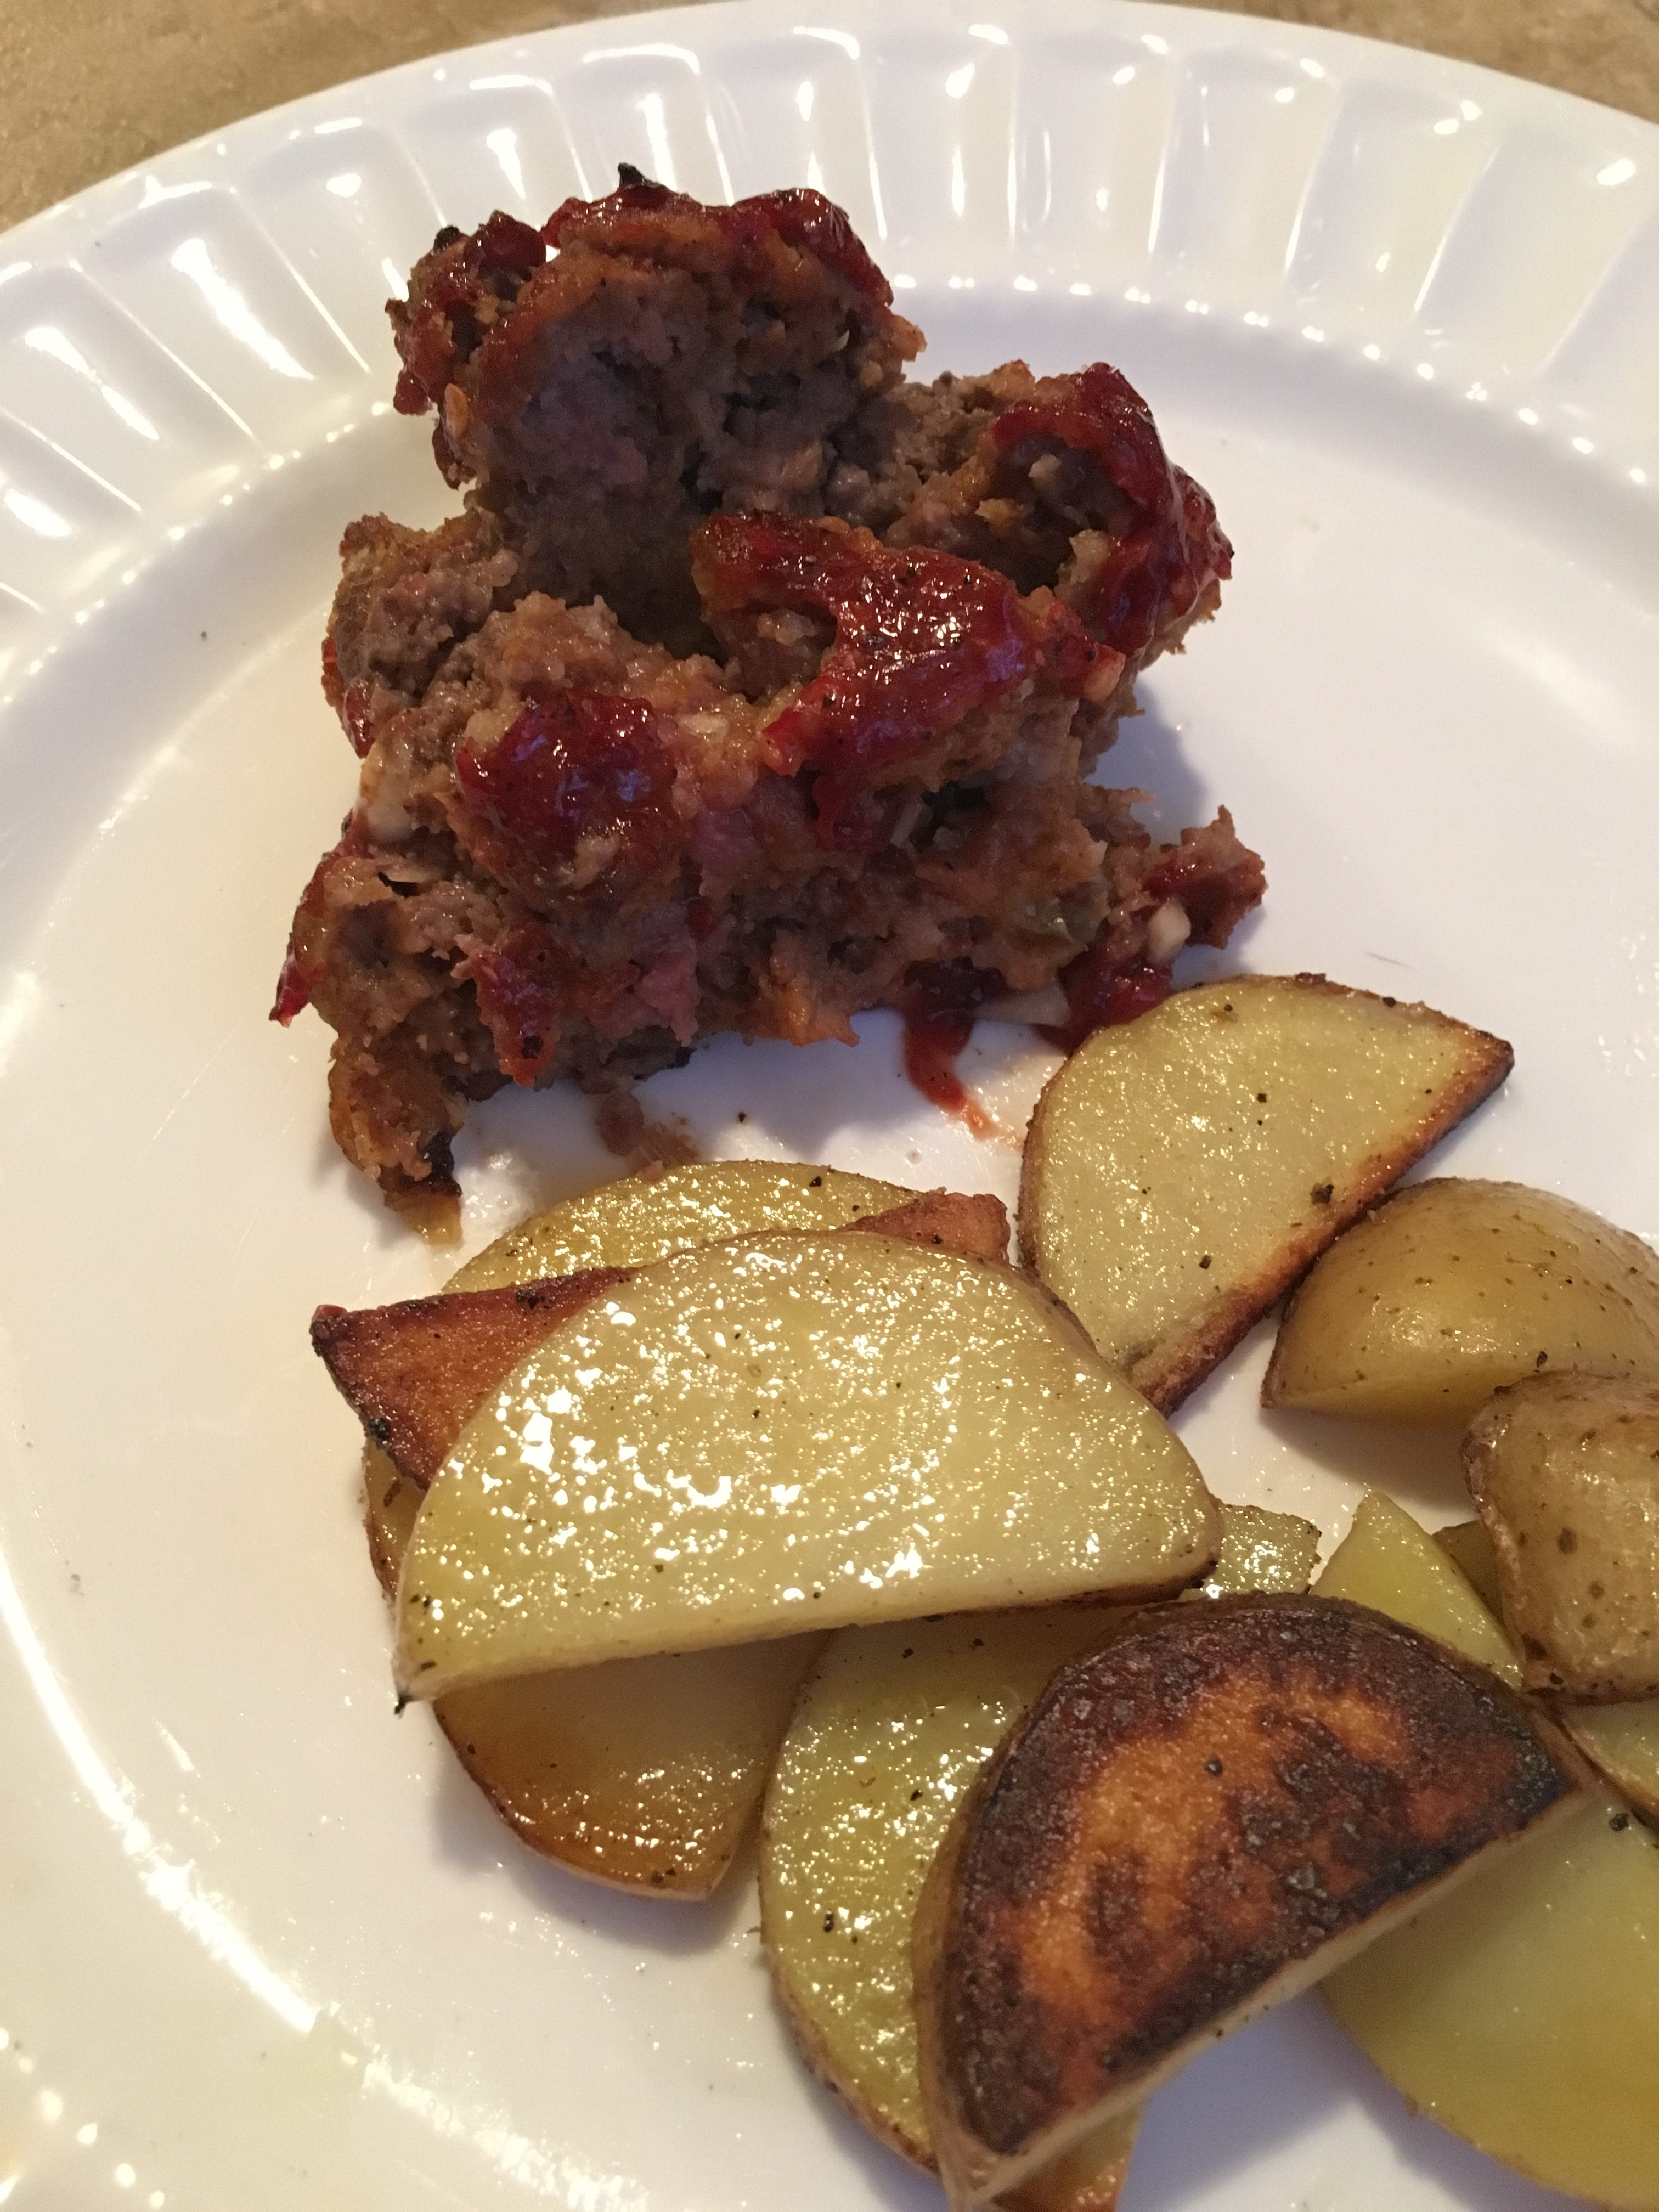
Plate of glazed meatloaf with roasted potato wedges

I got the chance to try Blue Apron myself! One of the three meals we tried was a Chipotle-Glazed Meatloaf with Crispy Potatoes. My significant other, Casey and I decided to make a Saturday date-night experience out of it. We were hoping it would fill that middle ground – a nice date night but one that didn’t require spending what going out to dinner. Casey enjoys cooking, but I’m not great at it. As a result, I don’t particularly enjoy it. Our Blue Apron date night let us spend time together in a great way, doing something Casey loved, and that supported our financial goals.

The following Sunday, Casey had to work the whole day. I prepared for us our second meal – Oaxaca Cheese and Plantain Tortas with Tangelo & Radish Salad. I was shocked by the prep time for this meal – nearly an hour – but it had less than 10 minutes of cook time. As a result, I was able to bring Casey a delicious meal and we got to share a not-so-picnic-lunch sitting in Casey’s office.

Blue Apron is a company growing in popularity, which is why you may have already heard of it. The company is set up for success and it has found product-market fix. You can see how it meets a need in real people’s lives. It meets a need in my life. That really says something.

You can try Blue Apron yourself and get $30 off your first order with this link.

Tell me more: Have you ever tried Blue Apron or another meal delivery service? 

I obtained free meals in exchange for reviewing Blue Apron. All thoughts and opinions are my own.

More Blue Apron reviews:

  • Cleverdude
  • Thousandaire
  • Budget and Invest
Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: money management

Paribus Review: Is it Free Money?

March 8, 2017 by Emilie Burke Leave a Comment


Paribus Review

There are a plethora of “free money” apps out there that feel like a scam. If you’ve gone looking for a Paribus Review, you know that isn’t the case with them. Paribus differentiates itself from so many of the other apps for one simple reason.

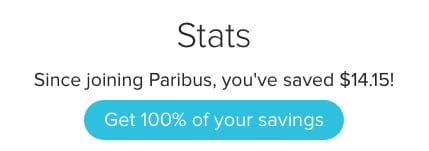
Paribus app stats screen: "Since joining Paribus, you've saved $14.15!" with a Get 100% of your savings button

Yes! The differentiator here is that I have actually gotten money back through Paribus. I know, for a fact, that this app works. Now that that’s out of the way, we can dig into the app.

An Honest Paribus Review

You set up Paribus by giving it permission to connect to your email address. This is how it tracks your purchases made around the web! As previously mentioned, they work with select merchants, but those merchants cover a wide variety of products. I do 99% of all my online shopping at Amazon, but if you’re not like me, you’re likely still covered. You can also connect your Paribus account to your credit cards to cover your bases entirely and make sure you are always getting the best price.

How It Works

You sit back and relax. Paribus looks at your purchases and uses bots to check prices on the things you’ve bought to see if the price drops. If it does, they work to get you money back. If not… well, you bought it anyway! If Paribus finds you money back, you will receive a message. Paribus does not collect any commission from your refund. Signing up with this link will get you started.

Here’s an example:

Sally buys shoes from an online retailer for $48. Paribus watches the price and it drops to $24. The difference: $24. Instead of $48 on those shoes, your net expenses are $24. As an added bonus, you get all this money back without have to do any extra work since Paribus does that for you!

More About Paribus

Paribus is not a scam. Like I said, I have made money with them. But, I also did some background research for this Paribus Review. Here is what I found…

The app was initially developed in 2014 as the brainchild of two Harvard guys – Karim Atiyeh and Eric Glyman. The software pretty much only runs on iOS, but there are plans to expand it to other operating systems. It is also owned by Capital One, so Paribus is a legit app run by a major banking corporation.

My Take? – Found Money

One thing that differentiates Paribus from similarly “found money” apps is that it requires no work from you. No tedious surveys that pay 10 cents per word. This is an app that actually works, costs you nothing and can help you bring in extra money at no additional work or cost to you. You have nothing to lose!

This post was sponsored by Paribus. 

Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: budget tips

Where to get good free financial advice?

February 20, 2017 by Emilie Burke Leave a Comment

If you are looking for financial advice, you probably don’t have money just lying around to be spent.  There’s a lot you can do before you shell out for a financial advisor! So, how can you get that advice for free? Here are five different websites with excellent financial advice available at no cost.

Pinterest graphic of a woman on the phone at a laptop: "Where to Get Good Free Financial Advice?"

Rockstar Finance

Subscribe to Rockstar Finance to get your feet wet in a little of everything financial. Rockstar Finance has a great blog, a list of money saving challenges to consider, book reviews on great financial reads, and a whole slew of reviews and information on financial apps and services. Whatever you are looking for, they probably have right on their website free of cost.

How Do I Money

Check out this awesome finance website for great blogs, podcasts, books and more. One thing that makes them unique is their video series on Budgeting; definitely worth giving a watch. How Do I Money also offers four money spreadsheets on their site that help with budgeting, dealing with debt, saving money and more. These sheets are a great tool for those trying to get a better handle on their finances. Print them off and use them each month as you budget.

Making Sense of Cents

If you want to make sense of money, this is the blog for you! Michelle has a consistent blog that covers a wide variety of topics: saving money, making extra income, paying off debt, and tips for traveling. She loves to travel, and gives expansive advice on how to do that while sticking to your budget. If you have struggled in the past with your personal finances, this blog has plenty of tips explaining what you could be doing wrong and how to turn things around. Check out 15 Reasons You’re Broke and Can’t Save Money for a personal favorite of mine.

Stefanie O’Connell

Stefanie is an expert on helping millennials become personal finance professionals. Her blog and videos are interesting and informative, covering topics such as “Three Mental Roadblocks to Making More Money” and “3 Ways to Earn a Pay Raise.” If you’re a millennial looking to achieve financial greatness and to be money savvy, she’s the gal for you!

Burke Does

I may be slightly biased, but Emilie Burke has some great financial advice. (Yep, that’s me.) My website offers tons of free advice that will help you get your budget on track and find better ways to save money. Burke Does is a lifestyle blog that specializes in personal finances and millennial struggles. I write about the balance between overcoming debt, staying healthy and enjoying life along the way. Check out my latest blog, Knowing Your Why When Paying Down Debt, to discover the importance of knowing your motivation while freeing your life from the weight of debt.

Bonus Tip

Pinterest has tons of resources for financial advice. A little searching can lead you to endless financial tips and tricks to help you save money and budget well.

Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.

Filed Under: Uncategorized

Mutual Funds: The Pros and the Cons

January 30, 2017 by Emilie Burke Leave a Comment

First thing first: What is a Mutual Fund?

A mutual fund is a strategy for investing that allows you to pool your money together with others to purchase a collection of stocks, bonds, or other securities. Typically, the fund is purchasing something that might be difficult or impossible for you to purchase on your own.

Pinterest graphic over a notebook and pen: "Mutual Funds: The Pros & The Cons"

The collection of holdings that the fund, or company, purchases is called its portfolio. As an investor, you own a share of the fund. However, you do not own any of the portfolio. This is different; the individual stocks do not belong to you.

Now… let’s talk about some pros and cons of mutual funds.

Pros:

  1. Mutual funds are convenient: You are doing a lot less of the research and work. Others do the “thinking,” and you are there to make money.
  2. Mutual funds are diverse: By coming together with other investors, you are able to hold an assortment of holdings that you would be unable to purchase on your own. You are no longer limited by your own finances, and your personal opportunities soar.
  1. The funds are professionally managed: Typically, there are a couple of professional managers and also a team of researchers leading the fund. People much more qualified and experienced are calling the shots.
  1. They are fool-proof: By joining a mutual fund, you have the opportunity to invest any amount of money with very little experience or investing history. You don’t have to continually decide which stocks will be a good investment. After joining, you are able to sit back and relax.

Cons:

  1. Mutual funds charge fees: Mutual funds are expensive to run, and therefore investors are often hit with high fees. There are often annual rates and sales commissions included in the funds.
  1. Share prices are only calculated once a day: Unlike single stocks, you cannot check price changes of a mutual fund throughout the day. The price completely depends on the fund’s net asset value (NAV), which is determined by all the different holdings within the fund. This is only calculated once each day.
  1. Shareholders are distributed Capital Gains: By law, mutual funds must distribute capital gains to investors. No matter how long you have been a part of the fund, the distributions are still taxed at the long-term rate. With single stocks, taxes on capital gains do not have to be paid until after you sell the stock and thus make profit. In mutual funds, you also have to pay taxes every single year on the fund’s capital gains.
  1. Phantom Gains: Bummer alert- this is a pretty big con. In a mutual fund, you can actually lose money on an investment, but still owe taxes. Talk about back-tracking… This is common when mutual funds are doing poorly, and investors decide to sell. The fund may in return have to sell profitable investments in order to raise money to pay off the investors leaving. This creates capital gains, which are then distributed to all the investors.
Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: Investing

Five 401K Alternatives You Need to Know About

January 23, 2017 by Emilie Burke 1 Comment

A 401K is a savings plan for retirement that is sponsored by your employer. Employees can save a piece of their paycheck before taxes are taken out, and put it toward their retirement.

Talking about far-off retirement plans can be overwhelming and boring. After all, it’s way easier to think about the here-and-now. We budget, save for vacation and pay the bills. That seems like enough… right?

On the contrary, planning for retirement is incredibly vital and cannot be forgotten or overlooked.

Pinterest graphic with a calculator and paper clips: "5 401K Alternatives You Need to Know About"

The 401K may be a good fit for your lifestyle, but there can also be cons. Your employer may not be matching the money that you contribute, and also could require tenure before allowing you to withdraw. If you aren’t sure about the 401K, there are many different options out there to consider.

Here are some alternatives to the typical 401K that may compliment your lifestyle and finances better.

  1. Index Funds- These are funds invested on an index of stocks. (You may have heard of S&P 500 or the Dow.) By investing in an index fund, you basically are investing in all the companies that make up that particular index (instead of investing in certain stocks). You are at the same risk as those who buy stock individually, but since the market typically increases over time, index funds could be used as an investing option for retirement.
  1. Roth IRAs and Traditional IRAs- IRA stands for Individual Retirement Account. Roth and Traditional IRAs differ from the 401K by bypassing the employer altogether. You save completely on your own for retirement. The biggest difference between the Roth and Traditional lies with when you pay your income taxes. Check out the two and see if one of these may be a better retirement plan for you.
  1. Simplified Employee Pension IRAs- SEP IRAs are a great option for any of you independent contractors, free-lance workers, or business owners out there. It is very similar to the Traditional IRA and could be very beneficial with your taxes. It doesn’t matter how small your business is, so definitely check it out!
  1. Variable Annuities- These are contracts between you, the investor, and an insurance company. The investor purchases a variable annuity upfront or over a period of time, and the insurance company makes periodic payments to you after retirement. However, there can be high fees and tax penalties, so do your research and insure that the contract is safe and beneficial for you.
  1. Bonds- Bonds may be great to dabble in addition to the 401K or any of the other retirement options listed above. Bonds essentially are saving accounts that pay interest rates. You set these rates at the time of purchase, and it’s an incredibly safe and stable investment. Because of its safety, they typically return less money than other higher risk investments. However, your money will be safe and making interest for retirement.

Do some research on what your employer offers and which option may be the best fit for you. Regardless of what you choose to use, saving for retirement should be a priority in your life.

Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: Retirement

Financial Habits to Set Up in 2017

January 16, 2017 by Emilie Burke 2 Comments

2017 is a brand-new opportunity to meet goals and start habits that we want to prioritize over the span of the year. Resolutions are made every year to stop smoking, eat healthy, or go to the gym. Although physical resolutions are terrific, it is also important to place focus on our financial habits as we start the new year. What type of financial goals do we have for ourselves? What habits should we form now to help us meet those goals? Here are five financial habits that will be beneficial for 2017.

Pinterest graphic over a tablet calendar: "Financial Habits to Set Up in 2017"

Budgeting

Create weekly and monthly budgeting plans, and take time afterwards to review how well you are sticking to the budget. When you have a plan in place, it is much easier to save money and spend less. Reviewing how you are doing regularly will help you to evaluate where you are financially and what you should change.

Setting financial goals

Set some goals that are important to you and be vigilant in sticking to them. One goal may be to create an emergency savings fund of $2,000. Another may be to stay under budget for 6 months in a row. Whatever your goals are, write them down so that you can hold yourself accountable.

Avoiding debt

One of the greatest habits you can keep is to never create debt for yourself. This means always living beneath your means, and NEVER above. Can you create this habit for yourself for 2017? If so, you will be a happier you with healthier finances.

Contributing to retirement

Create a Roth or Traditional IRA and make it a habit each paycheck to contribute into the fund. It is never too early to start preparing for retirement. The sooner you start, the more money you will have saved up when the day comes.

Giving (some people may call this Tithing)

Make it a financial habit this year to give to others. This may come in the form of giving to a particular charity, tithing at church, or donating money to a cause you believe in. When we give to others, we are blessed in return. If allowed the opportunity, giving may do even more good in your life than you ever could have imagined.

Think of whatever habits are important to you financially this year and write them down! Writing down what we want is so important because only then can we continually hold ourselves accountable. Hang your list on the fridge or sit it by your bed. Every day make it a priority to continue these habits in your life.

If you think these 5 habits listed above could be beneficial to your own personal finances, then I encourage you to truly try to stick to them over the next 12 months. It is the small things that you do every day that bring about big change in your life. Healthy habits create healthy finances, and that’s the goal that we all should be aiming to reach. Good luck!

For more on forming habits, and ways to get rid of bad ones, check out these great articles.

5 Habits That Cost You Thousands
Increase Your Financial Stability by Taking Advantage of New Spending Habits
Sandy Smith Talks Gen Y Money Habits


Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: money management, Planning

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • 5
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework