• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Personal Finance

What You Should Know About Taking A Postgraduate Course In Financial Planning

April 8, 2024 by Susan Paige Leave a Comment

Are you considering taking a postgraduate course in financial planning and want to know what will be covered? Maybe you want to learn about financial planning but are concerned about the assessments on a postgraduate course? Whatever brought you here, we have the answers for you! 

Today, we have a brief guide that outlines what you should know about taking a postgraduate course in financial planning, preparing you for the course before it begins. 

What Is Financial Planning?

Financial planning involves examining a business’s finances and offering advice on how it can achieve its financial goals. Both short-term and long-term financial goals are considered here, and financial plans are revised when needed depending on the business’s success and any changes in the market. 

Financial planning is often offered as part of business management courses, but you can specialise entirely in financial planning, especially at a postgraduate level. These courses are taught at postgraduate levels, including graduate certificates, diplomas, and master’s degrees. The course level, along with entry requirements, will be stated on the course so you can see which is best suited to you. 

What Do Postgraduate Courses In Financial Planning Cover?

Courses in financial planning cover various topics that will allow you to progress in your career as a financial planner or better understand your business’s finances. Typically, postgraduate financial planning courses will cover the following topics: 

  • Risk management and estate planning 
  • Taxation laws 
  • Business consulting 
  • Accounting and financial management 
  • Corporate finance 
  • Art and practice of leadership
  • Behavioural finance for financial advisers
  • Financial plan construction and client management 
  • Professionalism and ethics 

A postgraduate financial planning course aims to provide you with the knowledge and skills to begin or progress in your career in financial planning with a holistic view of the requirements of accredited financial planners. The courses will help you understand how financial planners can work with small businesses, big corporations, the taxation laws they must follow, and how to manage clients as a self-employed financial planner. 

Some courses offer additional modules that will allow you to specialise as a financial planner. These include topics like retirement and wealth planning, commercial law, and cash flow maintenance. When choosing the right course for you, check the course catalogue to see what modules and units are offered to ensure they will help you achieve your goals. 

How Will I Learn On A Postgraduate Financial Planning Course?

How you learn in a postgraduate financial planning course varies depending on your chosen course. Most financial planning courses are taught through a mixture of lectures, workshops, and seminars. These will involve independent and group work, allowing you to gain knowledge about topics and apply it to case studies and questions provided by the course leader. 

Some financial planning courses are taught online, focusing more on independent work. You will be given access to lectures and all your reading materials to work through at your own pace. There might also be collaborative sessions where you can work with other students, ask course leaders questions, and receive feedback. 

When applying for your postgraduate financial planning course, check the catalogue to see how the course runs. Here, you will find out how long the course takes, how many hours of classes you will attend weekly, and how many hours of independent study you are expected to complete. 

How Will I Be Assessed On A Postgraduate Financial Planning Course?

Assessments on postgraduate financial planning courses vary depending on the course you choose. Typically, exams, essays, and case studies are used to assess your knowledge and understanding. These will be spread across your course, usually after you complete a module. In-person courses sometimes feature group projects or presentations as part of your assessments.

Online postgraduate financial planning courses focus on independent assessments. Depending on how the course runs, there might be essays, reports, or case studies at the end of each unit. You might also be asked to give individual presentations or complete small exams to prove you have understood the knowledge and can apply it to real-life situations. 

Most course catalogues tell you what types of assessments are included in each course.

Final Thoughts 

A postgraduate course in financial planning is an excellent stepping stone, whether you are looking to change careers or embark on a new one. The course will cover the basics of financial planning and offer real-life situations where you can put your knowledge to the test, helping you become the best financial planner possible. 

Filed Under: Personal Finance

15 Things Smart People Only Leave to Charity in Their Wills

April 8, 2024 by Teri Monroe Leave a Comment

writing will

While it is most common to make charitable donations throughout your lifetime, smart people understand the benefits of leaving contributions to charity in their will. Writing charities in your will not only feels altruistic and may ensure your legacy, but there are also significant tax benefits for the estate and your heirs.

Charitable bequests, whether assets or items, are typically deductible from the estate’s taxable income, reducing the overall tax burden. While many people leave financial donations to charity in their will, many other surprising things can be left to charity. Here are 15 things smart people only leave to charity in their will.

1. Money and Financial Assets

donating to charity in will

Cash, stocks, bonds, or other financial assets are commonly bequeathed to charitable organizations to support their missions and programs. When leaving stocks and bonds to charity in your will, you can allocate all or some of the assets to the charity of your choice.

2. Real Estate

Donating home to charity

Property such as houses, land, or commercial buildings can be left to charities to use directly or sell for funding their activities. Leaving your home to charity can also lessen the burden on children if they do not wish to keep your house.

3. Artwork

donating art charity will

Valuable paintings, sculptures, or other artwork may be donated to museums or arts organizations to enrich cultural heritage and support the arts. However, not all museums will accept your art, so planning is necessary.

When the museum receives your collection, your estate will receive a tax deduction based on the collection’s current valuation.

4. Season Tickets

donate season tickets

Many charitable organizations use ticket donations to raise money for their organizations through silent auctions. Leaving your season tickets to your favorite charity could put them to good use.

5. Vehicles

donating vehicle charity will

Cars, boats, or other vehicles can be donated to charitable organizations, which may use them for their operations or sell them to raise funds. Most people wouldn’t consider leaving a car to charity, but many organizations like Cars for Kids run their entire charity on car donations.

6. Jewelry

donating jewelry charity will

Donating jewelry to charity can be beneficial not just for its monetary value, but in some cases for its historical significance. If your fine jewelry is antique, you may consider donating it to a museum.

7. Collections

stamp collection donated in will

Whether it’s stamps, coins, books, or other collectibles, individuals sometimes leave their collections to charities that can benefit from them, such as libraries or historical societies.

8. Personal Property

donating furniture charity will

Furniture, antiques, household items, and other personal belongings may be donated to charities that support individuals in need. Organizations like Goodwill and Salvation Army will pick up furniture from your home. Donating your furniture may be especially helpful if your heirs plan to sell your home.

9. Life Insurance Policies

life insurance left to charity

Some people designate charitable organizations as beneficiaries of their life insurance policies, providing financial support to the organizations upon their passing. To do so, you must notify the charity of your choice that they are a beneficiary ahead of time. Some insurers don’t allow this, so check to see if this is possible.
10. Retirement Accounts

IRA charity

Individual Retirement Accounts (IRAs) or other retirement savings accounts can be left to charities, potentially providing tax benefits to the estate and supporting charitable causes. Donating to a charity in this way in your will is also beneficial to the charity since they don’t have to pay income tax on any of the proceeds.

11. Business Interests

business interests to charity

Entrepreneurs and business owners may leave shares of their company or other business interests to charitable organizations, contributing to causes they care about.

12. Intellectual Property

donating intellectual property charity will

Copyrights, patents, or royalties from books, music, or other creative works can be assigned to charitable organizations, benefiting them long-term.

13. Donor-Advised Funds

donor-advised fund

A donor-advised fund is an account created specifically for donations to charity. To set this up, you first irrevocably contribute assets such as cash, stock, real estate, or private business interests to the fund. Then, you and your family can make grants to your chosen charities while you’re still alive and after you die.

Assets in the fund may grow over time, making more money available for the charity of your choice. You also receive a tax write-off in the year the gift is made. A donor-advised fund is also appealing because the list of charities that benefit can be changed. According to the National Philanthropic Trust, donor-advised funds held $234.06 billion in assets in 2021.

14. Animal Assets

Pet owners may leave assets or set up trusts to ensure the care and well-being of their pets, with any remaining funds going to animal welfare charities.

15. Education Funds

educational funds will

Scholarships, grants, or educational endowments can be established in your will to support students in need or educational institutions you care about, such as your alma mater.

Benefits of Writing Charities into Your Will

donating to charity will

Leaving items to charity in your will is a meaningful and financially smart way to leave a legacy. Whether supporting humanitarian causes, advancing education and the arts, or preserving the environment, charitable bequests allow individuals to continue their philanthropic efforts beyond their lifetime. Smart people leave more than just money to charity in their wills, but instead understand the full gamut of possible donations.

Due to the complex nature of estate planning, it’s always a good idea to consult a legal professional to walk you through the best way to make charitable donations in your will.

Read More

10 Upgrades Seniors Are Making To Their Homes In Lieu Of Retirement Facilities

Do These 12 Things If You Can’t Pay Your Taxes On Time

Photograph of Teri Monroe
Teri Monroe
Teri Monroe started her career in communications working for local government and nonprofits. Today, she is a freelance finance and lifestyle writer and small business owner. Teri holds a B.A. From Elon University.  In her spare time, she loves golfing with her husband, taking her dog Milo on long walks, and playing pickleball with friends.

Filed Under: charitable giving, Personal Finance Tagged With: Charitable donation, charitable giving, Estate planning

How does the PO process actually work?

April 8, 2024 by Susan Paige Leave a Comment

The purchase order (PO) process is a cornerstone of financial and operational management within an organization, encapsulating a series of steps designed to streamline procurement while ensuring accountability and compliance. This structured process is fundamental to acquiring goods and services, laying down a clear framework that governs transactions between a buyer and a vendor. It not only establishes a legal contract for the purchase but also sets in motion a series of actions that culminate in the exchange of goods, services, and payments. Below is a detailed breakdown of the purchase order process, highlighting its significance in fostering efficient, transparent, and controlled procurement activities.

  1. Identification of Needs

The process initiates with the identification of a need within the organization, which can emerge from various departments or units. This need could be driven by inventory levels dropping below a certain threshold, the requirement for new assets, or services essential for operational continuity or project execution. Identifying the need is the first critical step in ensuring that procurement aligns with the strategic objectives and operational demands of the organization.

  1. Vendor Selection

Following the identification of needs, the next step involves selecting a suitable vendor or supplier capable of fulfilling the requirements. This selection process is pivotal, as it determines the quality, cost, and timeliness of the goods or services procured. Companies may rely on existing relationships with trusted vendors or engage in a competitive bidding process to ensure value for money. Factors such as past performance, pricing, quality of offerings, and reliability play a crucial role in this selection.

  1. Creation of the Purchase Order

Once a vendor is selected, a purchase order is created. This document is essentially an official offer to buy products or services under specified conditions. It meticulously outlines the specifics of the purchase, including descriptions of the items or services, quantities, agreed prices, delivery dates, and payment terms. The purchase order serves as a legally binding document once accepted by the vendor, establishing the terms of the transaction.

  1. Purchase Order Approval

Before dispatching the purchase order to the vendor, it typically undergoes an internal approval process. This step is essential for ensuring that the purchase is justified, aligns with budgetary allocations, and adheres to the organization’s purchasing policies. The complexity of the approval process can vary, depending on the size of the organization and the value of the purchase order, involving multiple layers of scrutiny and sign-offs.

  1. Dispatching the Purchase Order

Upon approval, the purchase order is sent to the vendor, marking a formal request for the provision of the specified goods or services. The vendor then has the option to accept, reject, or propose adjustments to the purchase order. Acceptance of the purchase order by the vendor confirms the agreement and obligates the vendor to fulfill the order as specified.

  1. Vendor Fulfillment

With the acceptance of the purchase order, the vendor proceeds to prepare the ordered goods for delivery or schedules the provision of services. This phase may involve the vendor providing confirmations, updates on order processing, and shipping notices to keep the buyer informed of the order status and anticipated delivery timelines.

  1. Receipt and Inspection

Upon delivery of goods or completion of services, the receiving party conducts an inspection to verify that the delivery matches the purchase order in terms of quantity, quality, and specifications. This critical step ensures that the organization receives exactly what was ordered, fulfilling the terms of the purchase agreement.

  1. Three-Way Matching

A three-way matching process is often employed, involving the comparison of the purchase order, the delivery receipt, and the vendor’s invoice. This procedure is designed to ensure that the transaction details are consistent across all documents, safeguarding against discrepancies, errors, or fraudulent activities. It serves as a check-and-balance mechanism, verifying that only goods and services received as per the agreement are paid for.

  1. Invoice Approval and Payment

Once the three-way match is confirmed, the vendor’s invoice undergoes an approval process, after which payment is processed according to the agreed-upon terms. This stage finalizes the financial transaction, with payment signifying the fulfillment of the purchase order and the completion of the procurement cycle.

  1. Record-Keeping and Analysis

Comprehensive documentation and record-keeping are maintained throughout the purchase order process with the help of a PO management software. This not only facilitates financial accounting and compliance with regulatory requirements but also provides valuable data for analyzing procurement efficiency, vendor performance, and spending patterns. Such analysis can inform future procurement strategies, aiming at cost optimization, process improvements, and enhanced supplier relationships.

The purchase order process is an integral part of organizational procurement, embodying a series of deliberate steps that ensure the controlled, efficient, and transparent acquisition of goods and services. By adhering to this process, organizations can maintain fiscal discipline, foster strong vendor relationships, and support operational needs, all while ensuring compliance and accountability. This detailed framework underscores the complexity and importance of the purchase order process in the broader context of supply chain and financial management.


Filed Under: Personal Finance

Exploring 11 Smart Strategies on How to Minimize Property Taxes

April 5, 2024 by Susan Paige Leave a Comment

Property taxes are a significant yet often overlooked aspect of real estate ownership. They can significantly affect a property owner’s financial health and warrant careful consideration and strategic planning. There are various ways to minimize your property tax burden, from local tax incentives to savvy negotiations.

Read on to learn some strategies on how to minimize property taxes.

1. Know Your Property Tax Exemptions

Many local governments offer various exemptions that can help reduce your property taxes. For example, some states provide a homestead exemption for primary residences, while others have exemptions for veterans, seniors, and low-income homeowners. You should research your area’s available exemptions to see if you qualify for any of them.

Knowing how to minimize property taxes can also involve staying abreast of changes in tax laws. Keep an eye on your local government’s website for any updates or new exemptions that may become available.
2. Challenge Your Property’s Assessed Value

Property taxes are based on the assessed value of your property, which the local government determines. However, this assessment may be inaccurate and could lead to higher taxes. It is within your right as a property owner to challenge the assessed value if you believe it is too high.

Start by researching the property values of similar homes in your area and gather evidence to support your claim for a lower assessment. You can then present this information to your local tax assessor’s office and request a reassessment.

These tax-saving techniques are essential to ensure you’re not overpaying your property taxes. It may take effort, but the potential savings make it worth it.

3. Take Advantage of Tax Incentives

One of the tips on how to minimize property taxes is to take advantage of tax incentives offered by your local government. These can be anything from tax credits for energy-efficient property to tax cuts for certain property types.

Research what tax incentives are available in your area and see if you qualify for any of them. This could help reduce your property taxes, mainly if the incentives apply over an extended period.

Reducing tax tactics can be an effective way to save on property taxes, and it’s worth learning about what options are available to you.

4. Consider Renting Out Your Property

You can deduct some of your property taxes from your rental income if you own a rental property. This could lower your taxable rental income and reduce your overall tax burden.

However, be aware that this efficient tax management may not work in all situations and can have potential tax consequences. It’s best to consult a tax professional or financial advisor before deciding to rent your property for tax purposes. Knowing how to minimize property taxes by renting your property requires proper research and planning.

5. Negotiate with Your Local Government

Another helpful tactic for minimizing property taxes is negotiating with your local government. This may involve appealing your property tax bill or requesting a payment plan if you struggle to pay the total amount.

Be prepared to present evidence and make a persuasive argument when negotiating with the authorities. They may be willing to reduce your property taxes. This can happen in cases of financial hardship or tax assessment errors. This could save you a significant amount of money in the long run.

6. Improve Energy Efficiency

Energy-efficient upgrades for your property can cut your bills. They might also lower your property taxes.

Many local governments offer tax breaks or incentives. They are for properties that meet specific energy standards. Consider installing energy-efficient windows, insulation, solar panels, or heating and cooling systems.

Before making any upgrades, research your area’s specific requirements and tax incentives to ensure you maximize your savings. This could be a win-win situation for both your wallet and the environment.

7. Regularly Review Your Tax Bill for Errors

Mistakes can happen, and your property tax bill can include errors that could lead to you paying more than necessary. Every year, carefully review your tax bill and look for any incorrect discrepancies or charges. This could include errors in property measurements, misclassification of property type, or incorrect exemption applications.

If you find any errors, contact your local tax assessor’s office promptly to have them corrected. If you need help, you can opt for a tax reduction service. They will review your tax bill and handle the appeals process on your behalf. This could potentially save you time, effort, and money.

8. Join or Form a Neighborhood Association

Sometimes, there’s strength in numbers. Join a neighborhood association. If one doesn’t exist, form one. It can be a powerful way to negotiate property taxes.

An association can represent homeowners’ interests in talks with local government. This could lead to lower taxes or assessments for the community.

This approach helps cut property taxes. It also builds community by encouraging neighbors to work together towards a common goal.

9. Take Advantage of Land Use Reductions

Certain areas offer tax reductions for properties used in specific ways that benefit the community or environment, such as land used for agriculture, conservation, or forestry. Check with your local government to see if your property qualifies for land use reductions.

This strategy can lead to significant property tax savings, especially for larger parcels of land. It also promotes the preservation of green space and sustainable land use practices.

10. Regular Updates with Your Tax Assessor

It’s essential to keep the lines of communication open with your local tax assessor’s office. By informing them of any significant changes to your property, such as demolitions, structural damages, or renovations that could affect its value, you ensure that your property’s assessed value remains accurate.

Periodic updates can prevent surprises during tax season and can be a proactive step in managing your property taxes.

11. Utilize Professional Tax Assessment Services

For property owners who are unsure about navigating the complexity of tax assessments and appeals, professional tax assessment services can be invaluable. These experts are well-versed in local tax laws and can guide you on effectively lowering your property taxes.
They can assist with filing appeals, identifying applicable tax exemptions, and ensuring your property is assessed fairly. While a cost is associated with their services, the potential tax savings can far outweigh these expenses.

Learning How to Minimize Property Taxes

Incorporating these tips into your strategy can lead to significant savings on your property taxes. With careful planning and proactive measures, you will know how to minimize property taxes and keep your financial health in check. Stay informed, take advantage of available tax incentives, and proactively manage your property’s assessed value.
Visit our website and read more.
Filed Under: Personal Finance

How to Assess Your Small Business Insurance Needs

April 5, 2024 by Susan Paige Leave a Comment

In the ever-evolving landscape of the business world, insurance stands as a beacon of security for small businesses. It serves not just as a shield against the unforeseen and inevitable risks but as a foundation for sustainable growth. The objective of this article is to illuminate the path for small business owners, guiding them through the process of meticulously evaluating their insurance needs. This guidance is crucial, particularly for those navigating the complexities of risk management for the first time. By providing a roadmap, we aim to demystify the process and empower business owners to make informed decisions. Proper insurance ensures that a single unfortunate event does not have the power to derail years of hard work and investment.

Understanding the Basics of Small Business Insurance

Navigating the realm of small business insurance begins with familiarizing oneself with the basic types of insurance policies available. General Liability Insurance, for example, offers protection against common business liabilities such as bodily injury or property damage claims. Professional Liability Insurance, on the other hand, is crucial for businesses that offer services or advice, protecting against claims of negligence or harm caused by professional services. Understanding these basics is the first step in creating a robust defense against potential threats to your business. It lays the groundwork for more specialized coverage, tailored to the specific challenges your business might face. This foundational knowledge acts as the bedrock upon which more nuanced and specific insurance decisions can be made.

Assessing Your Industry-Specific Risks

Every industry carries its own set of inherent risks. Healthcare professionals, for instance, might require malpractice insurance, while consultants could benefit from errors and omissions insurance. Identifying these risks is a critical step in safeguarding your business against potential financial pitfalls. This step requires not only a thorough analysis of your own business operations but also a keen awareness of the broader industry landscape. Engaging with industry associations and participating in relevant forums can provide deeper insights and up-to-date information on emerging risks. Awareness of these risks enables a proactive approach to insurance planning, significantly mitigating potential impacts on your business.

Evaluating Your Business Size and Operations

The scale and nature of your operations play a pivotal role in determining your insurance needs. Businesses with employees, for instance, will need to consider Workers’ Compensation Insurance and Employment Practices Liability Insurance, covering injuries on the job and employment-related claims, respectively. For businesses that operate online or handle sensitive data, Cyber Liability Insurance becomes essential. This coverage protects against data breaches and other cyber threats, which are increasingly common in today’s digital world. As your business grows or diversifies, revisiting and adjusting your insurance coverage becomes essential to ensure that new aspects of your operations are fully protected. Tailoring insurance to your business size and operations ensures that your coverage evolves in tandem with your business.

Identifying Specific Risks and Liabilities

Conducting a thorough risk assessment is foundational in pinpointing your specific insurance needs. This process involves a deep dive into all aspects of your business, from physical assets and intellectual property to potential legal liabilities. The geographic location of your business can also influence your insurance requirements. For instance, businesses in flood-prone areas might need specialized flood insurance, highlighting the role of environmental factors in risk assessment. This meticulous approach not only helps in identifying the immediate insurance needs but also prepares you for potential future challenges, ensuring that your business remains resilient in the face of adversity. An effective risk assessment provides a clear blueprint for addressing both current and future insurance requirements.

Consulting with Professionals

Navigating the complex terrain of business insurance can be daunting. This is where the expertise of insurance agents and brokers comes into play. Professionals, particularly those who specialize in small business insurance, can offer invaluable guidance in customizing your insurance portfolio. For businesses seeking streamlined and tailored insurance solutions, BizInsure offers a platform where owners can easily find and secure business insurance that aligns with their specific needs. With access to a range of policies from reputable providers, BizInsure simplifies the process of obtaining the right coverage for your business. Their guidance can be instrumental in deciphering the fine print and ensuring that your coverage meets not just current needs but also anticipates future growth and changes. Engaging with a professional can illuminate aspects of risk that may not have been previously considered, ensuring comprehensive coverage.

Conclusion

The journey of assessing your small business insurance needs is intricate, necessitating a thorough understanding of the various types of insurance, industry-specific risks, and the unique aspects of your business. Taking proactive steps to secure the right insurance coverage is not merely a precaution but a strategic investment in the future of your business. Small business owners are encouraged to embark on this process with diligence and foresight, leveraging the expertise of professionals and resources like BizInsure to navigate the complexities of business insurance. In doing so, you fortify your business against the uncertainties of tomorrow, ensuring its resilience and longevity. This proactive approach to risk management not only protects the business but also contributes to a sense of security and confidence among stakeholders, fostering a stable environment for growth and innovation. A well-considered insurance strategy is integral to the health and longevity of your business, safeguarding your hard-earned success against the unpredictable nature of business risks.

Filed Under: Personal Finance

10 Unnecessary Dental Procedures Your Dentist May Be Charging You For

April 4, 2024 by Tamila McDonald Leave a Comment

Unnecessary Dental Work Intro

Dental care is essential for maintaining overall health, but sometimes, the treatments offered may not always be necessary. Being informed about which dental procedures are essential and which are not can save you from unnecessary discomfort and expense. Take a look at these ten dental procedures that, in certain cases, might be unnecessary and could be adding extra costs to your dental bills.

1. Routine X-Rays

Dental Xrays

While X-rays are crucial for diagnosing dental issues, routine use is often unnecessary. Annual X-rays may not be needed unless there are signs of dental problems. According to the Cleveland Clinic, if your gums are healthy, an X-ray should be done every 6 to 18 months.  If your dentist is recommending more X-rays than this and you aren’t having any dental issues, you should inquire about the need and if you aren’t satisfied with the answer, you can always say “no.”

2. Teeth Whitening

Teeth Whitening

Teeth whitening is a cosmetic procedure that many dentists offer. While it enhances the appearance of your teeth, it’s not a necessary procedure for dental health. It may actually cause teeth to become sensitive making it difficult to eat anything that’s too hot or too cold. The costs can be high, and there are various over-the-counter options available at a fraction of the price.

3. Dental Scaling and Root Planing

Dental Scaling and Root Planing

Often suggested for treating gum disease, scaling, and root planing can be unnecessary, especially if you have mild gingivitis that can be resolved with improved oral hygiene. This procedure should be reserved for more severe cases of periodontal disease.

4. Wisdom Teeth Removal

Wisdom Teeth Removal

The removal of wisdom teeth is common, but not always necessary. If they are not causing pain, overcrowding, or other dental issues, they might not need to be removed. It’s important to get a second opinion if your dentist recommends extraction without a clear reason.

5. Fluoride Treatments

Fluoride Treatments

Professional fluoride treatments in adults, especially those with good oral hygiene and no history of cavities, might not be necessary. These treatments are often more beneficial for children and adults with a high risk of tooth decay.

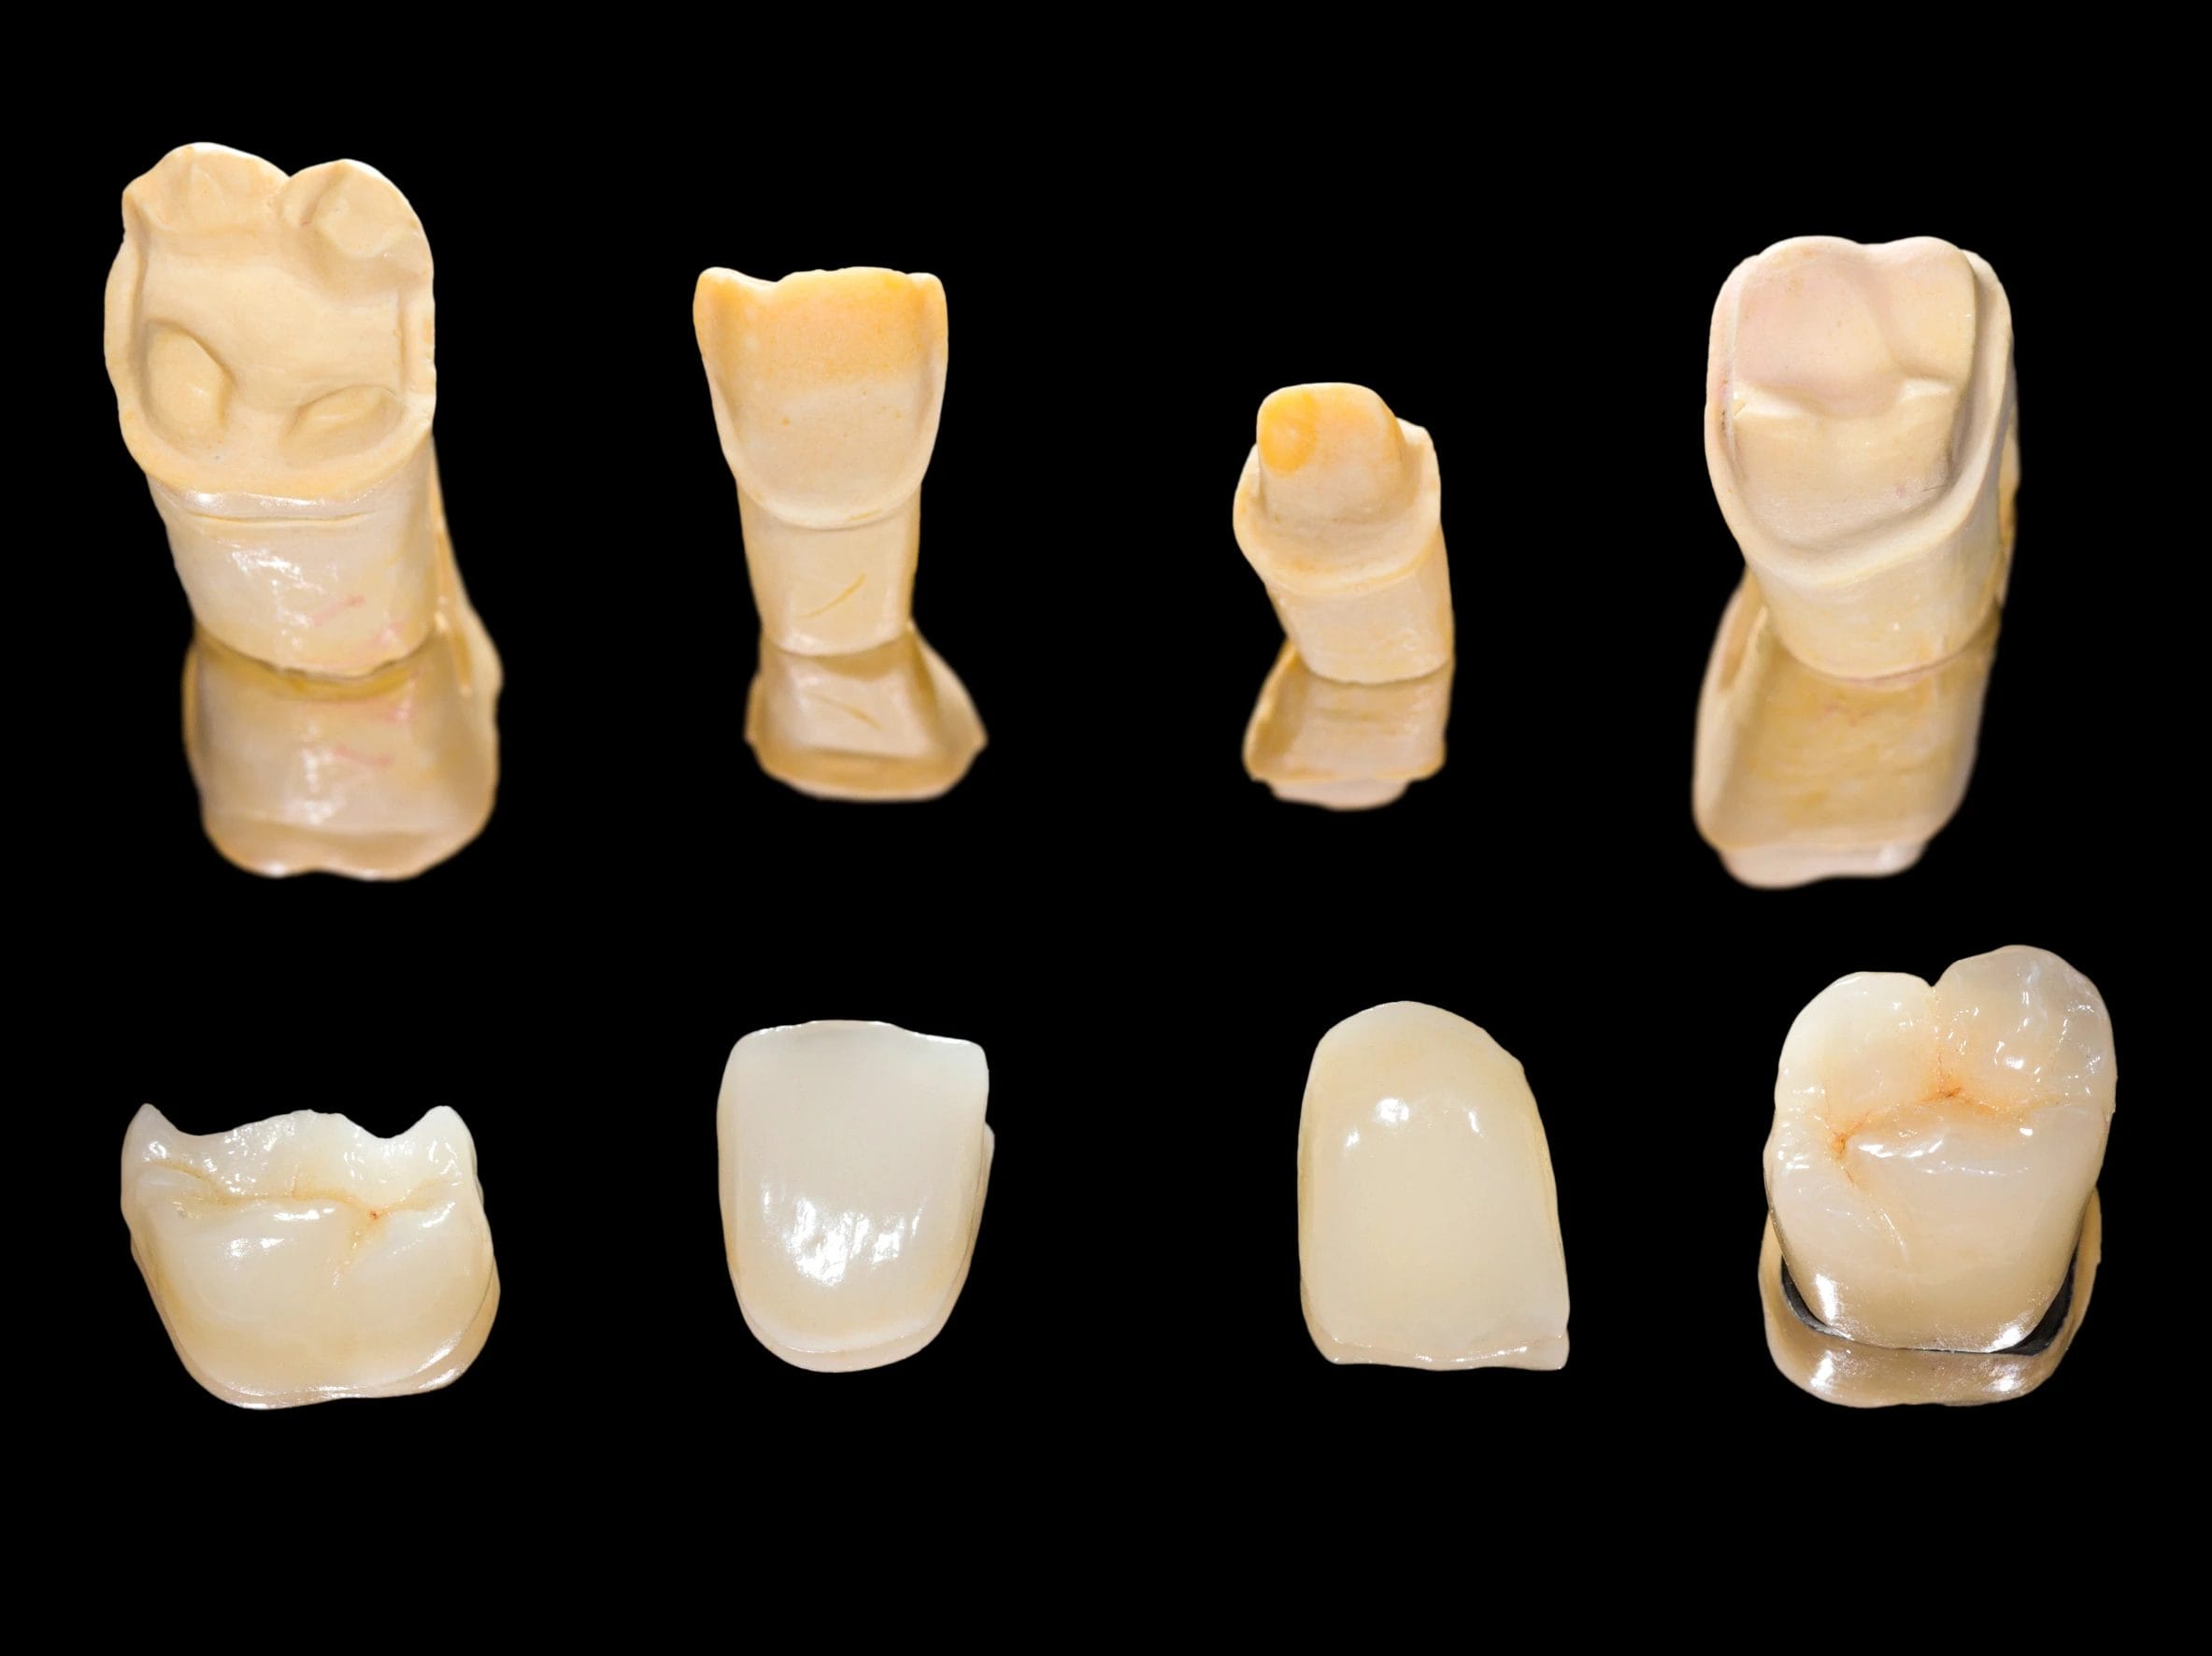
6. Dental Crowns for Minor Tooth Decay

Dental Crowns

For minor tooth decay, a simple filling is often sufficient. Crowns are sometimes recommended for more extensive decay but can be unnecessary for small cavities. They are more expensive and involve removing more tooth structure than fillings. Although, they can be helpful for other conditions such as covering a discolored tooth or a tooth that has an odd shape, this is an expensive fix for a cosmetic issue.

7. Over-the-Counter Product Recommendations

Over The Counter Shopping Recommendations

Dentists may sometimes recommend specific brands of over-the-counter products like toothpaste or mouthwash. However, many of these products offer similar benefits, and a high-priced recommendation may not always be necessary check Dentist in North Lakes.

8. Deep Cleaning for Preventive Care

Deep Cleaning

Deep cleaning is often suggested as a preventive measure. However, for patients without signs of periodontal disease, regular cleanings and good oral hygiene might be just as effective without the added cost and discomfort.

9. Extensive Orthodontic Work for Minor Issues

Extensive Dental Work

While orthodontic work can be necessary for significant dental issues, it may not be needed for minor alignment problems. Less invasive options like retainers or minor cosmetic procedures can sometimes be a more practical and affordable solution.

10. Night Guards from the Dentist

Night Dental Guard

Custom night guards from a dentist can be very costly. If you’re suffering from teeth grinding (bruxism), over-the-counter night guards might be a suitable and far less expensive alternative to try first.

Open Dialogue With Dentist

Talk With Dentist

It’s essential to have an open dialogue with your dentist about the necessity of recommended procedures. Always feel empowered to seek a second opinion. Remember, preventative care through good oral hygiene and regular check-ups is the best way to minimize the need for more extensive dental work.

Be an informed patient, and don’t hesitate to question procedures that seem unnecessary for your dental health and wellbeing.

Have you ever had a dental procedure that you felt was unnecessary? If so, we’d like to hear about it in the comments.

Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance Tagged With: routine x-rays, teeth whitening, wisdom teeth removal

Demystifying Equity Investments: A Beginner’s Roadmap to Building a Robust Portfolio

April 4, 2024 by Susan Paige Leave a Comment


Table of Contents

  • Understanding the Basics of Equity and Shareholding
  • Starting Your Equity Investment Journey
  • Deciphering the Stock Market: A Guide for Beginners
  • Exploring Mutual Funds as a Vehicle for Equity Investment
  • Exchange-Traded Funds (ETFs): Bridging Stocks and Mutual Funds
  • Shareholder Rights and Responsibilities
  • Assessing and Managing Risk in Equity Investments
  • The Long-Term Perspective: Building Wealth Through Equity

Key Takeaways

  • Equity investments extend beyond stocks, encompassing mutual funds and ETFs, each with distinctive advantages.
  • Establishing defined financial goals and understanding risks are the cornerstones of a solid investment strategy.

Understanding the Basics of Equity and Shareholding

Equity signifies more than just a slice of profits; it indicates part ownership in a company and the shared destiny in its success or failure. Investors can touch the equity world via several avenues—common stocks offer a direct equity interest, while mutual funds and ETFs allow a more collective approach. Each type of equity vehicle presents unique opportunities for financial growth and reflects varying degrees of control and exposure to the vicissitudes of the marketplace. Understanding these facets is crucial for choosing the right equity blend that aligns with your investment profile and personal goals.

Starting Your Equity Investment Journey

The quest for solid equity investment strategies starts with introspection and planning. Investors need to forge well-defined financial aspirations and a corresponding investment blueprint. Establishing risk tolerance is akin to setting the sails appropriately for your financial voyage, balancing the potential for stormy markets with the hunger for returns. Knowledge of the market and its myriad elements lays the groundwork for building a resilient and tailored investment strategy. In this initial stage, investors paint their financial future on the canvas of market possibilities, blending their risk profile with the palette of investment opportunities.

Deciphering the Stock Market: A Guide for Beginners

Grasping the stock market’s pulse is a skill developed over time and experience. The essential stock market indices often serve as the market’s barometers, giving investors a snapshot of its overall health. Reading these indices and individual stock charts can offer newcomers critical insights into how equities perform under various market conditions. 

Exploring Mutual Funds as a Vehicle for Equity Investment

Mutual funds present a fortified bastion for those seeking equity exposure without the volatility typically associated with individual stocks. These funds amalgamate investments from many players, harnessing the expertise of seasoned fund managers to steer the portfolio. The inherent diversification of mutual funds mitigates risk and grants investors an accessible entry point into the equity markets. The judicious selection of mutual funds aligned with an investor’s long-term financial objectives is critical in curating a balanced and robust portfolio.

Exchange-Traded Funds (ETFs): Bridging Stocks and Mutual Funds

ETFs meld the traceability of stocks with the diversified approach of mutual funds, offering investors a versatile and cost-effective instrument. They are adept at tracking indices, sectors, or commodities, providing a straightforward means to diversify and hedge investment portfolios. Additionally, most ETFs boast lower expense ratios than mutual funds, enhancing their appeal to cost-conscious investors. Selecting ETFs requires understanding their composition, performance history, and how they complement the thicker tapestry of an investor’s overarching strategy.

Shareholder Rights and Responsibilities

With equity ownership comes a potent mix of rights and responsibilities. Shareholders wield power through votes on crucial corporate actions, from electing boards to policy reforms. This democratic facet of equity investment empowers shareholders to influence the trajectory of a company and underscores the importance of engaging with corporate governance. While enjoying the fruits of their equity stake, investors also bear the onus of due diligence to exercise their rights for the collective well-being of the enterprise and its stakeholders.

Assessing and Managing Risk in Equity Investments

Risks in equity investments are as varied as they are inevitable. Volatility, market uncertainties, and economic shifts pose challenges that require vigilant risk management strategies. Implementing diversification tactics and committing to steady asset allocation are the financial equivalents of constructing a dam to control the flow of risk. This conscientious approach to risk mitigation is indispensable in orchestrating a symphony where the returns notes align with the rhythms of one’s risk capacity.

The Long-Term Perspective: Building Wealth Through Equity

Investing in equity is less a sprint and more a marathon, where compounding returns over extended periods can yield substantial wealth. Patience and persistence become virtues as the investor navigates through the crests and troughs of market fluctuations. A longitudinal view coupled with an unyielding strategy focused on long-term gains often separates fleeting success from enduring wealth creation. The chronicles of successful investors invariably highlight the significance of a persistent long-haul approach to equity investment.

Filed Under: Personal Finance

Innovative Integration: Embracing Bitcoin in Overcoming Financial Challenges

April 4, 2024 by Susan Paige Leave a Comment

Few developments in the digital world have been as revolutionary as the birth of cryptocurrencies, and more specifically, Bitcoin. With the financial world facing unprecedented challenges and complexities, the solution may lie in branching out from the traditional norms within the financial arena to embrace the boundless potential of Bitcoin.

The Unstoppability of Bitcoin

Satoshi Nakamoto’s creation, Bitcoin (BTC), stands as a testament to innovation within the financial landscape. Despite the initial skepticism and criticism, Bitcoin has made it to the top representing a significant fraction of the world’s wealth and proving its worth by being both a store of value and a medium of exchange. It is undeniable that Bitcoin has established itself as a vital currency in the financial world.

Bitcoin: A Valid Financial Solution

While Bitcoin and cryptocurrency might still feel foreign to some investors, this digital asset has already shown its worth by providing solutions to the current financial issues we face, particularly in the face of economic crises and inflation. An expert analyst from Bitcoingambling.org stated that the lack of arbitrary control over Bitcoin ensures its stability amidst financial turmoil. This makes Bitcoin a valid investment to hedge against unpredictable world events and economic downturns.

Finding Your Way around Bitcoin

Navigating the Bitcoin universe can seem daunting for beginners. However, with widely accessible platforms and increasing public awareness, getting started with Bitcoin has never been easier. It’s all about understanding the basics before diving deeper into the intricate world of blockchain, wallets, and cryptocurrency exchanges. With perseverance, one can master the Bitcoin terrain and benefit much from this digital gold.

Bitcoin and Dealing with Retail Barriers

Contrary to popular belief, Bitcoin is not purely an investment tool; it has found its way into our day-to-day transactions. An increasing number of retailers are now accepting Bitcoin payments, thus overcoming one of the major financial barriers in our almost fully digitalized world. More businesses embracing Bitcoin payments equates to increased financial inclusivity.

Tackling Financial Woes: Venture into Bitcoin

The decentralization of Bitcoin serves to counter a variety of financial challenges. It provides a viable alternative to traditional banking systems, proving particularly beneficial for those in countries where the financial infrastructure is inadequate or non-existent. Moreover, as there is no intermediary, Bitcoin transactions can be faster, cheaper, and more efficient.

Bitcoin: A Financial Ally

Bitcoin is not here to replace our traditional financial systems completely but to offer another reliable and innovative method for conducting transactions and saving wealth. Once regarded as a risky venture, Bitcoin is now seen as a financial ally, capable of adding value to one’s portfolio and essentially, their life.

All these factors mentioned build a compelling case for Bitcoin as a force to be reckoned with in the financial landscape. It is high time that we pivot from the longstanding traditional systems and embrace the digital currency’s future, Bitcoin.

Filed Under: Personal Finance

10 Hot Items Thieves Are Looking To Steal From Your Car!!

April 3, 2024 by Tamila McDonald Leave a Comment

Car Thieves

With the rise in vehicle break-ins, understanding what thieves are targeting is crucial for protecting your belongings. Here’s a list of ten items commonly stolen from cars, highlighting the importance of being vigilant and taking preventive steps to safeguard your possessions.

1. Fitness Trackers and Smart Watches

Smart Watches and Fitness Trackers

Fitness trackers and smart watches have become increasingly popular and are often left in cars after a workout or during a quick errand. These high-tech gadgets are not only valuable but also easy to sell, making them a prime target for thieves. To prevent theft, it’s best to keep these devices on you or hidden from view when left in the car.

2. Sporting Equipment

Sports Equipment

Sporting equipment, like golf clubs, bicycles, and ski gear, are prime targets due to their high value and ease of resale. Leaving these items visible in your car can quickly attract thieves. It’s advisable to store such equipment in the trunk or bring it inside to ensure its safety.

3. High-End Clothing and Shoes

High End Clothing and Shoes

Luxury clothing and designer shoes can be significant lures for thieves. These items, especially if left in shopping bags or in plain sight, can suggest the presence of other valuables. To protect them, it’s best to keep such items concealed or take them with you when leaving the car.

4. Car Seats and Baby Accessories

Baby Accessories

Car seats and related baby accessories like strollers and diaper bags are surprisingly attractive to thieves. They are not only costly to replace but also essential for parents. Keeping them inside or in a locked trunk is vital for safeguarding these items.

5. Cash

Cash

Cash is a universal motivator for thieves. It’s untraceable and immediately usable, making it an attractive target. To avoid making your car a target, refrain from leaving any cash, including small change, visible inside your vehicle.

6. Car Parts and Accessories

Car Accessories

High-end car parts, such as audio systems, rims, and custom accessories, are valuable and easy to sell on the black market. It’s essential to park in secure areas and consider additional security measures for your vehicle to prevent these thefts.

7. Work Equipment and Uniforms

Work Equipment

Industry-specific tools and equipment, as well as professional uniforms, are often targeted by thieves. They can indicate the presence of other valuable items and are themselves costly to replace. Secure these items in a locked compartment or take them with you to ensure their safety.

8. Personal Electronics (Tablets, Cameras)

Personal Electronics

Tablets, cameras, and other personal electronics are attractive to thieves for their high resale value. Their portable nature makes them particularly vulnerable when left in a vehicle. To protect these items, store them in a locked glove compartment or trunk, or better yet, keep them with you.

9. Shopping Bags and Visible Items

Shopping Bags and Visible Items

Any visible item, regardless of its actual value, can tempt a thief. Shopping bags, whether they contain new purchases or groceries, can attract unwanted attention. Store these bags in the trunk or take them with you to deter potential break-ins.

10. Gym Bags

Gym Bags

Gym bags are often targets for thieves, as they may contain electronics, jewelry, or cash. Leaving a gym bag in your car, especially in plain sight, can make your vehicle a target for theft. Keep your gym bag with you or store it out of sight to avoid attracting thieves.

Awareness Is Key

Conclusion

Awareness of what items are frequently stolen from cars is key to preventing these thefts. Always be cautious about what you leave in your vehicle and remember, the best deterrent is an empty car. By taking proactive steps to protect your belongings, you can significantly reduce the risk of becoming a victim of car theft. Stay informed, stay safe, and keep your car free of tempting items for peace of mind.

Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance Tagged With: car thieves, cash, fitness trackers, gym bags

Do These 12 Things If You Can’t Pay Your Taxes On Time

April 3, 2024 by Tamila McDonald Leave a Comment

Can't Pay Taxes On Time

When tax season arrives and you find yourself unable to pay what you owe, it can be a source of significant stress. However, there are steps you can take to mitigate the situation and handle your tax obligations responsibly. Here’s a detailed guide on what to do if you can’t pay your taxes on time.

1. Don’t Ignore the Problem

Don't Ignore The Problem

Ignoring your tax bill won’t make it go away; it will only make things worse. The first step is to acknowledge the situation. Understand that the IRS deals with this frequently and offers several solutions to help taxpayers. The key is to act promptly to avoid additional penalties and interest that accrue over time.

2. File Your Tax Return on Time

File On Time


Even if you can’t pay, ensure you file your taxes or file for an extension. Failing to file can result in a failure-to-file penalty. Remember, this extension is only for filing your return, not an extension to pay your tax bill. By filing your taxes, you’re demonstrating a willingness to comply with tax laws, which can be beneficial in your communications with the IRS.

3. Contact the IRS

Contact IRS

Communicate with the IRS about your situation. They are often more accommodating when they see proactive efforts from taxpayers. In many cases, they can offer guidance or a solution you might not have considered. It’s also important to stay informed about any new IRS policies that may offer additional relief.

4. Explore Payment Plans

Explore Payment Options

The IRS offers various payment plans, including short-term extensions and longer installment agreements. These can be a viable option if you need more time to pay your tax bill. Research which plan suits your financial situation best and apply through the IRS website or by contacting them directly.

5. Consider a Short-term Loan or Credit Card Payment

credit card

While it may seem counterintuitive to take on debt, a short-term loan or credit card payment could have lower interest rates than the penalties and interest charged by the IRS. Compare the costs carefully and consider this option if it’s more economical in the long run.

6. Avoid Additional Penalties

Additional Penalties

Make every effort to minimize additional penalties. This includes filing on time, paying as much as you can by the due date, and staying in communication with the IRS. Penalties can accumulate quickly, making your situation more difficult.

7. Check Eligibility for Waiving Penalties

Check Eligibility

In some circumstances, the IRS may waive penalties for late payment if you can show reasonable cause for not paying on time. This does not typically apply to the interest charges on the taxes owed, but reducing penalties can still significantly decrease your total bill.

8. Seek Professional Help

Seek Professional Help

If you feel overwhelmed, it might be wise to consult a tax professional. They can offer guidance tailored to your situation and may know of options and programs that you are not aware of. Involving a professional can also ensure that all paperwork and communication with the IRS are handled correctly.

9. Don’t Overlook Tax Credits and Deductions

Taking Tax Credits and Deductions

Ensure you’ve taken advantage of all applicable tax credits and deductions. Sometimes, people miss out on these, which can reduce their tax liability. Look into any credits or deductions you may not have claimed, as this could significantly lower your tax bill.

10. Prioritize Your Tax Bill

Prioritize Your Tax Bill

If you have various debts, prioritize your tax bill. IRS debts can have more severe consequences than other types of debts, including the potential for wage garnishment. Evaluate your finances and consider paying off your tax debt first or seeking a balance that addresses all your obligations.

11. Consider Future Tax Adjustments

Consider Future Tax Adjustments

If this year was challenging, make adjustments for the next tax year. This might include increasing your withholdings or making estimated tax payments if you’re self-employed. Planning can help you avoid a similar situation in the future.

12. Stay Informed about Tax Law Changes

Tax Law Changes

Keeping abreast of changes in tax laws is crucial, as new legislation can significantly affect your tax liabilities and relief opportunities. Tax laws are frequently revised to reflect economic policies, address emerging issues, or provide relief in times of crisis, such as during economic downturns or public emergencies. These changes can introduce new deductions, credits, or even special programs offering additional relief to taxpayers.

Navigating Tax Challenges with Prudence

Tax Challenges

Facing tax challenges can be daunting, but taking these steps can help navigate through the process more smoothly. Remember, the worst action you can take is no action. By addressing the issue head-on, exploring available options, and seeking professional advice when necessary, you can manage your tax obligations in a way that minimizes stress and financial impact. Stay informed, stay proactive, and know that there are avenues available to help you through this challenging time.

Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance, tax tips Tagged With: Check Eligibility for Waiving Penalties, credit card payment, Explore Payment Plans, Prioritize Your Tax Bill

  • « Previous Page
  • 1
  • …
  • 61
  • 62
  • 63
  • 64
  • 65
  • …
  • 95
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework