• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Car

Here’s The Real Reason Used Car Prices Are Dropping

April 3, 2023 by Tamila McDonald Leave a Comment

Dropping Used Car Prices

Dropping used car prices are increasingly common, which is good news for anyone looking to get a different vehicle in the near future. In January, the average price for a used vehicle was $26,510, a $633 decline from the month prior. While that drop may seem modest, a few of the proceeding months also saw price reductions. Here’s a look at some of the real reasons why used car prices are dropping and whether additional price declines are likely.

Why Used Car Prices Are Dropping

New Car Supply Chain Issues Are Resolving

One of the main reasons that used cars became so expensive during the pandemic was the supply chain issues in the new car market. Fewer new cars were making their way to dealerships. As a result, people with an immediate need for a vehicle often had little choice but to consider used cars.

When more people began shopping for used vehicles, used car inventories also fell. Combine that will rising interest in previously owned vehicles, and prices rose incredibly quickly.

However, the new car supply chain issues are now resolving. While inventory levels may be lower in some areas than they were pre-pandemic, the situation is nowhere near as severe. Since that’s the case, people interested in new vehicles can focus on that part of the market, which may increase used car inventory availability to those who prefer previously owned vehicles in specific areas of the country.

Additionally, new car buyers may have a trade-in as part of the deal. When that occurs, the new car purchase creates an additional vehicle to add to the used market, which also benefits inventory levels.

Shifting Attitudes About Vehicles

The pandemic altered the car-buying landscape. Shelter-in-place orders and rapidly rising amounts of remote positions made vehicles less critical when compared to periods where work commutes were the norm and recreational trips were common. As a result, fewer people were interested in offloading the cars they currently owned and replacing them with newer models, as they weren’t as dependent on their vehicles and weren’t spending as much time in them.

Additionally, some people with paid-off vehicles weren’t necessarily inclined to get a different car during the pandemic. Often, getting a new or used car comes with an auto loan payment, something that isn’t always wise to add to a person’s plate during periods of economic uncertainty. Since these individuals weren’t selling or trading in as regularly, that also hindered used car inventories.

Now that the pandemic isn’t as much of a concern, people’s attitudes about car buying are shifting. Anyone who delayed a purchase with a trade-in due to the pandemic may reevaluate that decision, leading to more used inventory.

Rising Interest Rates

While rising interest rates can cause auto loans to become more expensive, they can also trigger price declines in the used car market. Dealerships understand that higher interest rates make financing a vehicle purchase less appealing. As a result, they have to reevaluate their pricing strategy to make used cars seem reasonably affordable.

Often, this results in dealerships dropping the price of their used cars. When the price is lower, the impact of higher interest rates typically seems less severe to auto loan borrowers. As a result, a smart price drop can stir up more demand, leading to more used car sales.

Are More Used Car Price Reductions Likely?

At this time, used car prices may or may not continue to fall in the coming months. Higher interest rates may incentivize dealerships to keep prices lower, using the reduction to draw in buyers who may otherwise be put off due to the higher financing costs. However, used car wholesale prices are actually on the rise, increasing by 4 percent during a two-week period in February.

Since wholesale prices went up, that can often lead to price increases at the dealership, as dealerships will want to offset as much of the additional spending as possible. But that’s not the only factor.

While used car inventories are increasing in some parts of the country, that rise in inventory levels isn’t necessarily universal. One factor that’s hindering the availability of previously owned cars is that many lessees during the pandemic opted to buy out their contract instead of bringing the leased vehicle back. Often, returned lease vehicles become part of a dealership’s used car inventory, so without those cars coming back, inventories are stymied.

Additionally, new fleet vehicle purchases declined during the pandemic. Again, fleet vehicles were previously traded in at dealerships with a reasonable amount of regularity, leading to used cars on lots. Since fleet vehicle activities changed, that also hinders the used car market.

How much of an impact those issues have on local used car availability varies, as the use of leases or the prevalence of fleet vehicle purchases differ across the country. Still, they could keep inventory levels broadly low enough that additional price declines become unlikely.

Is Now a Good Time to Buy a Used Car?

Ultimately, whether now is a good time to purchase a previously owned vehicle is a personal decision. Prices are falling, which is excellent news for those who need to replace an existing vehicle or acquire an additional car for their household either immediately or in the new future.

However, the current prices of used vehicles are by no means low. The pandemic and the situations it caused led to massive price hikes, and recent declines haven’t overcome those increases entirely. As a result, used cars still aren’t as affordable as they once were, so it’s critical to keep that in mind.

Additionally, rising interest rates are a factor. Ultimately, financing costs more today than it did before inflation made interest rate increases a necessity. Since that’s the case, interest rates could offset any value created by price reductions for those who need to finance.

Since that’s the case, aspiring used vehicle buyers need to look at all of the factors. That way, they can determine whether getting a previously owned car now makes sense in the context of their situation.

Do you know of any other reasons why there are dropping used car prices? Are you considering getting a car but want to see if prices will fall further? Share your thoughts in the comments below.

Read More:

  • 5 Steps for Getting the Most Money for Your Used Car
  • Why Does Carvana Offer Better Deals Than Car Dealerships?
  • How to Choose the Right Automotive Insurance Company


Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Car Tagged With: buy a used car, buying a car, car prices dropping, rising interest rates

How To Retrieve Your Vehicle After Repossession

December 5, 2022 by Tamila McDonald Leave a Comment

Retreive Your Vehicle After Repossession

Having a vehicle repossessed puts you in a difficult spot, particularly if you need the car to get to work, school, stores, or anywhere else. Fortunately, it’s possible to get your vehicle back after a car repossession. If you’re vehicle’s been repossessed and you’d like to get it back, or you’re at risk of a car repossession and want to prepare, here’s what you need to know.

Why a Car Repossession Happens

Generally speaking, a car repossession only occurs if you violate the terms of your auto loan. In most cases, that means failing to make your required payments, as that causes you to default on the loan. However, in some states, not having sufficient vehicle insurance may also trigger repossessions, even if you’ve made all of your payments on time.

How to Prevent a Car Repossession

If you’re at risk of a vehicle repossession, but one hasn’t occurred yet, preventing it from happening is potentially an option. Contact your lender immediately to discuss the issue. If missed payments are the reason for the car repossession, you might be able to negotiate better terms or qualify for a program that gives you more time to make up any missed payments.

For vehicle repossessions relating to insufficient insurance, you’ll need to find a car insurance provider and get a policy that meets the terms of the loan. Speak with your lender to determine precisely what coverage is required. Then, shop around for insurance that offers a compatible policy. Finally, once you have the policy, contact the lender again to provide them with your new coverage details.

How to Retrieve Your Vehicle After Repossession

Contact Your Lender

If your car has already been repossessed, the first step you’ll need to take is to contact your lender. Find out why the vehicle repossession occurred, as well as whether retrieval is an option.

After a repossession, lenders may prepare to auction the car. However, some states have mandated reinstatement or redemption periods, limiting how quickly a lender can move forward with an auction. As a result, you may have time to get your vehicle back without having to deal with the auction process, depending on how long you wait before reaching out and whether you can pursue alternative solutions.

In other cases, a lender may resell the car instead of auctioning it. Again, there is commonly a minimum waiting period before the lender can move forward with reselling, so ask about the timeline during the call.

Do Some Research

What options are available for getting your car back may vary by state. As a result, after speaking with your lender, it’s wise to research local laws regarding repossessed vehicles. That way, you’ll know whether what the lender stated aligns with any relevant legislation in your area.

In most cases, you can perform a simple online search to get an overview of applicable state laws. Simply search for “vehicle repossession [your state]” as a starting point. Alternatively, you may be able to reach out to your state’s attorney general’s office or a local consumer advocacy group for information.

Reinstate the Auto Loan

In specific states, reinstating the loan is a potential option. With this approach, you’d need to pay the entire past due amount along with any repossession-related fees, such as storage and towing costs, within a specific time period.

If reinstatement is available in your state, the lender will outline a timeline for providing them with the required funds and the dollar amount needed. In most cases, the timeframe is relatively short, usually coming with a deadline that’s 10 to 20 days after the date of repossession.

Whether a reinstatement is worth pursuing depends on your financial situation. Acquiring the needed cash is potentially challenging, particularly if you were already struggling to make the monthly payments. However, it’s worth considering if gathering up the money is an option.

Redeem the Auto Loan

Redeeming the auto loan involves paying off any missed payments and the remaining balance in full, as well as covering any repossession-related fees. In many cases, this requires significantly more funds than a reinstatement, as you’ll need to cover the entire balance due. However, if you pay in cash, it also means the vehicle is formally yours in the end, which is beneficial.

If you want to pursue this option after a car repossession, ask the lender for the pay-off amount, including any repossession-related fees. Additionally, find out the timeline for the redemption, letting you know when you’d need to provide the lender with the funds to get your car back this way.

Buy Your Car at Auction

If the lender decides to auction off your vehicle, you can attempt to buy it back then. Buying a car at an auction is relatively simple, but there are some costs involved.

First, you’ll need to register for the auction, and that usually comes with a fee. When you register, you also need to show that you have enough money to potentially participate. That could include providing a credit card number and a letter of guarantee from your bank or bringing cash to the event, depending on what the auction accepts.

Once you register and arrive on-site, you’ll get a numbered paddle. The auctioneer will present a vehicle – discussing its features and the starting price – and open it up to bidding. The auctioneer will then state new prices, and those who are willing to pay the indicated amount raise their paddle to make their bid. That process continues until no further bids come in, making the last bid the purchase price for the associated bidder.

Raise Your Paddle

When your car comes up, you’ll raise your paddle to correspond with the amounts you’re willing to pay. Just keep in mind that you’ll need to cover the entire cost at the end of the auction, as well as a buyer’s premium – which is typically about 10 percent of the bid price – so don’t place a bid that you can’t support financially.

The process is similar for online auctions; you just don’t have to deal with a paddle. Instead, when the auction goes live on the designated, it will show an initial price. Bidders can then submit offers over a specific time period.

Some online auctions show the updated price based on the submitted bids, giving others a chance to outbid the current leader. Others use a sealed-bid process, where the bid amounts aren’t displayed, essentially encouraging all participants to submit their best offer from the beginning.

Regardless, immediate payment is typically required for online auctions, too. As a result, you need to ensure you can cover the purchase price and any buyer fees.

Will You Owe Money After an Auction If You Don’t Buy the Car Back?

It’s important to note that having the vehicle go to auction doesn’t mean you’re immediately clear of the original loan. Whether the loan is complete after the sale primarily depends on the auction price.

If the amount the car sold for at auction meets or exceeds what’s left on your loan, then you won’t typically owe any money to the lender. However, if the auction sale price is less than the remaining balance of your loan, you are typically responsible for the difference.

For example, let’s say that the remaining loan balance and any required fees is $5,000 in total. If the vehicle sells for $5,000 or more at auction, the amount is covered, so you won’t owe any more money. However, if the car sells for $4,000 at auction, you’d still owe $1,000.

If you owe money, you’ll need to pay it like any other debt. Failing to do so can cause the account to go to collections or may make it possible for the lender to sue you for the amount due.

Owe Money After an Auction If You Don’t Buy the Car Back

Should You Retrieve a Vehicle After Repossession?

Even if you can retrieve your vehicle after repossession, that doesn’t always mean that you should. Look at your broader financial situation. Determine whether you’d be able to cover the costs of car ownership after a reinstatement, redemption, or auction purchase.

If so, then getting your vehicle back after a car repossession isn’t necessarily a bad idea if you need it for transportation. If not, then you may want to let it go and explore alternative forms of transportation, such as public transit or a cheaper vehicle you can buy with cash.

Additionally, regardless of whether you retrieve the vehicle after repossession, the action may still show on your credit report. As a result, you’ll want to focus on rebuilding your credit. Make on-time payments on any other debts, pay off your debts as soon as possible, and avoid opening new accounts as much as possible. That way, you can regain your footing.

Have you ever had to retrieve a vehicle after repossession and want to tell others about the experience? Did you go through a car repossession, decided not to get the vehicle back, and want to let others know what that was like? Share your thoughts in the comments below.

Read More:

  • Should You Ever Use a Car Dealer’s In-House Financing?
  • Selling Your Vehicle Via a Private Sale-Follow These Steps
  • Why Does Carvana Offer Better Deals Than Car Dealerships?
Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Car Tagged With: Car Repossession Happens, Owe Money After an Auction If You Don’t Buy the Car Back, Prevent a Car Repossession, Reinstate the Auto Loan, Retrieve Your Vehicle After Repossession

Why Does Carvana Offer Better Deals Than Car Dealerships?

October 3, 2022 by Tamila McDonald Leave a Comment

carvana cars

When you’re shopping for a new car, finding the best possible deal is a common priority. As a result, most buyers turn to a variety of resources. Along with heading to local dealerships, many check out Carvana cars to see if the pricing is better, often being pleasantly surprised by what they find. However, it’s easy to assume that an excellent price isn’t what it appears. Fortunately, it can be the real deal. Here’s a look at why Carvana offers better deals than car dealerships.

What Is Carvana?

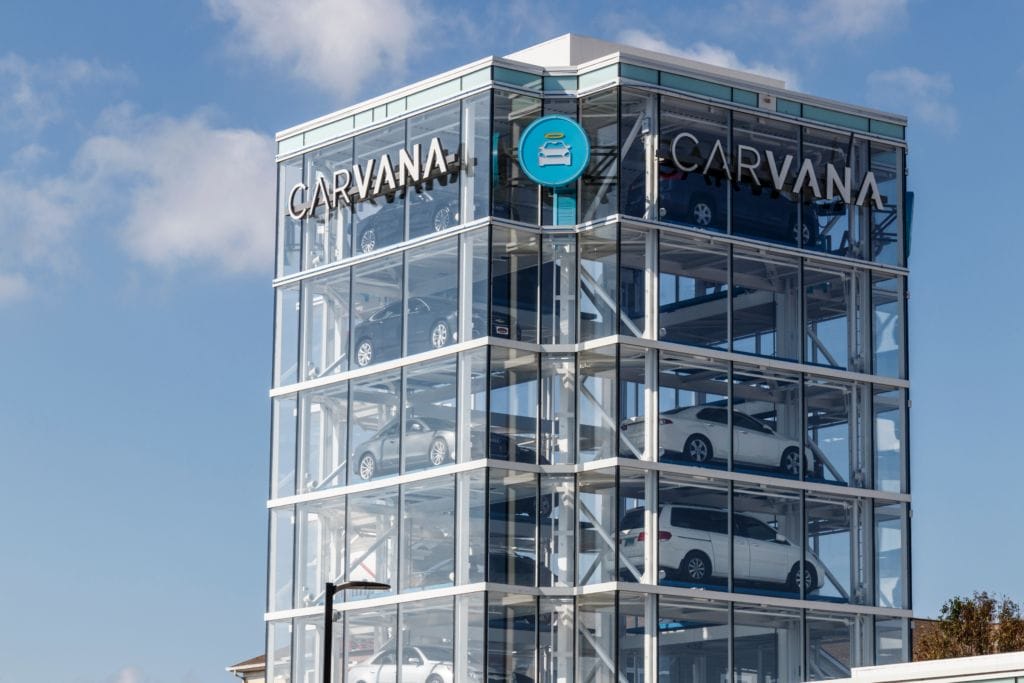
Carvana is a non-traditional car dealership that focuses on used cars. It was founded in 2012 and captured ample attention after installing car vending machines in several major cities.

The company focuses on online sales over a traditional dealership model. Along with the car vending machines for picking up a car after buying it, Carvana will deliver your recently purchased vehicle to your home if you prefer.

In many ways, Carvana is a leader when it comes to convenience. Fewer operating models make a used vehicle purchase quite as streamlined, which is why it’s become such an attractive option.

How Carvana Works

Primarily, Carvana operates in the used car space. They focus on high-quality but affordable vehicles, mainly targeting Millennials by introducing unique technologies and ample convenience.

Car purchases through Carvana are predominately handled online. Since that means buyers can’t see a vehicle in person before making a buying decision, the listings are highly detailed. Along with a slew of photos, you’ll see information about the specs and the results of Carvana’s in-house inspection. Additionally, you’ll be able to review photos that show any flaws the company discovered along the way, leading to reasonable transparency.

Another feature of Carvana that is designed to offset the risk of not being able to check out the vehicle in person is the return policy. Buyers have seven days to make sure the car is right for them. If not, they have the option to return the vehicle and get their money back.

If you find a car you’re interested in, you can begin the purchase paperwork with a few clicks. However, if another buyer has already started the paperwork for that vehicle, you’ll get a notification that the car is temporarily on hold, along with a timer that shows how long the other buyer has before the vehicle is released for sale again.

The purchase dashboard is pretty straightforward. You provide personal details, information about trade-ins, and delivery and pickup preferences. You also tell the company if you’re using a loan or cash to complete the purchase or even arrange financing through the application. Overall, the entire process takes between 10 and 20 minutes in most cases.

Why Carvana Has Better Deals Than Dealerships

First, it’s important to note that not every vehicle at Carvana is automatically the lowest price you can find. The pricing is based on several factors, and there are instances where you may be able to score something a little better by looking elsewhere.

However, Carvana generally comes out ahead. One main reason is that you don’t end up paying certain dealer fees along the way. Instead, Carvana doesn’t pass certain paperwork filing costs onto the buyer.

Second, this approach to selling vehicles eliminates certain employee-related expenses. They aren’t paying salespeople to be on the lot, and they don’t owe them commissions. The latter part impacts pricing in two ways. Along with lowering Carvana’s operating costs, it means buyers aren’t haggling with someone whose pay is dependent on convincing you to pay a bit more.

Third, Carvana doesn’t operate as many locations as some competitors with similar purchase models. That reduces its overall overhead, making it easier to undercut competitors by several hundred dollars on most cars.

Finally, Carvana does give you an easy way to trade in your current vehicle, but it isn’t necessarily offering you the best price. This may come as a surprise, considering some people using the site have seen unexpectedly high offers recently. However, that isn’t reflective of Carvana. Instead, that’s simply the state of the used car market.

By purchasing cars for as little as possible, Carvana can then sell them below their fair market value and still snag a tidy profit. The trick is that it’s the lower sales prices that draw people in, not the trade-in or cash offer prices. As a result, they hope that buyers with a vehicle to unload will simply accept the lower price because doing so is incredibly convenient.

Should You Use Carvana to Buy a Car?

Generally, there’s no reason not to consider Carvana when you’re purchasing a vehicle. Most customers say that you can expect great customer service if you need help. Plus, the pricing is based on avoiding negotiations, so even if you have to call the company, they aren’t going to pressure you into higher-priced options. The price on the website is what it is, and that’s that.

The purchasing process itself is reasonably simple and quick, too. If you look at financing options through Carvana, the rates are typically competitive as well (though it’s still a good idea to comparison shop). It’s also hard to beat the option to have your car delivered to your front door, and if you aren’t satisfied, you can arrange a return during the initial seven days for any reason and get your money back.

However, if you have a trade-in or a vehicle you’d otherwise like to sell, Carvana isn’t going to give you the best price. Since that’s the case, you may need to explore other options. Fortunately, there are plenty available, including many you can handle online to get quick cash offers. While it may take more effort than having Carvana pick it up, the significant price difference could make it worth the extra time.

Carvana Cars May Not Have Comprehensive Inspections

Additionally, while Carvana does an inspection before it sells a vehicle, understand that it isn’t always as comprehensive as what you’d get directly from a mechanic. Since that’s the case, get your own inspection right away. Then, if they spot a problem that you don’t want to mess with, return the vehicle to Carvana during that seven-day window and get your money back.

Finally, Carvana may not work for you if you aren’t sure what you want. Remember, there are no test drive options when you shop and buy online like this. The only way to get in and check out the vehicle is to buy it, and while you can return it within seven days, that’s a big step for a test drive. As a result, you may be better off going another route or, at least, doing some research before you head to the Carvana site, allowing you to figure out what you’re after first.

Have you purchased from Carvana and want to tell others about your experience buying Carvana cars? Did you consider using Carvana but decided to go in another direction and want to discuss why? Share your thoughts in the comments below.

Read More:

  • How to Buy Your New Car the Smart Way
  • What Are the Most Expensive Cars to Maintain?
  • Saving Money on Car Repairs After an Accident


Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Car Tagged With: About Carvana, Buying a car with carvana, Carvana vs dealership deals, How Carvana works

  • « Previous Page
  • 1
  • …
  • 4
  • 5
  • 6

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework