• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for IRA rules

Retirement Account Rollover Rules: When a Signature Is Not Enough

August 5, 2026 by Brandon Marcus Leave a Comment

Retirement Account Rollover Rules: When a Signature Is Not Enough
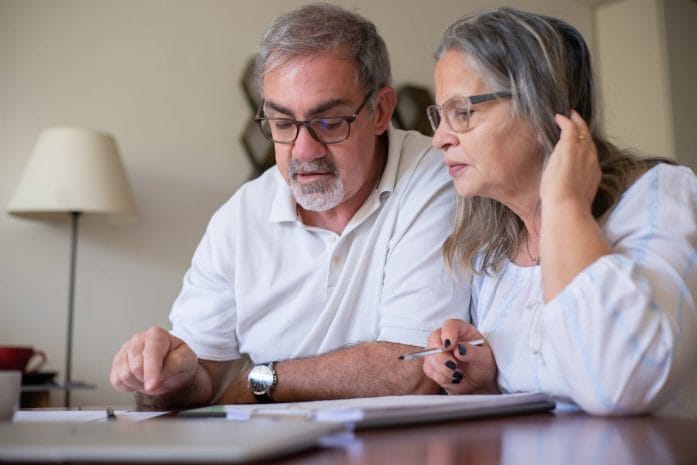
A retiree must review retirement rollover paperwork while remembering the importance of careful account transfers, IRS rules, and tax planning before signing documents – Shutterstock

Moving retirement money from one account to another sounds simple. A signature, a form, and a quick transfer might seem like the whole recipe, but rollover rules often hide important details that can affect taxes, timing, and future savings choices. A small paperwork mistake can turn a routine retirement move into a frustrating financial puzzle.

Retirement rollovers often happen during job changes, career transitions, or retirement planning updates. Knowing the rules before signing anything can help account owners avoid unnecessary surprises and make smarter decisions with their hard-earned savings. The IRS provides guidelines for retirement accounts, including contribution limits and rules that affect IRAs and workplace plans.

A Signature Starts the Process, But Details Finish the Job

A signature alone does not always tell the full story of a retirement rollover. Account owners need to know where the money moves, which type of account receives it, and how the transfer fits within IRS rules. A rollover involves more than pushing paperwork across a desk and hoping the numbers land in the right place. Retirement accounts follow specific tax rules, and the wrong move can create complications. A careful review before signing can help prevent a retirement account from becoming a paperwork adventure nobody requested.

For example, someone leaving a job might decide to move money from a former employer’s 401(k) into an IRA. That person needs to confirm the receiving account accepts the rollover and that the transaction follows applicable requirements. The IRS lists separate rules for IRAs and workplace retirement plans, including contribution limits that change over time. In 2026, the IRS announced a 401(k) contribution limit increase to $24,500 and an IRA contribution limit increase to $7,500. Those limits matter because retirement decisions often connect several moving pieces at once.

Common Rollover Mistakes Can Create Big Headaches

Many rollover problems begin with assumptions. A person might assume every retirement account transfer works the same way, but different account types follow different rules. Some people focus only on the signature and forget to check the destination account details. Others rush through forms because retirement paperwork rarely feels like exciting reading material. Yet those tiny details can make a major difference.

A common mistake involves moving money without confirming the tax treatment. Retirement account decisions can affect taxes differently depending on the situation, account type, and transaction details. The IRS provides retirement guidance, but individual circumstances can vary widely. Professional review can help people evaluate their options before they finalize a rollover decision.

Careful Planning Helps Protect Retirement Savings

A retirement rollover should feel like a planned road trip, not a last-minute scramble through unfamiliar streets. Before moving funds, account owners should gather account information, review available choices, and ask questions about how the transfer works. A checklist can make the process less intimidating and easier to manage. Good preparation helps people focus on long-term goals instead of chasing paperwork after a problem appears.

The smartest rollover decisions usually start with a clear reason for the move. Someone might want simpler account management, different investment choices, or a more organized retirement plan. Each reason brings different considerations, and the best choice depends on personal financial circumstances. Reviewing options with a qualified tax professional can help clarify possible tax consequences before money changes locations.

Retirement Rules Reward Patience and Attention

Retirement accounts represent years of saving, so a rollover deserves more attention than a quick signature and a handshake. The IRS updates retirement account limits and guidance, which means account owners need current information when making decisions. The 2026 contribution limits show how retirement rules can shift over time. Staying informed helps people avoid relying on outdated assumptions. A few extra minutes of research can protect years of retirement savings.

The biggest lesson involves slowing down before making a permanent choice. Retirement paperwork may look ordinary, but every line can carry important meaning. A rollover decision should match a person’s financial goals, tax situation, and retirement strategy. Tax treatment varies, so professional review can help people make choices that fit their circumstances. A signature matters, but it represents only one part of the process.

The Smart Move Happens Before the Ink Dries

Retirement rollovers work best when preparation comes before paperwork. A signature confirms a decision, but it does not replace careful review of account rules, tax considerations, and long-term goals. The IRS offers retirement guidance that helps account owners stay informed about contribution limits and account requirements. Retirement savings deserve attention because even small mistakes can create unnecessary complications. The best rollover decisions combine patience, accurate information, and thoughtful planning.

A retirement account move does not need to feel like a maze filled with confusing forms and mysterious rules. Account owners who check details before acting put themselves in a stronger position. Reviewing options, asking questions, and seeking professional advice when needed can make the process smoother. The goal involves protecting retirement savings while creating a plan that fits future needs. The signature matters, but the strategy behind it matters even more.

What rollover experiences have you had, and what advice would you share with someone preparing to move retirement funds?

You May Also Like…

15 States Now Automatically Enroll Eligible Workers in Retirement Accounts—Is Yours One of Them?

Ages 60 to 63: How the New Catch-Up Contribution Rules Change Retirement Saving

12 Distinctive Advantages of Self-Directed Retirement Accounts

Average Social Security Benefits for 81-Year-Old Retirees in 2026

Medicare and Employer Coverage Don’t Always Work Together the Way Retirees Expect

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: 401(k) rollover, IRA rules, Personal Finance, retirement accounts, retirement planning, taxes

6 RMD Planning Errors Retirees Can Still Correct Before Year-End

August 4, 2026 by Brandon Marcus Leave a Comment

6 RMD Planning Errors Retirees Can Still Correct Before Year-End
Retirees review retirement account documents and a calendar while planning required minimum distributions before year-end. This picture highlights the importance of checking RMD deadlines, account details, and tax planning strategies – Shutterstock

Required minimum distributions can sneak up like a forgotten subscription charge, except the consequences involve taxes instead of a few unwanted dollars leaving a bank account. Retirees who review their RMD plans before year-end can still catch mistakes, adjust strategies, and avoid unnecessary headaches when tax time arrives.

The IRS sets specific rules for retirement accounts, including contribution limits, senior tax resources, and filing guidance that affect retirement planning decisions. The right moves depend on each person’s situation, so retirees should consider working with a qualified tax professional before making major changes.

1. Missing the RMD Deadline Creates a Costly Surprise

Many retirees make the mistake of treating an RMD like a suggestion instead of a yearly requirement. Traditional retirement accounts follow IRS distribution rules, and missing required withdrawals can create unwanted tax complications. A simple calendar reminder, account review, or conversation with a financial professional can prevent this problem from turning into a year-end scramble.

The first step involves checking retirement account details and confirming whether a distribution needs attention before the deadline. The IRS continues to provide retirement and senior tax resources designed to help older taxpayers prepare for filing season. A quick review now can feel much easier than a frantic search for paperwork later.

2. Forgetting About Multiple Retirement Accounts

Retirees with several IRAs or workplace retirement accounts sometimes lose track of which accounts need action. One forgotten account can create confusion, especially when old employer plans sit quietly in the background. Gathering every account statement creates a clearer picture of the retirement income puzzle.

This process does not require fancy spreadsheets or a mountain of paperwork. A simple list of account types, balances, and distribution plans can reveal gaps before year-end arrives. The goal involves creating a retirement checklist that leaves fewer surprises hiding in the corners.

3. Taking the Wrong Amount From Retirement Funds

Some retirees withdraw money without reviewing whether the amount matches their RMD needs. Taking too much can create a larger taxable income situation, while taking too little can create problems. Careful planning helps match withdrawals with actual financial needs instead of making random guesses.

Retirement accounts do not operate like a household checking account where any withdrawal feels interchangeable. Account rules matter, and tax consequences can vary depending on personal circumstances. A year-end review can help retirees decide whether their current distribution approach still fits their goals.

4. Ignoring New Retirement Account Limits

Retirees who still work sometimes overlook changes that affect retirement savings opportunities. For 2026, the IRS increased the 401(k) contribution limit to $24,500 and increased the IRA contribution limit to $7,500.  Those updates can matter for workers who continue earning income while planning their next retirement chapter.

A mistake happens when people assume retirement planning ends the moment they leave a full-time job. Some retirees continue working, contributing, and adjusting their strategy for future tax years. Reviewing current limits can uncover opportunities that might otherwise disappear unnoticed.

5. Overlooking Tax Planning Around Withdrawals

RMD planning involves more than moving money from one account to another. A withdrawal can affect taxable income, so retirees should look at the bigger financial picture before making decisions. Taxes, charitable goals, and everyday spending needs all deserve a seat at the planning table.

The IRS offers filing resources specifically for older taxpayers, including reminders about tax-related topics that affect seniors. Waiting until tax documents arrive can make choices harder because fewer planning options remain. A little preparation before year-end can make the following tax season feel far less stressful.

6. Assuming Last Year’s Plan Still Works

Retirement plans need occasional tuneups because life rarely stays exactly the same. Changes in income, account balances, health expenses, or family goals can make an old RMD strategy outdated. Copying last year’s approach without checking current details can create avoidable problems.

A yearly retirement review works like checking the tires before a road trip. The car may look fine sitting in the driveway, but small issues can become bigger problems down the highway. Reviewing RMD decisions before year-end gives retirees a chance to make thoughtful adjustments while time remains.

A Year-End Retirement Checkup Can Protect Future Plans

RMD mistakes often happen because retirement rules feel complicated and easy to ignore until a deadline approaches. The good news involves the opportunity to review accounts, correct planning errors, and make smarter choices before the calendar turns. Small adjustments today can help create a smoother financial path tomorrow.

Retirement planning does not require perfection, but it does require attention. The IRS updates retirement and senior tax information regularly, including resources that help older taxpayers prepare for filing responsibilities. Before making any tax-related decision, retirees should consult a qualified tax advisor or financial professional who understands their specific situation. This article provides general educational information and does not provide personal tax advice.

Which RMD planning mistake do you think causes the most confusion for retirees? Share your thoughts in the comments.

You May Also Like…

Ages 60 to 63: How the New Catch-Up Contribution Rules Change Retirement Saving

How the Social Security Earnings Test Works for Part-Time Retirees

Home Insurance Renewal Changes Retirees Can Challenge or Compare

IRS Replaces First Time Abate Program With Automatic Penalty Relief for Taxpayers With Clean Compliance History

No Kids, No Heirs? Here’s How to Create an Estate Plan

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: 401k planning, IRA rules, retirement income, retirement taxes, RMD planning, senior finances

What Happens if You Forget an RMD? The Costly Consequences Explained

April 8, 2026 by Brandon Marcus Leave a Comment

What Happens if You Forget an RMD? The Costly Consequences Explained
Image Source: Pexels.com

The idea of forgetting something important rarely sparks panic—until that “something” comes with a hefty tax penalty attached. Required Minimum Distributions, better known as RMDs, don’t sit quietly in the background. They demand attention, precision, and timing, and the moment someone misses one, the consequences arrive fast and loud. No one enjoys dealing with the IRS on a normal day, but skipping an RMD can turn a simple oversight into a financial headache that refuses to go away. That reality alone makes this topic worth a closer look.

Retirement accounts often feel like a reward after years of hard work, but they come with rules that don’t bend easily. The government allowed those tax advantages for decades, and eventually, it wants its share. That’s where RMDs step in, forcing withdrawals whether someone needs the money or not. Forgetting one doesn’t just delay a withdrawal—it triggers penalties, paperwork, and stress that can spiral quickly.

The Penalty That Makes People Do a Double Take

For years, missing an RMD carried one of the harshest penalties in the tax code. The IRS used to impose a 50 percent penalty on the amount that should have been withdrawn but wasn’t, and that number shocked just about everyone who learned about it. Recent changes under the SECURE 2.0 Act lowered that penalty to 25 percent, and in some cases even 10 percent if someone corrects the mistake quickly. That adjustment offers some relief, but it still represents a significant financial hit that no one wants to absorb. A missed withdrawal of $10,000 could still lead to a $2,500 penalty if left unresolved. That kind of loss stings, especially when it stems from something as simple as forgetting a deadline.

Deadlines play a huge role in this situation, and they don’t leave much room for error. Most retirees must take their RMD by December 31 each year, although the first RMD allows a one-time delay until April 1 of the following year. That exception creates confusion because delaying the first withdrawal means taking two RMDs in one year, which can bump someone into a higher tax bracket. Missing either deadline triggers the penalty, and the IRS does not send reminders. That responsibility falls entirely on the account holder, which makes organization and awareness essential. Anyone juggling multiple retirement accounts faces an even greater risk of overlooking one.

Fixing the Mistake Before It Gets Worse

A missed RMD doesn’t lock someone into permanent trouble, but quick action makes all the difference. The first step involves taking the missed distribution as soon as possible, even if the deadline has already passed. That move shows good faith and starts the process of correcting the error. Waiting longer only increases the chance of complications, and it signals neglect rather than oversight. Acting quickly keeps the situation manageable and prevents additional stress from building.

After taking the distribution, the next step involves filing IRS Form 5329, which reports the missed RMD and calculates the penalty. This form also allows individuals to request a waiver of that penalty by explaining the mistake and showing that they corrected it promptly. The IRS often grants waivers when someone demonstrates a reasonable error and takes immediate steps to fix it. Clear explanations, accurate documentation, and timely action improve the odds of avoiding the penalty altogether. Ignoring the issue or filing incomplete information almost guarantees a worse outcome.

Why RMDs Catch So Many People Off Guard

RMD rules don’t exactly present themselves in a simple, easy-to-follow package. They depend on age, account type, and changing laws, which creates confusion even among financially savvy individuals. The SECURE Act raised the starting age for RMDs from 70½ to 72, and later legislation pushed it to 73, with another increase scheduled in the future. These shifts create uncertainty, especially for those who planned retirement strategies under older rules. Keeping up with those changes requires attention that many people simply don’t prioritize until it becomes urgent.

Multiple accounts add another layer of complexity that trips people up. Traditional IRAs allow aggregation, meaning someone can calculate the total RMD and withdraw it from one account. Employer-sponsored plans like 401(k)s follow different rules, requiring separate withdrawals from each account. Mixing those requirements often leads to missed distributions, especially when accounts sit with different financial institutions. Without a clear system, it becomes easy to assume everything is handled when it isn’t. That assumption creates the perfect setup for an expensive mistake.

Staying Ahead of the Problem

Avoiding a missed RMD starts with building a system that removes guesswork. Setting calendar reminders months in advance creates a buffer that allows time to act without pressure. Many financial institutions offer automatic RMD services, which calculate and distribute the required amount on schedule. Using those tools reduces the risk of human error and keeps everything running smoothly. Automation doesn’t eliminate responsibility, but it provides a strong safety net that helps prevent costly oversights.

Working with a financial advisor can also make a big difference, especially for those with multiple accounts or complex financial situations. Advisors track changing rules, calculate accurate RMD amounts, and ensure distributions happen on time. That guidance turns a confusing process into a manageable routine. Even without an advisor, regularly reviewing account statements and confirming RMD requirements each year keeps things under control. Staying proactive beats scrambling to fix a mistake every single time.

What Happens if You Forget an RMD? The Costly Consequences Explained
Image Source: Pexels.com

The Ripple Effect on Taxes and Retirement Plans

Missing an RMD doesn’t just trigger a penalty—it can disrupt an entire financial strategy. Required distributions count as taxable income, so skipping one and taking it later can push someone into a higher tax bracket. That shift affects not only federal taxes but potentially state taxes as well. A single oversight can ripple through a tax return in ways that feel frustrating and avoidable. Planning withdrawals carefully helps maintain a steady tax situation instead of creating sudden spikes.

RMD timing also plays a role in long-term retirement planning. Some individuals use strategies like qualified charitable distributions (QCDs) to reduce taxable income while meeting RMD requirements. Missing the deadline eliminates the opportunity to use those strategies effectively for that year. That loss doesn’t just affect taxes—it limits flexibility and reduces control over retirement income. Staying on top of RMDs preserves those options and keeps financial plans on track.

The Important Lesson Behind a Missed RMD

Forgetting an RMD may start as a simple oversight, but it quickly turns into a reminder that retirement accounts come with responsibilities that don’t fade over time. The penalty grabs attention, the paperwork demands action, and the stress pushes financial organization to the top of the priority list. Staying ahead of deadlines, understanding the rules, and using available tools can turn a stressful situation into a manageable routine. No one needs to memorize every detail, but ignoring the basics creates problems that grow fast.

So, what strategies have worked best for keeping your financial deadlines on track, and what lessons have shaped a smarter approach to retirement planning? It’s time to share your thoughts, experiences, or tips in the comments section.

You May Also Like…

How Seniors Jeopardize Their Social Security Right After Retirement

10 Retirement States That No Longer Cater to Retirees

7 Hidden Costs That Are Eating Away at Retirement Income

Retirement Accounts Are Triggering Unexpected Taxes — What Some Investors Overlook

8 Hidden Fees That Can Eat Away at Your Retirement Savings

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: 401(k) withdrawals, IRA rules, IRS penalties, Personal Finance, Planning, required minimum distribution, retirement income, retirement mistakes, retirement planning, RMD rules, tax strategies, taxes

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework