It’s 2023, and the global recession isn’t really a healthy environment for your savings or investments. So let’s face it, the automobile or real estate loan you’ve been looking to get now looks more like a mirage. Doesn’t it? [Read more…]
It’s 2023, and the global recession isn’t really a healthy environment for your savings or investments. So let’s face it, the automobile or real estate loan you’ve been looking to get now looks more like a mirage. Doesn’t it? [Read more…]
Short-term loans are a popular option for those in need of quick cash in an emergency for a short period of time. They offer fast approval and can be used for a variety of purposes, including unexpected expenses, emergencies, or to bridge the gap between pay checks. There is a range of short-term loans to choose from, all varying in terms and conditions. Below, we will provide a complete overview of short-term loans so you can learn more about them. [Read more…]
Financial distress is highly common. Often, it occurs when unexpected money problems arise or ongoing challenges start making it increasingly difficult to make ends meet. At times, a simple lack of proper planning could be responsible. Even with solid planning, financially difficult events like divorces or unemployment can wreak havoc on your finances. Fortunately, regardless of the reason, it’s possible to move forward. Here’s a look at how to deal with financial distress.
Before you can start moving forward, you need to identify the source of your financial distress. This means examining the situation to look beyond the basics. For example, simply knowing that your income isn’t enough to cover your expenses may not be sufficient if you want to solve the situation. You need to determine why you’re falling short, how long that shortfall will remain an issue, and if there are any patterns or financial moves you’re making that are causing the situation to become more challenging.
Ultimately, you need to determine precisely what about where you stand is causing discomfort. Are you turning to credit cards to handle basic expenses because you don’t have enough income? Were your debt payments once manageable, but the end of an introductory APR or special promotion is now causing problems? Did an adjustable APR cause your required payment to become too challenging to cover? Are rising food prices throwing off your budget?
By asking questions like those above, you can figure out why you’re experiencing financial distress. Once you know, it’s easier to use a targeted strategy to move forward.
When you’re dealing with a challenging financial situation, spending time outlining your priorities is a must. This is especially true if you currently don’t have enough income to handle all of your obligations, but it’s valuable for anyone experiencing financial distress.
For those who can’t afford all of their bills, spend time identifying the ones you simply can’t let fall behind. Generally, that includes housing, utilities, transportation, groceries, and similar must-haves that ensure your survival and are necessary to keep earning an income.
By doing that, you can see how much the essentials are costing every month. If there are opportunities to cut back in these areas, that’s potentially wise. However, if you’re already in low-cost housing based on your location, don’t have an expensive vehicle or use public transit, and have a barebones grocery budget that you’re sticking with, you’ll know exactly how much the essentials cost.
After that, you can review your remaining expenses to determine which ones are more critical than others. While it’s again wise to reduce your other bills as much as possible, cutting back wherever the opportunity arises, it also helps you see where a sacrifice can occur. Then, if you need to miss a payment, you’re ensuring that the critical bills are covered first, allowing you to choose a less-crucial one to skip.
For those who can pay all of their bills and those who can’t, this exercise helps you see what matters to you most. Then, you can choose costs that aren’t as vital in your eyes for drastic cost-cutting. Essentially, it ensures that any short-term sacrifices are in areas that cause you the least amount of discomfort, letting you prioritize your spending based on what matters to you.
After determining your priorities, it’s time to identify appropriate cutbacks and create a new budget. As mentioned above, work to scale back spending in all lower-priority areas where reductions are possible. Usually, this starts with lifestyle adjustments that aren’t connected to essentials. Reducing eating out and entertainment spending are both solid starting points, but it’s also wise to examine other areas where you may be able to find savings.
Once you finish reducing costs where you can, it’s time to create your new budget. List your expenses based on your priorities and allocate your income to them. As you work down the list, identify the point where your costs exceed your income if that occurs. Then, you can determine how much you’re short.
If you’re not short, assess how much money you have remaining. After that, determine if you can direct those funds to areas that result in less financial stress. For example, building an emergency fund could give you peace of mind. Similarly, reducing your credit card debt may relieve some anxiety.
If you know that you won’t be able to make a scheduled debt payment, speak to your lender as soon as possible. Many creditors have programs that assist those with challenging financial situations, allowing you to avoid – or limit the impact of – missed payments and similar issues.
Precisely what’s available varies by lender and your situation. In some cases, you might be eligible for forbearance, interest rate reductions, term extensions, or other adjustments that can reduce your financial stresses. Ultimately, you won’t know what’s available until you ask, and the sooner you find out, the easier it is to find suitable arrangements with one or all of your creditors while you work to get back on your feet.
While getting a second job or starting a side hustle can potentially add some stress, the extra income may make solving your financial concerns easier. If you’re currently employed, ask about overtime. If you’re performing well and haven’t seen a pay increase recently, you could also see if you’re eligible for a raise.
Otherwise, start exploring part-time jobs, freelancing, or gig opportunities. Generally, genuine part-time employment is the least risky. Otherwise, stick with other side hustles that have a reputation for being safe options, making it easier to avoid scams.
You could also sell household items you no longer need for a quick injection of funds. Whether it’s listing items online or holding a yard sale, it’s a way to earn a bit from things you own but don’t have a clear reason to keep. Just make sure that you remain security minded if you sell online, only agreeing to meet buyers in safe locations like police department parking lots.
Getting outside help can reduce feelings of financial distress in many ways, primarily depending on the approach you use. Speaking with trusted loved ones or a counselor could give you an outlet for your concerns. Plus, you might get advice that can make dealing with any stress or anxiety easier.
If you’re not able to make ends meet and your financial situation seems insurmountable, turning to a credit counseling organization could bring some relief. They can provide advice to move you toward financial recovery, and they may be able to arrange a debt management plan to simplify paying down your debts.
Just make sure you choose a reputable nonprofit credit counseling organization that offers the service, taking time to research it carefully, as there are scams operating in this area. Looking for options through the National Foundation for Credit Counseling or the Financial Counseling Association of America is typically a good starting point.
It’s also wise to look for community services or nonprofits that may offer financial or others types of support to those in need. States typically have agencies dedicated to helping low-income individuals, and there are many nonprofits that operate programs that provide various types of assistance. Again, just make sure to research them carefully, as there are scams that masquerade as charities.
In many cases, seeing that your efforts are leading to positive results can alleviate stress and help keep you motivated. Without appropriate tracking, you may not realize that your approach is working. As a result, it’s wise to monitor your progress toward your various financial goals and give yourself some kudos every time you get closer to the finish line.
Tracking how your financial situation changes also lets you know if a strategy that you thought would work isn’t making the difference you expected. Plus, monitoring your spending allows you to identify budget leaks you didn’t notice previously. As a result, it’s far easier to take quick corrective action, making it easier to get on the right track and ensure you’ll make appropriate progress in time.
Do you have any other tips to help someone deal with financial distress? Have you tried some of the options above and want to tell others how they impacted your financial anxiety or stress levels? Share your thoughts in the comments below.
Read More:
Accidents involving pedestrians frequently lead to severe injuries. In contrast to car passengers, pedestrians have no outside protection. Recovery from injuries can take months or years. Children under the age of 15 are particularly vulnerable to serious injuries in pedestrian accidents. Parents must be informed about accidents involving kid pedestrians to reduce the likelihood of these mishaps and the degree of injuries. In case your child is injured due to a pedestrian accident, contact a local PI law firm to help you recover compensation.
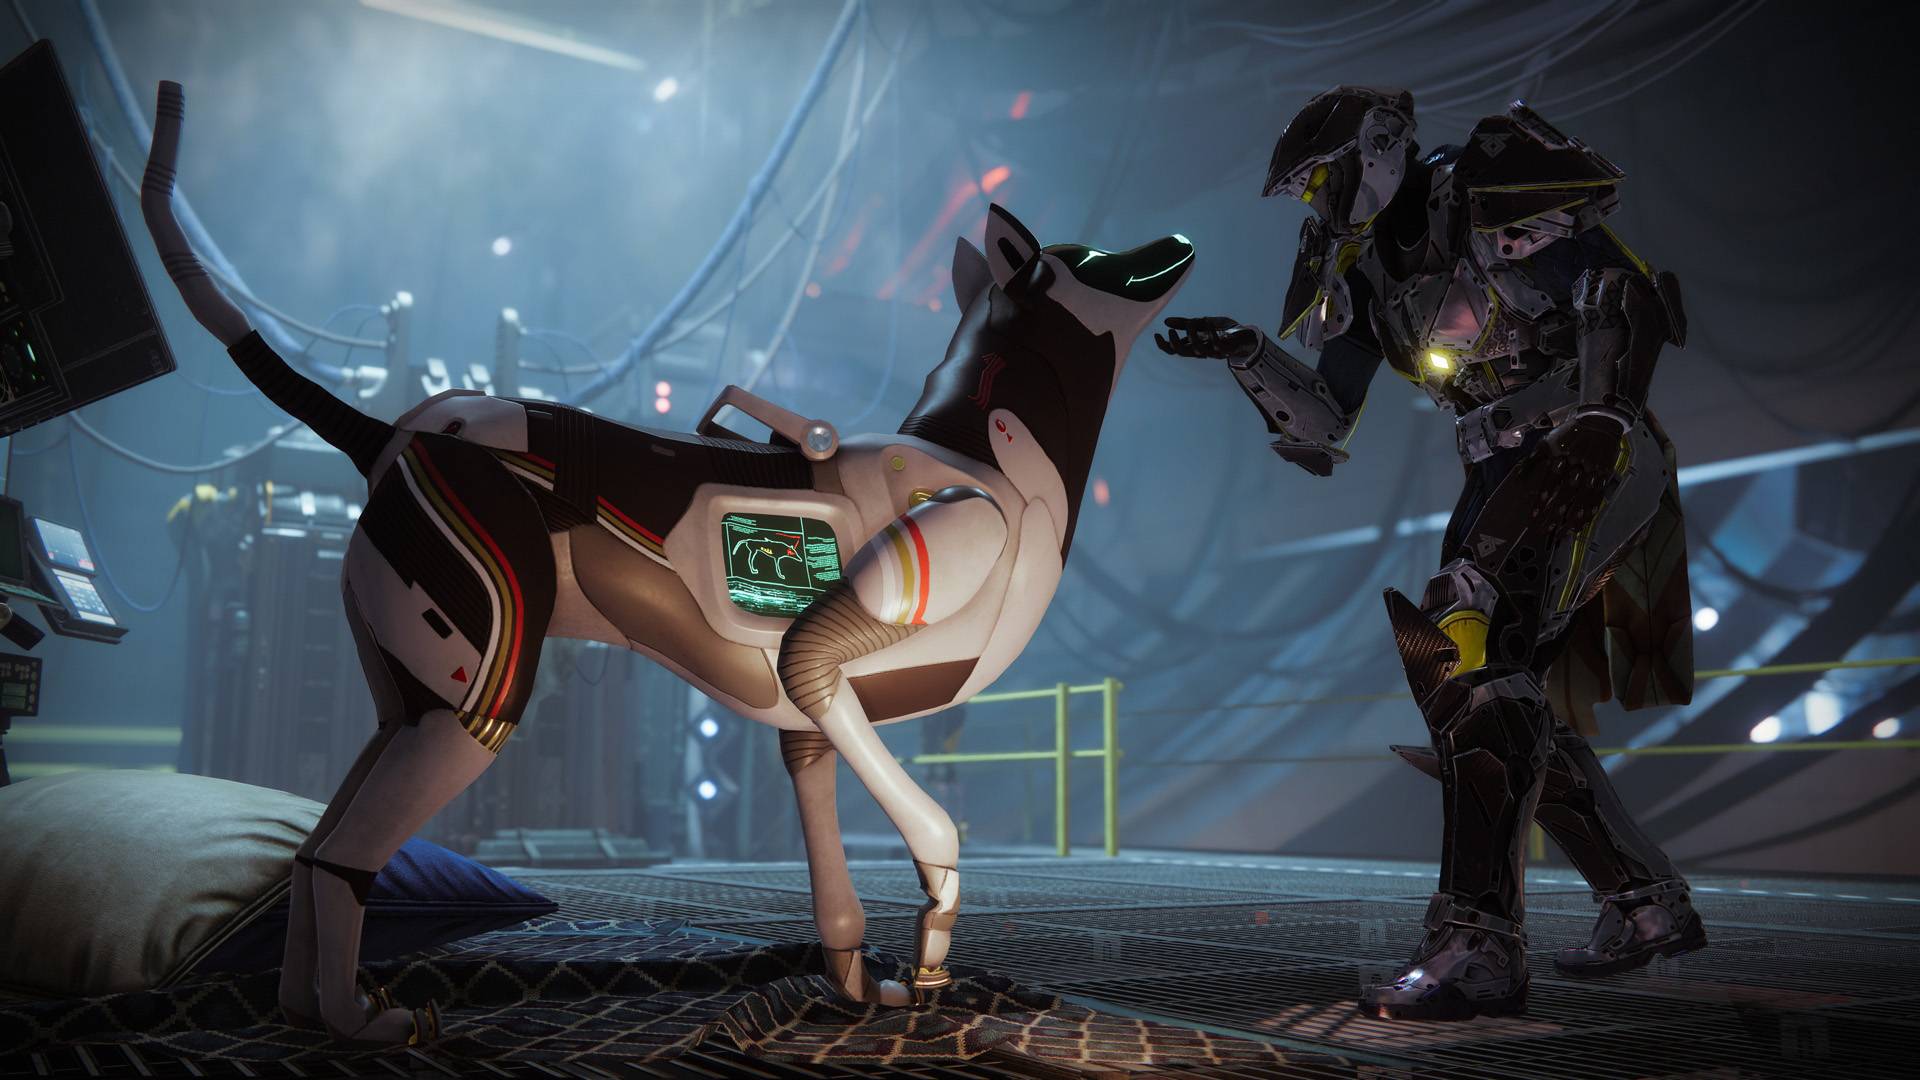
When many players come to a new Destiny 2 project, they are faced with a misunderstanding of the main mechanics – leveling and subclass systems, raids and strikes, content updates and others.
Owning real estate is one of the surest paths to passive income and even wealth. If you’re a real estate agent, you have an advantage most people don’t – you come across properties that would be great investments all the time. The problem is, even if you see all the best deals, it’s meaningless if you don’t have the capital to buy into them.
You would be surprised to find out that raising money for deals isn’t as much of an uphill battle as you might think. There are actually several strategies you can use to raise money to invest in real estate, and the best approach will depend on your individual situation and goals.
Here are some strategies that you may want to consider as you look for ways to raise money to invest in real estate:
Use Your Personal Savings
One of the simplest ways to raise money to invest in real estate is to use your own personal savings. If you have been saving money over time, you may be able to use these funds to make a down payment on a property or to cover other upfront costs associated with real estate investing. If you own your primary residence, your home equity is a bit like a secret savings account and you can tap into it to buy an investment property.
Take Out a Loan
Another option is to take out a loan to cover the costs of investing in real estate. There are several different types of loans that you may be able to use. As a real estate agent, you might qualify for a personal line of credit or loans for small businesses using the track record of your business entity to show your credibility. Keep in mind that you will need to have good credit and a solid financial history in order to qualify for most loans.
Partner With Other Investors
If you don’t have the funds to invest in real estate on your own, you may be able to find partners to invest with you. This can be a good way to share the risk and costs of investing in real estate. Just be sure to carefully vet any potential partners and to have a clear agreement in place before moving forward. Syndication is an investing model where up to 10 investors pool their resources, which allows them to buy bigger properties, even commercial ones. Joining a syndication group would allow you to get into an amazing deal without financially overexerting yourself.
Partner With Your Clients
As a real estate agent, you already have a wide database of people and a lot of them actually have capital to help you invest in real estate. In this current economy, most people are taking their money out of things like the stock market because they’ve become too volatile. You can offer those people a safer place to put their money. Whether you need cash for a short-term real estate deal or a long-term buy and hold, your own sphere of influence probably has people who would want to partner with you on deals, and you can very easily reach out to them letting them know you have a great deal. If you don’t have your own money to contribute to the deals, you can offer to do all the legwork, while they provide the capital. You can also offer the same thing to friends and family who have access to capital. For most people, the offer to grow their money without them doing any extra work will be an offer too good to pass up.
Consider Alternative Financing Options
There are also alternative financing options that you may be able to use to raise money. For example, you may be able to secure financing through a hard money lender.
Borrowing money from lenders like private money lender Miami is especially great if you’re doing a short-term flip where you can pay the money back before the interest skyrockets.
You could also consider a seller financing deal – this is where you pay the seller in installments instead of buying the home through a traditional mortgage. Make sure you’re 100% clear on the terms of these kinds of deals so that there’ll be no unpleasant fine print to come back to bite you.
Overall, there are many different strategies that real estate agents can use to raise money to invest in real estate. Don’t think that just because you don’t have the money yourself that you’ll never be able to get into an investment property. There are many sources you can tap into for the cash you need. By carefully considering your options and working with a financial advisor or other professional, you can find the best approach for your needs and goals.

In today’s world, having insurance has become a necessity. It is no longer an option but an essential part of our lives. Insurance provides us with a safety net in case of unforeseen events such as accidents, illnesses, or natural disasters. However, with so many types of insurance available, it can be overwhelming to choose the right one for your needs. Take a break from surfing on https://22bet.com.gh/ and read this insurance guide to help you out.
Insurance is a risk management technique that offers financial protection to individuals or organizations against the potential risks and damages associated with various unforeseen events. In simple terms, insurance provides the assurance of compensation for potential financial loss due to unexpected circumstances that are beyond the individual’s control.
Insurance policies are offered by insurance companies, which collect premiums from their clients in exchange for financial protection against various risks such as car accidents, fire, theft, natural disasters, and illness. Insurance companies utilize a pool of resources and expertise to estimate the potential risks, calculate the associated costs and create a policy that suits the client’s needs.
The fundamental principle of insurance is based on the law of large numbers, which states that the larger the number of participants in the insurance pool, the more accurate the predictions will be for future events. In this way, the insurance company can provide protection to its clients by spreading the risk across a larger group of people, which helps to keep the cost of premiums affordable.
Insurance is an essential tool that provides financial security to individuals and businesses. It helps to mitigate the financial burden that comes with unexpected events, making it an essential part of a well-planned financial strategy. With the right insurance coverage, people can have peace of mind knowing that they are financially protected, regardless of what life may throw their way.
Health insurance is one of the most important types of insurance that you should have. It covers the cost of medical expenses in case of illness or injury. With the rising costs of healthcare, having health insurance is essential to avoid financial hardship. Health insurance can be provided by your employer, or you can purchase it on your own. It is important to read the terms and conditions of the policy carefully to ensure that it covers your specific needs.
Life insurance is another important type of insurance that you should consider. The policy pays out a lump sum to your beneficiaries, which can be used to cover expenses such as funeral costs, mortgage payments, and other debts. There are two types of life insurance policies: term life insurance and permanent life insurance. Term life insurance is more affordable and provides coverage for a specific period, whereas permanent life insurance offers lifelong coverage and builds cash value over time.
Auto insurance is mandatory in most states, and for a good reason. It protects you financially in case of accidents involving your vehicle. Auto insurance covers the cost of repairs or replacement of your vehicle, medical expenses, and liability in case of damage to another person’s property. It is important to choose the right coverage for your needs and to review your policy periodically to ensure that it is up to date. [Read more…]
There are many different expenses that are associated with becoming a homeowner and it is so much more than just getting a mortgage for which you can afford the monthly payments. The VA loan program is one that is unique compared to the ‘traditional’ home buying route, which means that there are specific and innovative ways that you can save money while still getting what you want out of the mortgage program, way more ways than if you apply through other programs and systems.
Small business owners in the UK often face financial challenges that can impede their ability to grow and succeed. Potential solutions to these challenges are UK payday loans, a type of short-term loan that can provide quick access to cash when it is needed most. In this blog post, we will discuss the benefits of a payday loan for small business owners in the UK and how it can help them overcome financial obstacles.
Fast Approval and Funding
One of the main benefits of a payday loan is that it can be approved and funded quickly. This is important for small business owners who may need cash to cover unexpected expenses or to take advantage of a business opportunity. Unlike traditional bank loans, which can take weeks or even months to be approved, a payday loan can be approved and funded within 24 hours.
Flexibility
Another benefit of a payday loan is that it offers flexibility. Small business owners can choose the amount of money they need and the repayment terms that work best for them. This allows them to tailor the loan to their specific needs and budget.
No Collateral Required
Unlike traditional bank loans, a payday loan does not require collateral. This means that small business owners do not have to put up their personal assets as collateral in order to secure the loan. This is especially beneficial for small business owners who may not have a lot of assets to put up as collateral.
Easy to Qualify
A payday loan is also easy to qualify for. The eligibility criteria for a payday loan are less stringent than those for a traditional bank loan. This means that small business owners who may not have a strong credit history or financial statement can still qualify for a payday loan.
No Impact on Credit Score
Traditional bank loans can have a negative impact on a small business owner’s credit score, especially if the loan is not repaid on time. A payday loan, on the other hand, does not have a significant impact on a small business owner’s credit score. This is because the loan is not reported to the credit bureau.
A payday loan is a great option for small business owners who need cash quickly and don’t want to go through the hassle of applying for a traditional bank loan. It offers a fast and easy way to get the cash they need without the hassle of collateral or a credit check.
Helping During an Emergency
Sometimes, small business owners face unexpected emergencies that require immediate attention and cash. In such situations, a payday loan can be a lifesaver as it can provide quick access to cash to handle the emergency.
Payday loans can also be used to purchase inventory, pay bills, and cover other expenses that are critical to the success of a small business.
Always an Available Option
A payday loan can be an excellent option for small business owners in the UK who need cash quickly and don’t want to go through the hassle of applying for a traditional bank loan. It offers a fast, flexible, and easy way to get the cash they need without the hassle of collateral or a credit check. However, it is important to keep in mind that payday loans often come with higher interest rates, so it is important to carefully consider the terms and conditions of the loan before applying for it.
If you’ve decided to form a corporation or a limited liability company (LLC), you’ve probably come across the term ‘registered agent.’
A registered agent is an individual or entity whose job is to receive government, legal, and tax correspondence on behalf of the LLC or corporation and relay them to the owner. When registering your business with the state, you need a registered agent as part of the registration requirements.
Here’s more of what you need to know about a registered agent and when you will need one.
What Is A Registered Agent?
A registered agent is a person or a company that serves as the point of contact for business entities like corporations, limited liability companies, limited partnerships, and limited liability partnerships. Through a registered agent, the court, government, and the public can reliably reach out to a corporation or LLC.
However, it’s essential to know that you can’t just hire anyone. The right one for the job should be able to meet the following criteria: