• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for tax rules

Regulation Echo: 10 Under-the-Radar Rules Affecting Future Wealth

December 22, 2025 by Brandon Marcus Leave a Comment

Regulation Echo: 10 Under-the-Radar Rules Affecting Future Wealth
Image Source: Shutterstock.com

Money doesn’t just grow or shrink because of markets, luck, or hustle—it responds to rules quietly humming in the background. While headlines scream about interest rates and stock swings, a softer but more powerful force keeps shaping who wins, who waits, and who wonders what happened. These are the regulations most people never notice until they feel the consequences in their savings, investments, or retirement plans.

They aren’t flashy, and they rarely trend on social media, but they influence wealth the way gravity influences motion. Get ready, because once you notice these echoes, you’ll never hear the financial system the same way again.

1. Retirement Account Contribution Limits

These caps seem harmless, even responsible, but they quietly decide how much tax-advantaged wealth you’re allowed to build each year. High earners often hit these ceilings quickly, forcing excess money into taxable accounts with less favorable treatment. Over decades, that difference can mean hundreds of thousands of dollars lost to frictional taxes. Contribution limits also lag inflation, subtly shrinking their real value over time. What looks like a simple number is actually a throttle on long-term compounding.
Regulation Echo: 10 Under-the-Radar Rules Affecting Future Wealth
Image Source: Shutterstock.com

2. Required Minimum Distribution Rules

RMDs dictate when the government expects you to start withdrawing retirement funds, whether you need the money or not. These forced withdrawals can push retirees into higher tax brackets at precisely the moment they hoped for simplicity. They also limit how long tax-deferred assets can grow untouched. Recent adjustments raised the age slightly, but the underlying pressure remains. The rule quietly nudges retirees from growth mode into tax-management mode.

3. Capital Gains Holding Period Definitions

That one-year line between short-term and long-term gains carries more power than most realize. Selling an asset a day too early can double the tax bill on profits. This encourages timing decisions that may not align with market realities or personal goals. Over time, the rule shapes behavior, not just tax outcomes. Wealth often rewards patience, but the regulation decides how patience is defined.

4. Estate Tax Exemption Thresholds

These thresholds rise and fall with political winds, making long-term planning a moving target. Families who plan under one assumption may face a very different reality a decade later. Even those well below the federal limit can be caught by state-level estate taxes. The uncertainty itself becomes a hidden cost, pushing people toward complex planning strategies. Inheritance outcomes are often decided years before a will is ever read.

5. Accreditation Rules For Private Investments

To access many private deals, you must meet income or net-worth standards set by regulation. These rules aim to protect investors, but they also gatekeep high-growth opportunities. Those just below the cutoff are locked out regardless of experience or sophistication. Over time, this can widen wealth gaps by reserving certain returns for a select group. The rule quietly decides who gets invited into the most exclusive rooms in finance.

6. Housing Zoning And Land-Use Regulations

Local zoning laws heavily influence property values, often more than the condition of the home itself. Restrictions on density can inflate prices by limiting supply. Homeowners benefit while renters struggle to enter the market. These rules can turn geography into destiny for wealth accumulation. Real estate fortunes are often built on paperwork long before bricks are laid.

7. Student Loan Repayment Structures

Repayment rules determine how long educational debt lingers and how expensive it becomes over time. Income-driven plans can lower payments but extend balances for decades. Interest capitalization quietly inflates what borrowers actually repay. These structures influence when people buy homes, invest, or start businesses. The rulebook shapes not just debt, but life timelines.

8. Social Security Benefit Calculations

Benefit formulas reward certain earnings patterns more than others, often favoring long, steady careers. Those with gaps, caregiving years, or nontraditional work paths may receive less than expected. The rules are complex enough that many never optimize their claiming strategy. Timing decisions can swing lifetime benefits by six figures. What feels like a safety net is actually a puzzle with high financial stakes.

9. Tax Treatment Of Side Income

Gig work and side hustles face different reporting and tax obligations than traditional wages. Self-employment taxes surprise many first-time earners. Deductions exist, but only for those who understand the rules well enough to claim them properly. Over time, missteps erode the extra income these ventures promise. The regulation determines whether a side hustle builds wealth or quietly drains it.

10. Inflation Indexing Rules

Not all financial thresholds adjust for inflation, and that omission matters more every year. Tax brackets may move, but deductions, credits, and exemptions often lag behind. This creates “stealth tax increases” without new legislation. As purchasing power shifts, so does the real impact of old numbers. Inflation indexing decides whether rules age gracefully or grow harsher over time.

Listening To The Echoes

Wealth isn’t shaped only by what you earn or invest, but by the rules that quietly steer outcomes in the background. These under-the-radar regulations don’t announce themselves, yet they influence decisions at every stage of life. Paying attention to them can mean the difference between reacting too late and planning ahead with confidence.

Everyone has a moment when a small rule made a big difference in their financial story. We’d love to hear your experiences, insights, or perspectives in the comments section below.

You May Also Like…

Legacy Risk: 6 Estate Myths That Put Families in Financial Danger

Funding Gap: 8 Ways Rising College Costs Are Changing Mid-Life Financial Planning

Legacy Debt: 5 Family Conversations That Help Prevent Wealth From Becoming a Burden

Legacy Trap: How Your Kids Might Inherit More Tax Than Wealth Without Realizing It

Deadline Countdown: 11 Smart Moves Every Wealth-Seeker Should Do in December


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Wealth Building Tagged With: capital gains, estate tax, invest, investing, investments, money rules, Required Minimum Distributions, retirement account, retirement contribution, tax rules, taxes, Wealth, Wealth Building

Estate Overhaul: 10 Document Updates to Make Before New Tax Rules Kick In

December 15, 2025 by Brandon Marcus Leave a Comment

Here Are 10 Document Updates to Make Before New Tax Rules Kick In
Image Source: Shutterstock.com

The clock is quietly ticking, and most people don’t even hear it. While headlines scream about markets, elections, and tech trends, major tax rule changes often sneak in through the side door, reshaping estates before families realize what happened. An outdated estate plan isn’t just paperwork collecting dust—it can be a financial landmine waiting for heirs to step on it.

The good news is that a proactive update now can mean clarity, savings, and fewer headaches later. Think of this as a strategic tune-up for your legacy, done while you still control the wheel.

1. Update Your Will

Your will is the backbone of your estate plan, but tax law changes can quietly weaken it if it hasn’t been reviewed in years. Shifts in exemption amounts and tax thresholds can turn once-smart distributions into costly mistakes. An updated will ensures your assets pass efficiently, not expensively. It also helps eliminate ambiguity that could spark family disputes. Even small wording tweaks can make a massive difference under new tax rules.

Here Are 10 Document Updates to Make Before New Tax Rules Kick In
Image Source: Shutterstock.com

2. Review Your Revocable Living Trust

Revocable living trusts are popular for avoiding probate, but they are not “set it and forget it” documents. New tax rules may change how trust income or distributions are taxed. Reviewing beneficiary provisions now can help preserve flexibility later. Trustees also need updated guidance that aligns with current laws. A modernized trust keeps control where you intended it to be.

3. Refresh Beneficiary Designations

Retirement accounts and life insurance policies don’t care what your will says—they follow beneficiary forms. Tax rule changes, especially around inherited retirement accounts, can dramatically impact how and when beneficiaries pay taxes. An outdated designation could create unexpected tax bills or disqualify planning strategies. This is one of the easiest updates to make and one of the most commonly overlooked. A quick review now can prevent years of regret later.

4. Amend Powers Of Attorney

Financial powers of attorney allow someone else to act on your behalf, but tax law changes can limit or expand what they should be allowed to do. Older documents may not grant authority for newer planning strategies or filings. Updating this document ensures your agent can respond quickly if laws shift again. It also helps prevent delays during critical moments. Strong authority paired with clear limits is the sweet spot.

5. Update Health Care Directives

While health care directives aren’t tax documents, they often intersect with financial decisions during incapacity. New rules around long-term care costs and benefits can influence estate outcomes. Updating directives ensures your wishes align with today’s financial realities. It also reduces confusion during emotional situations. Clear instructions now mean fewer rushed decisions later.

6. Revisit Gifting Strategy Documents

Annual and lifetime gift exemptions are frequent targets for tax reform. Documents supporting gifting strategies may no longer match current limits or reporting requirements. Updating these ensures gifts remain tax-efficient and properly documented. It also helps beneficiaries understand the intent behind transfers. Smart gifting is about timing as much as generosity.

7. Modify Trusts For Minor Or Special Needs Beneficiaries

Trusts designed for children or special needs beneficiaries must stay compliant with evolving tax and benefit rules. An outdated structure could accidentally disqualify someone from assistance or increase tax exposure. Reviewing these trusts protects both financial support and eligibility. Adjustments now can preserve benefits for decades. This is where precision truly matters.

8. Review Business Succession Documents

If you own a business, estate tax changes can directly affect succession plans. Buy-sell agreements and valuation methods may no longer produce the desired tax results. Updating these documents helps protect both the business and your family. It also provides clarity to partners or co-owners. A well-timed update can be the difference between continuity and chaos.

9. Reassess Charitable Giving Plans

Charitable trusts and donor-advised funds are sensitive to tax law changes. New deduction limits or valuation rules can alter the benefits you expected. Updating documents ensures your generosity remains impactful and efficient. It also keeps charities from facing administrative complications later. Thoughtful updates allow philanthropy to remain a win for everyone involved.

10. Consolidate And Organize Supporting Documents

Estate plans don’t live in isolation—they rely on deeds, titles, account statements, and contracts. New tax rules can expose gaps or inconsistencies across these materials. Consolidating and updating everything creates a clearer financial picture. It also makes administration far easier for heirs. Organization is an underrated but powerful estate planning tool.

Your Move, Before The Rules Do

Estate planning isn’t about predicting the future perfectly—it’s about staying adaptable when the rules change. Updating documents before new tax laws take effect gives you leverage, clarity, and peace of mind. It also spares loved ones from confusion and costly surprises during already difficult times. An estate overhaul today is an act of responsibility and care tomorrow.

Share your thoughts, experiences, or planning stories in the comments section for others to learn.

You May Also Like…

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

Should You Make A Roth Conversion Now Or Wait For January’s Tax Environment To Settle?

9 Financial Dangers of Ignoring Property Taxes

What Happens When Retirement Plans Ignore Rising Taxes

Why Do Middle-Class Families End Up Paying the Most Taxes


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: beneficiary, charitable contributions, charity, Estate plan, Estate planning, family trusts, healthcare, important documents, live trust, powers of attorney, Tax, tax rules, taxes, trusts, will and testament

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

December 9, 2025 by Brandon Marcus 2 Comments

Here Are The Georgia Counties Where Property Taxes Are Set to Rise the Fastest
Image Source: Shutterstock.com

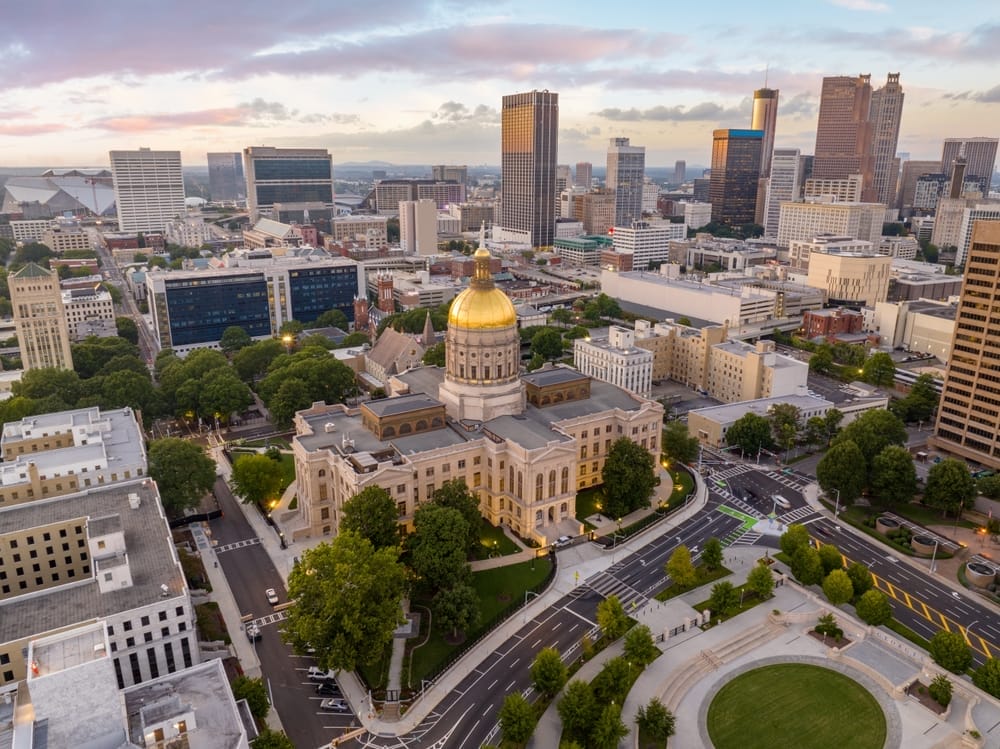
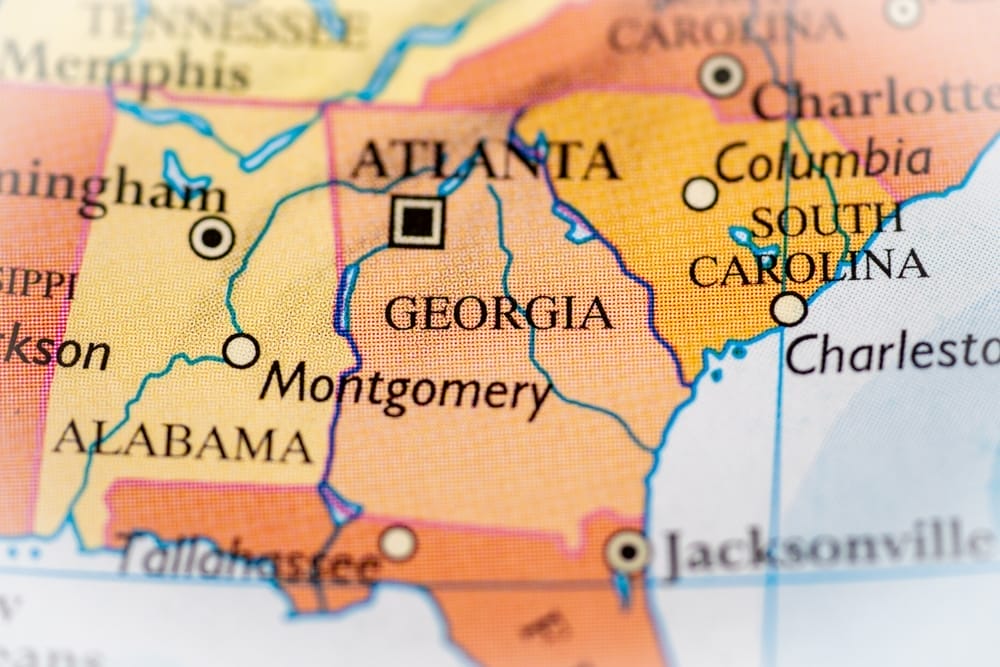
Let’s dive right in — if you own property in Georgia (or you’re house-hunting), buckle up. Home values are shooting up across parts of the state, and that means for many homeowners, the property tax bill that lands in your mailbox this year could hit a lot harder than last year. Between rapidly rising assessments, shifting millage rates, and local governments scrambling to keep up with growth (or budget shortfalls), there are several counties where taxes are on track to climb faster than you might expect.

Here are nine Georgia counties to watch if you care about what your home will cost you — and what you might start paying soon.

1. DeKalb County

DeKalb County is practically waving a red flag when it comes to rising tax burdens in 2025. The county’s governing authority has approved a tentative millage rate of 12.427 mills — that’s 2.690 mills over the computed “rollback” rate, representing a 27.6 percent increase from what the rollback formula would dictate. Even though the combined rate for all levies has been held flat at 20.81 mills since 2015, the reassessment of property values means many homeowners are still looking at significantly larger tax bills.

For those living in parts of metro Atlanta where housing demand has exploded — and with schools, public services, and infrastructure under pressure — the jump in tax obligations feels like the price tag for growth. If your property was reassessed upward even a little, that 27% swing could hit harder than it looks on paper.

2. Cobb County

Cobb County remains one of Georgia’s fastest-growing suburban hubs, and with growth comes rising home values — and rising taxes. According to the 2025 residential property value report, the market value of single-family homes rose about 3.1 percent compared to 2024. That’s not the kind of jump that knocks you off your feet overnight — but consistent annual increases add up over time, especially when many homeowners already operate on tight margins or fixed incomes.

The ripple effect? Expect next year’s tax digest (and likely your bill) to reflect the new valuations. As properties change hands or get upgraded, it’s a reminder that suburban expansion often comes with a hidden cost.

3. Fulton County

In the heart of metro Atlanta, Fulton County continues to see some of the steepest home-value gains statewide — and that typically translates directly into steeper taxes. A recent report showed residential property values increased by 5.9 percent overall, with even bigger upswing among higher-valued homes. It’s not just luxury mansions driving the spike either; mid-range properties saw solid upward movement, pushing more “average” homeowners into new tax brackets.

The truth is, when demand is high and inventory is tight, tax assessments follow market prices — and that upward pressure tends to stick. For many long-time residents, this can feel like being priced out of your own neighborhood without ever moving.

Here Are The Georgia Counties Where Property Taxes Are Set to Rise the Fastest
Image Source: Shutterstock.com

4. Gwinnett County

Though not always in the headlines, Gwinnett County in recent years has seen rapid population growth and mounting development. As demand pushes property values upward, tax bills are likely to follow. In recent statewide property-tax data, Gwinnett had among the highest effective tax burdens for homeowners. This county is part of the broader metro-Atlanta growth wave — new homes, families moving in, and expanding services. With schools, roads, and infrastructure needing funding, officials often lean on property tax increases to keep pace. If you own in Gwinnett and haven’t looked at your latest assessment closely — now might be a good time.

5. Chatham County

Way out on the coast, things are heating up in Chatham County too. As home to the city of Savannah and its surrounding suburbs, Chatham is seeing rising demand for housing — which tends to push up property valuations. According to the latest county-by-county data, Chatham’s effective property tax rate and median tax bills are among the higher ones in Georgia. For coastal homeowners, rising property taxes can clash with other cost pressures like insurance, maintenance, and flood-related expenses. If you own a home in this region, prepare for what could be a steeper climb than many inland counties are facing.

6. Fayette County

Fayette County is often overlooked in discussions about tax spikes, but it’s a place where property value increases and tax burdens have quietly climbed. According to recent data, many mid-sized Georgia counties like Fayette are seeing rising effective tax rates and increased tax bills, even as statewide attention focuses on the major metros. For long-term homeowners, that can mean incremental increases over successive years — enough to shift what was once a manageable payment into a financial burden. Communities that had affordable charm a few years back may now feel the squeeze as valuations edge upward and local government costs rise.

7. Henry County

Henry County, which sits on the growing periphery of metro Atlanta, is another spot where homeowners should keep a close eye. As development expands outward and more people move in, property values tend to follow — and with that, tax bills often climb too. Tax data show that Henry County’s effective property tax burden is already above the statewide median. For families moving into what once felt like affordable suburbs, this means the dream of lower-cost living might be under threat from rising assessments and incremental tax pressure. New growth brings new amenities — but also new expenses.

8. Coweta County

Few counties outside the big metro centers get much attention, but Coweta County is quietly part of the broader shift. As people look for more space and affordability outside major urban zones, places like Coweta become magnets — which can trigger property value hikes. According to recent property-tax data sets, Coweta shows a relatively high effective rate, suggesting that as home values rise, tax bills are likely to follow. This dynamic often sneaks up on homeowners: the neighborhood feels peaceful, the home feels like your refuge, but the tax bill creeping up in your mailbox tells a different story. If you call Coweta home — or are thinking about buying there — it’s worth budgeting for steeper taxes down the line.

9. Butts County

Last but not least, Butts County stands out among Georgia’s smaller and more rural counties, yet it shows signs of rising tax burden that many might not expect. According to county-by-county effective property tax data, Butts is among the counties where rates — relative to property values — are trending upward. As urban sprawl pushes outward, even rural zones can feel the ripple effect of increased demand, leading to reassessments and higher bills. For homeowners who moved here for peace, space, or affordability, that tax increase can sting: what once felt affordable might suddenly feel like a stretch.

What This Means For Georgia Homeowners

If you own — or are thinking of buying — a home in Georgia, these counties show that the property-tax landscape is shifting quickly. Rising home values, population growth, and local budget pressures are colliding to make increases more common than exceptions. It’s a reminder that homeownership isn’t just about your mortgage and that property taxes can sneak up and add real impact to your bottom line.

Have you seen a jump in your latest tax bill? Are you feeling the squeeze — or moving because of it? We want to hear your story. Drop your experience, tips, or frustrations in the comments below.

You May Also Like…

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

Can Your Taxes Be Cut In Half By You Simply Incorporating Your Name?

5 Reasons Why Homeowners Should Increase Their Property’s ROI

9 Financial Dangers of Ignoring Property Taxes

7 Lesser-Known Costs of Selling Inherited Property


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: Butts County, Chatham County, Cobb County, Coweta County, DeKalb County, Fayette County, Fulton County, Georgia, Gwinnett County, Henry County, property tax, property taxes, tax rules, taxes

10 Lesser-Known Tax Rules That Cost Households Big Money

August 31, 2025 by Travis Campbell Leave a Comment

tax
Image source: pexels.com

Tax season can feel overwhelming, especially when you realize how many tax rules are tucked away in the fine print. Many households miss out on savings or end up paying more than they should because they don’t know about certain lesser-known tax rules. These overlooked details can quietly drain your wallet year after year. Understanding them is key to keeping more of your hard-earned money. Let’s break down 10 of the most important lesser-known tax rules that cost households big money—and what you can do about them.

1. The Kiddie Tax on Unearned Income

Think your child’s investment gains are taxed at their lower rate? Not always. The “kiddie tax” applies when children under 19 (or under 24 if full-time students) have unearned income above a set threshold. That income can be taxed at your higher rate, not theirs. Many parents are surprised when their kids’ summer dividends push them into a higher tax bracket. To avoid an unexpected bill, monitor all investment accounts in your child’s name.

2. Limits on State and Local Tax Deductions (SALT Cap)

The IRS limits the deduction for state and local taxes to $10,000 per year ($5,000 if married filing separately). If you live in a high-tax state, this rule can raise your federal tax bill by thousands. Households with high property taxes are especially affected. Consider this cap when budgeting for homeownership or evaluating your overall tax strategy.

3. Mortgage Interest Deduction Changes

Many homeowners count on the mortgage interest deduction, but recent changes mean only interest on up to $750,000 of mortgage debt is deductible for loans taken after December 15, 2017. If you bought a home before that date, you may qualify under the old $1 million limit. Refinancing or moving could impact your eligibility, so check the details before making big decisions.

4. The Alternative Minimum Tax (AMT)

The Alternative Minimum Tax was designed to prevent wealthy taxpayers from avoiding taxes, but it can affect upper-middle-class households, too. Certain deductions like state taxes and miscellaneous expenses are not allowed under AMT, which can lead to a higher tax bill than expected. If you regularly exercise incentive stock options or claim a large number of deductions, check whether you may be subject to the AMT. This is one of those lesser-known tax rules that cost households big money without warning.

5. Taxation of Social Security Benefits

Many retirees are surprised to learn that up to 85% of their Social Security benefits may be taxable, depending on their total income. If you have other sources of income—like pensions, part-time work, or withdrawals from retirement accounts—those can push you over the threshold. Planning withdrawals carefully can help reduce the tax hit on your benefits.

6. Penalties for Early Retirement Account Withdrawals

Need to tap your IRA or 401(k) before age 59½? Unless you qualify for a specific exception, you’ll pay a 10% penalty on top of regular income tax. Some exceptions exist, like for first-time homebuyers or certain medical expenses, but the rules are strict. Failing to plan withdrawals properly is one of those lesser-known tax rules that cost households big money, especially during emergencies.

7. The “Wash Sale” Rule for Capital Losses

If you sell a security at a loss and buy it back within 30 days, the IRS disallows the loss for tax purposes. This is called the “wash sale” rule. Many investors accidentally trigger this rule when trying to harvest tax losses. To avoid losing out on valuable deductions, wait the full 30 days before repurchasing the same or substantially identical investment.

8. Taxation of Health Savings Account (HSA) Withdrawals

HSAs provide excellent tax benefits, but only if you use withdrawals for qualified medical expenses. Non-qualified withdrawals before age 65 are subject to income tax and a 20% penalty. After age 65, you can withdraw for any reason without a penalty, but non-medical withdrawals are still taxed as income. Keep good records and save receipts to avoid costly mistakes.

9. Missed Education Credits

Education credits like the American Opportunity Tax Credit and Lifetime Learning Credit can shave thousands off your tax bill. But many households miss out by not claiming expenses or misunderstanding eligibility. For example, you can’t double-dip by claiming both credits for the same student.

10. Dependent Care FSA Forfeitures

If you contribute to a Dependent Care Flexible Spending Account, unused funds generally don’t roll over. If you don’t use the money by the deadline, you lose it. Many families overestimate their dependent care expenses, leaving hundreds or thousands on the table. Plan contributions carefully and track expenses throughout the year to maximize these tax benefits.

How to Avoid These Costly Tax Surprises

Staying informed about lesser-known tax rules that cost households big money can make a huge difference in your annual tax bill. Small missteps add up fast, while a little research and planning can keep more money in your pocket. Tax laws change often, so it’s wise to review your situation every year and consult trusted resources like the IRS website or a qualified tax professional.

What confusing tax rules have caught you off guard? Share your experiences or questions in the comments below!

What to Read Next…

  • 7 Tax Breaks That Sound Generous But Cost You Later
  • 6 Tax Breaks That Vanished Before Anyone Noticed
  • 5 Ways Missing One Tax Form Can Cost Your Heirs Thousands
  • 6 Tax Moves That Backfire After You Sell A Property
  • What Tax Preparers Aren’t Warning Pre Retirees About In 2025
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: tax tips Tagged With: household taxes, Personal Finance, retirement planning, Tax Deductions, tax rules

  • « Previous Page
  • 1
  • 2

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework