• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for community development

Treasury Opens $5 Billion New Markets Tax Credit Round to Drive Investment in Low-Income Communities

September 16, 2026 by Amanda Blankenship Leave a Comment

New Markets Tax Credit 2026
The Treasury Department’s CDFI Fund is making $5 billion in New Markets Tax Credit allocation authority available for 2026 to help attract private investment into low-income and economically distressed communities. Fishman64/Shutterstock

The U.S. Department of the Treasury is opening a new $5 billion round of a federal tax-credit program designed to attract private investment into economically distressed communities.

Treasury’s Community Development Financial Institutions Fund announced the Calendar Year 2026 round of the New Markets Tax Credit Program in a Federal Register notice published September 15.

Organizations seeking an allocation face several deadlines, including a November 10, 2026, deadline for the full application.

The $5 Billion Isn’t a Pool of Direct Grants

The New Markets Tax Credit Program works differently from a traditional federal grant program.

Through the New Markets Tax Credit Program, the CDFI Fund gives certified Community Development Entities, or CDEs, authority to offer federal tax credits to investors who make qualifying equity investments.

Those CDEs then use the investment capital to finance eligible businesses and projects in low-income communities.

The federal tax credit totals 39% of the original qualified investment and is claimed over seven years. Investors generally claim 5% in each of the first three years and 6% in each of the following four years.

That means the newly announced $5 billion represents the amount of equity investment authority for which New Markets Tax Credits may ultimately be claimed—not $5 billion that Treasury will distribute directly to businesses or communities as grants.

The Program Has Financed Businesses and Community Projects

Congress created the New Markets Tax Credit Program in 2000 to encourage investment in communities that historically have had difficulty attracting private capital.

According to the CDFI Fund’s program overview, eligible investments have helped finance businesses and projects serving distressed communities.

The CDFI Fund says that through fiscal year 2023, the program generated about $8 in private investment for every $1 of federal funding and supported the construction or rehabilitation of more than 268 million square feet of commercial real estate.

Projects financed through the program can include operating businesses as well as facilities and services serving low-income communities.

The program does not mean that every business located in a low-income area automatically qualifies for a tax credit. Investments must flow through qualified Community Development Entities and meet detailed federal requirements.

Treasury Has $5 Billion Available for the 2026 Round

The Federal Register notice for the 2026 allocation round makes $5 billion in New Markets Tax Credit allocation authority available.

The CDFI Fund anticipates awarding individual allocatees up to $100 million in tax-credit investment authority.

However, that isn’t an absolute cap or a guaranteed award amount.

The agency says it may award more or less than $100 million when it determines doing so is appropriate, and it retains discretion to make allocations to any, all, or none of the organizations that apply.

Awards are therefore competitive rather than automatic.

Congress Made the $5 Billion Annual Program Permanent

The 2026 round follows a significant change to the future of the program.

The New Markets Tax Credit had previously been extended by Congress for limited periods, creating uncertainty about whether the program would continue after its existing authorization expired.

The One Big Beautiful Bill Act of 2025 permanently extended the New Markets Tax Credit and provided $5 billion in annual allocation authority beginning in 2026.

That means the current $5 billion round isn’t simply another short-term extension of the program.

The CDFI Fund’s 2026 notice cites the 2025 law as the authority for the $5 billion available in this year’s allocation round.

Applicants Face Several Deadlines

Organizations interested in the 2026 allocation can’t wait until November to begin the process.

The CDFI Fund has established several critical deadlines:

  • September 22, 2026, at 11:59 p.m. ET: CDE certification applications and certain certification/service-area requests
  • October 6, 2026, at 5 p.m. ET: Allocation Application Registration
  • November 3, 2026, at 11:59 p.m. ET: Certain allocation-agreement amendment requests
  • November 6, 2026, at 5 p.m. ET: Last day to contact CDFI Fund staff with application questions
  • November 10, 2026, at 5 p.m. ET: Full CY 2026 Allocation Application and required attachments

Applications and related submissions are handled electronically through the CDFI Fund’s Awards Management Information System, or AMIS.

Importantly, an organization that fails to complete the required application registration by October 6 won’t be able to subsequently submit a 2026 allocation application.

Certification Rules Also Changed for This Round

Treasury highlighted two notable program changes for the 2026 round.

First, prior New Markets Tax Credit allocatees face revised minimum requirements involving the issuance of Qualified Equity Investments and the closing of Qualified Low-Income Community Investments tied to earlier allocations.

Second, applicants must meet new timing requirements involving CDE certification.

To be considered for a 2026 allocation, an applicant generally must either already be certified as a Community Development Entity as of the Federal Register publication date or submit its CDE certification application through AMIS by the September 22 deadline.

The CDFI Fund says it won’t provide allocation authority to applicants that ultimately aren’t certified as CDEs.

Some Prior Allocatees Face January 2027 Deadlines

The application deadline isn’t the only date organizations participating in the program need to watch.

Certain prior allocatees subject to Qualified Equity Investment issuance and Qualified Low-Income Community Investment requirements have until January 7, 2027, at 11:59 p.m. ET to meet the applicable thresholds.

The deadline to report those QEIs and certify the required QLICIs through AMIS is January 14, 2027, at 11:59 p.m. ET.

Those deadlines are particularly relevant to organizations with earlier New Markets Tax Credit allocations because satisfying prior-round requirements can affect eligibility in the new competition.

Organizations considering an application should review the complete CDFI Fund New Markets Tax Credit application materials rather than relying only on the headline November deadline.

With $5 billion in new allocation authority available and the program now permanently extended, the 2026 round represents the beginning of a new phase for a tax incentive that has been directing private investment toward low-income communities for more than two decades.

What to Read Next

Treasury Yields Are Rising. Why Should Someone Who Doesn’t Own a Treasury Care?

The Fed Decides September 16—The 3 Accounts That Reprice Within 48 Hours, and the 4 That Take Months

Treasury Proposes New Stablecoin Rules Under GENIUS Act — Here’s Who Could Be Affected

Headshot of Amanda Blankenship
Amanda Blankenship

Amanda Blankenship is the Chief Editor for District Media.  With a BA in journalism from Wingate University, she frequently writes for a handful of websites and loves to share her own personal finance story with others. When she isn’t typing away at her desk, she enjoys spending time with her daughter, son, husband, and dog. During her free time, you’re likely to find her with her nose in a book, hiking, or playing RPG video games.
Filed Under: news Tagged With: CDFI Fund, community development, Federal Programs, Low-Income Communities, New Markets Tax Credit, Small business, tax credits, U.S. Treasury

How Can Rich vs. Poor Shopping Habits Predict Local Economies

September 2, 2025 by Catherine Reed Leave a Comment

How Can Rich vs. Poor Shopping Habits Predict Local Economies
Image source: 123rf.com

When economists study communities, they often look at employment data, housing prices, and business growth. Yet, one of the most revealing indicators comes from something people do every day: shopping. The way individuals spend money, from luxury items to discount essentials, provides insight into the financial health of entire neighborhoods. Shopping habits don’t just reflect personal income levels; they also shape and predict the strength of local economies. By comparing how the rich and poor shop, we can better understand where communities are headed financially.

1. Where People Shop Tells a Bigger Story

One of the clearest signals comes from where people choose to shop. Affluent households often spend money at specialty stores, boutiques, and higher-end grocery chains, which attract further business investment. Lower-income households, on the other hand, tend to rely on discount retailers, dollar stores, and bulk shopping clubs. These patterns of shopping habits determine which businesses thrive in a given area. Over time, the mix of stores in a community becomes a direct reflection of its overall economic strength.

2. Spending on Experiences vs. Essentials

Another key difference in shopping habits is whether households spend more on experiences or essentials. Wealthier families are more likely to purchase dining, travel, and entertainment, injecting money into service-oriented businesses. Poorer families often allocate a greater share of income to necessities like food, clothing, and utilities. While both forms of spending support local economies, experience-based spending usually generates more tax revenue and job diversity. The balance between essentials and experiences reveals the financial flexibility of a community.

3. Credit Use and Debt Impact Local Economies

How people pay for their purchases is another economic clue. Wealthier shoppers are more likely to use credit strategically, paying balances in full to earn rewards. Lower-income shoppers often rely on credit out of necessity, which can lead to revolving debt and higher interest payments. These shopping habits influence the local economy by affecting consumer confidence and long-term spending power. Communities with high debt reliance often face slower economic growth compared to those with healthier financial practices.

4. The Role of Big-Box vs. Small Businesses

The choice between shopping at big-box retailers or supporting local businesses highlights broader economic patterns. Wealthier shoppers often split their spending, using large retailers for convenience but also supporting niche local stores. Lower-income households may lean heavily on big-box or chain stores for affordability. These shopping habits impact the survival of small businesses, which are often critical for local job creation and tax revenue. The strength of small businesses within a community is a powerful predictor of local economic resilience.

5. The Effect of Online Shopping Growth

The rise of e-commerce has widened the gap between rich and poor shopping habits. Affluent shoppers often use online platforms for both luxury goods and everyday purchases, supporting national and global brands. Lower-income shoppers may stick to in-store purchases for essentials, partly due to lack of access to credit or delivery services. This difference in habits shapes whether local economies lose money to outside corporations or keep it circulating within the community. The level of online vs. local spending offers a forecast of future economic development.

6. How Savings and Bulk Purchases Shape Spending

Wealthier families often buy in bulk, not just for savings but also for convenience. This strategy reduces per-unit costs and helps stretch long-term budgets. Lower-income households, however, frequently purchase smaller quantities, even though it costs more per unit, simply because cash flow is tighter. These shopping habits create a cycle where wealthier households save more while poorer households spend more on the same items. Over time, this imbalance contributes to widening economic divides within local communities.

7. Indicators from Luxury vs. Discount Growth

The presence and growth of luxury stores versus discount retailers can predict where an economy is headed. When luxury shops and upscale grocery chains open in a neighborhood, it signals rising incomes and investment potential. Conversely, a surge in discount retailers often points to economic stress in the community. These shifts in retail presence stem directly from consumer shopping habits. For policymakers and investors, they serve as an early warning system of local financial health.

8. Shopping Habits and Community Stability

Beyond economics, shopping patterns also influence community stability. Wealthier households, with more discretionary spending, often support arts, culture, and charitable donations tied to their shopping behaviors. Lower-income households, focused on survival spending, may not have the same opportunities to invest in community enrichment. This creates visible differences in how neighborhoods develop socially and economically. Shopping habits, therefore, act as both a reflection and a driver of community well-being.

The Economic Story Hidden in Every Purchase

Every purchase tells a story, not just about personal budgets but about the health of entire communities. The contrast between rich and poor shopping habits highlights which areas are growing, which are struggling, and where the future may be headed. By paying attention to where people shop, what they buy, and how they pay, we can better predict local economic shifts. These insights remind us that small daily choices can have large collective impacts on community prosperity.

Do you think shopping habits reveal more about a local economy than official statistics? Share your thoughts in the comments.

What to Read Next…

Can You Really Build a Future With Someone Who’s Terrible With Money?

10 Unusual Spending Habits That Reveal Someone Is Quietly Rich

What Happens When Inflation Creeps Into Everyday Purchases

8 Silent Wealth Killers That Hide in Everyday Expenses

20 Valuable Items In Your Home Hiding in Plain Sight

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Spending Habits Tagged With: community development, consumer spending, economic trends, financial behavior, local economies, Personal Finance, shopping habits

10 Happenings That Suggest White Flight Is Happening In Your Town

March 26, 2025 by Latrice Perez Leave a Comment

White Flight
Image Source: 123rf.com

White flight refers to the migration of white populations from urban areas to suburban or rural locales, often in response to increasing racial and ethnic diversity. This phenomenon has historically led to significant demographic shifts and has impacted community structures. Recognizing the signs of white flight can help communities address underlying issues and promote inclusivity. Here are ten indicators that may suggest white flight is occurring in your town.

1. Shift in School Demographics

A noticeable change in the racial composition of local schools can be an early sign of white flight. As white families relocate, schools may see a decrease in white students and an increase in students from diverse backgrounds. This shift can lead to changes in school funding, resources, and community support. It’s essential to monitor these demographic changes to ensure that all students receive equitable educational opportunities. Engaging with school boards and community organizations can help address and adapt to these transitions.

2. Changes in Property Values

Declining property values in certain neighborhoods may indicate that residents are moving out, possibly due to perceived or actual changes in the community’s demographic makeup. As homes are listed for sale in large numbers, the increased supply can drive down prices. This trend can disrupt the local housing market and affect community stability. It’s important to analyze the factors contributing to these changes to implement appropriate interventions. Community development programs and investment in local infrastructure can help stabilize property values and retain residents.

3. Decrease in Local Business Ownership

The disappearance of long-established, white-owned local businesses can signal demographic shifts and economic changes within a community. As the customer base evolves, some businesses may close or relocate, leading to a loss of familiar services and goods. New businesses may emerge, catering to the needs and preferences of a different demographic. This transition can alter the local economic landscape and affect community cohesion. Supporting diverse entrepreneurship and fostering inclusive business environments can mitigate these impacts.

4. Real Estate Marketing Trends

Real estate advertisements that emphasize the homogeneity of communities further away can encourage specific groups to consider relocating. This marketing strategy may subtly suggest that certain areas are more desirable due to their demographic composition. Such trends can perpetuate segregation and contribute to white flight. It’s crucial to promote fair housing practices and ensure that marketing strategies do not discriminate or marginalize any group. Educating real estate professionals about inclusive marketing can help create more equitable communities.

5. Emergence of Gated Communities

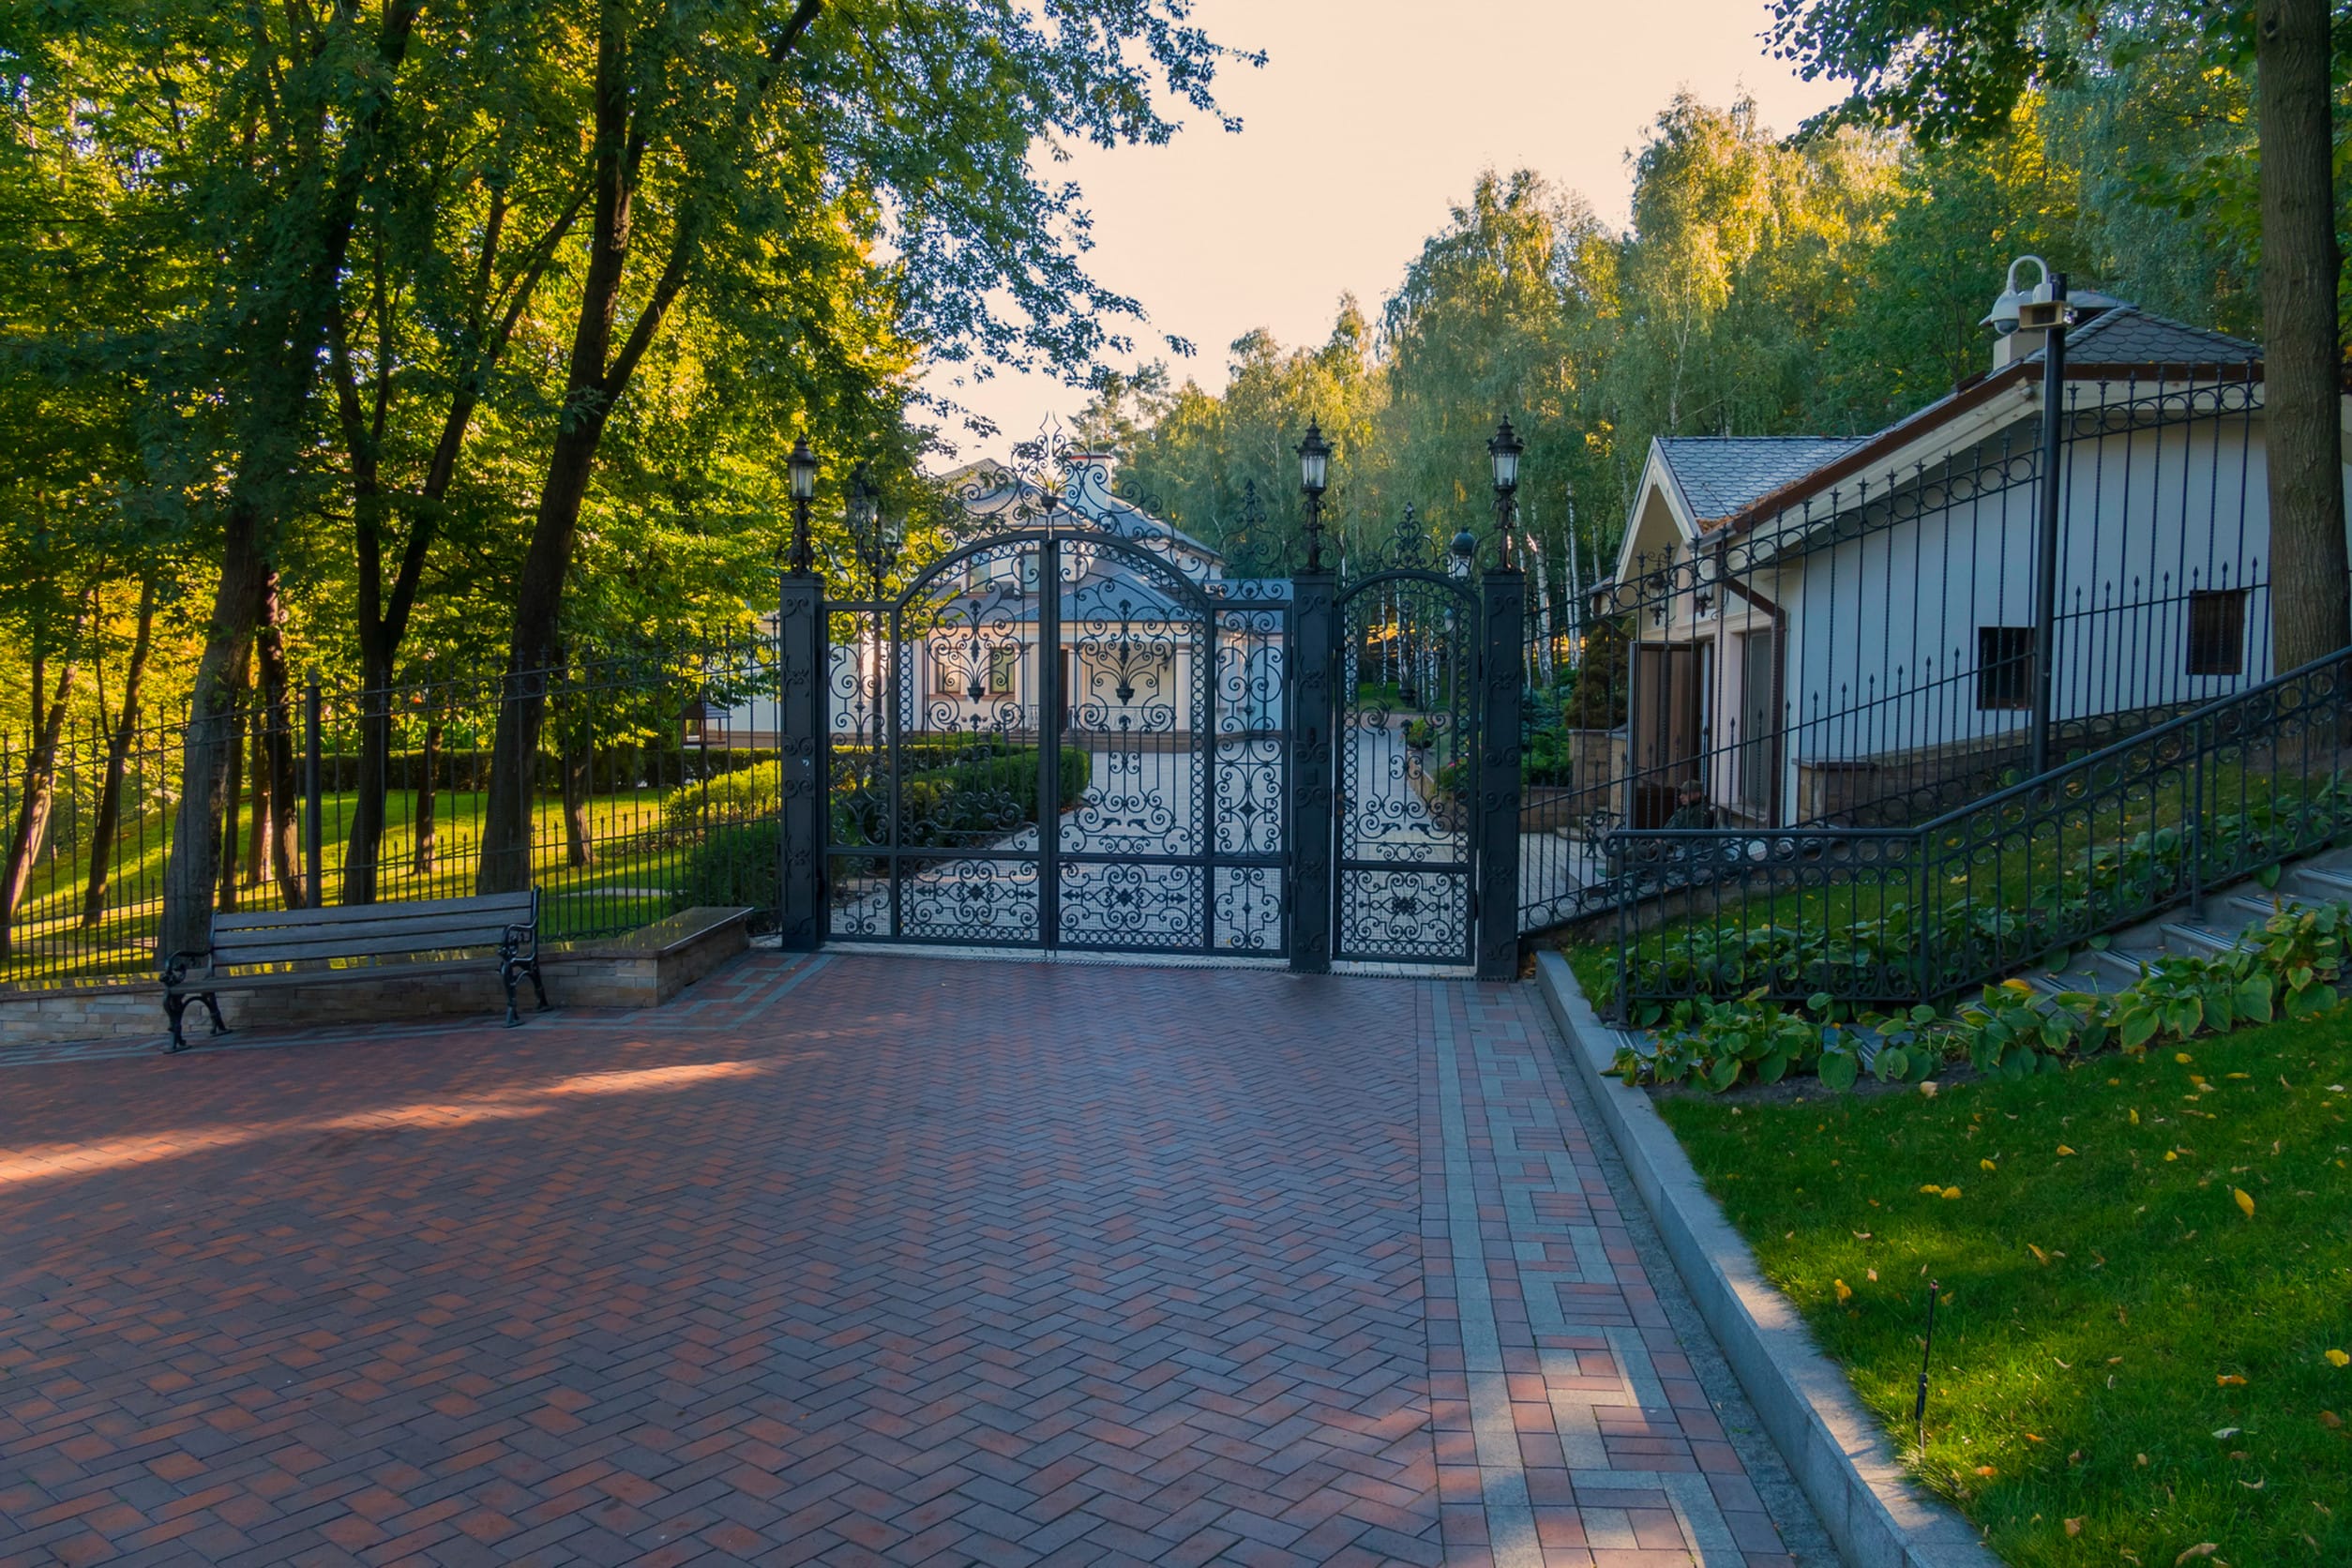
Entrance to the territory closed with an iron gate with a door made of their figured lattices with lanterns on top with a bench beside him in the shade of trees.
Image Source: 123rf.com

The development of gated communities can reflect a desire for exclusivity and separation from perceived changes in the broader community. These enclaves often appeal to those seeking homogeneity and security, potentially signaling underlying social divides. While they may offer amenities and a sense of safety, they can also exacerbate segregation and reduce social cohesion. Encouraging open and inclusive neighborhood designs can promote interaction and understanding among diverse populations. Urban planning that fosters mixed-use developments can counteract the isolating effects of gated communities.

6. Increased Enrollment in Private Schools

A surge in private school enrollments may indicate that families are opting out of public education due to changing demographics. This shift can lead to decreased funding and support for public schools, affecting the quality of education for remaining students. It’s essential to address the concerns prompting this exodus to ensure public schools remain robust and inclusive. Engaging with parents and community leaders to understand their motivations can inform policies that strengthen public education. Investing in public school resources and programs can attract and retain a diverse student body.

7. Political and Social Tensions

Heightened political and social tensions, such as debates over resource allocation or cultural representation, can be symptomatic of underlying demographic shifts. These conflicts may arise as communities grapple with changing identities and power dynamics. Addressing these tensions through open dialogue and inclusive policies is crucial for maintaining community harmony. Facilitating community forums and workshops can provide platforms for residents to express concerns and collaborate on solutions. Promoting cultural events that celebrate diversity can also enhance mutual understanding.

8. Media Portrayals and Public Perception

Local media narratives that emphasize crime or decline in certain neighborhoods can influence public perception and contribute to white flight. Sensationalized reporting may exacerbate fears and prompt residents to relocate. It’s important for media outlets to provide balanced coverage and for communities to critically assess the information presented. Encouraging media literacy and supporting local journalism that highlights positive community stories can counteract negative stereotypes. Collaborating with media professionals to promote ethical reporting can also mitigate harmful portrayals.

9. Infrastructure Neglect

Neglect of infrastructure, such as roads, parks, and public facilities, in certain areas can signal a lack of investment due to demographic changes. This neglect can lead to deteriorating living conditions, prompting residents to seek better environments elsewhere. Advocating for equitable distribution of resources and consistent maintenance can help prevent such decline. Engaging with local government officials to prioritize infrastructure improvements in all neighborhoods ensures that no area is left behind. Community-led initiatives to beautify and maintain public spaces can also foster pride and retention among residents.

10. Population Density Shifts

Significant changes in population density, such as declining numbers in certain neighborhoods and growth in others, can indicate migration patterns associated with white flight. Monitoring these shifts helps in understanding and addressing the factors driving them. Implementing policies that promote inclusive growth and prevent segregation is essential for balanced community development. Urban planners and policymakers should analyze demographic data to create strategies that encourage diverse and integrated neighborhoods. Providing affordable housing options across various areas can also mitigate population imbalances.

Fostering Inclusive Communities Amid Demographic Changes

Recognizing the signs of white flight is a crucial step toward fostering inclusive and resilient communities. By identifying these indicators, residents and policymakers can proactively address underlying issues, promote diversity, and ensure equitable development. Engaging in open dialogues, investing in community resources, and implementing inclusive policies can help mitigate the factors contributing to white flight. Building a community that values and embraces diversity not only enriches the social fabric but also strengthens the overall well-being of all its members.

Have you observed any of these signs in your community? What steps do you think can be taken to promote inclusivity and prevent white flight? Share your thoughts and experiences in the comments below.

Read More:

8 Signs Your Neighbor Is Watching You (And What to Do About It)

How Criminals Pick Their Targets—8 Everyday Mistakes That Make You Vulnerable

Headshot of Latrice Perez
Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Personal Finance Tagged With: community development, community engagement, demographic shifts, diversity, equitable development, inclusivity, neighborhood change, social cohesion, urban planning, white flight

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework