• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Susan Paige

Common Challenges and Solutions in Bank Reconciliation for Businesses

February 6, 2024 by Susan Paige Leave a Comment

In today’s fast-paced corporate world, maintaining accurate financial records is paramount for any business. A crucial aspect often overlooked by businesses is the bank reconciliation process, which plays a vital role in financial integrity. Reconciliation errors can lead to severe financial discrepancies, affecting business decisions and credibility. Understanding the potential challenges and solutions in bank reconciliation can shield a company from financial mishaps. Keep reading to dive into the common hurdles and how businesses can efficiently navigate them.

Understanding the Importance of Accurate Bank Reconciliations
Accurate bank reconciliations are the cornerstone of reliable financial reporting. By ensuring that the bank’s records match a company’s internal financial data, businesses can affirm the integrity of their financial statements. This comparison is not only a safeguard against fraud but also an indispensable tool in highlighting any inconsistencies that can distort a company’s financial health.

Inaccuracies in the reconciliation process can result in misleading information about cash flow and capital, which are critical factors in decision-making. Companies that diligently reconcile their accounts can better manage their cash, avoid overdraft charges, and identify unauthorized transactions quickly.

The task of reconciling bank statements with internal records can sometimes be daunting. However, the advent of digital solutions has made it easier to address discrepancies. By consistently following best practices in reconciliation, companies can significantly reduce financial risks.

Common Pitfalls in Bank Reconciliation and How to Avoid Them

Among the most frequent pitfalls in bank reconciliation are data entry issues caused by human error. These may seem trivial, but they can have a compounding effect on financial reports. Diligence and attention to detail are critical in preventing these mistakes from occurring.

Additionally, businesses often face problems due to timing differences, such as outstanding checks or deposits in transit. Maintaining a thorough record of pending transactions and regularly updating cash flow statements can help alleviate these issues.

Another common obstacle is the problem of lost records or unaccounted-for charges. To prevent such scenarios, firms should enforce a policy of regular documentation and review of all expenditures and receipts, along with prompt recording of each transaction.

Businesses must also contend with bank errors. Though infrequent, they can and do happen. Regular reconciliations enable companies to detect and address these errors swiftly, thereby maintaining accurate financial records.

Leveraging Technology to Streamline Bank Reconciliation Processes
Technology has revolutionized bank reconciliation by enabling automation and real-time data syncing. Advanced software can now match transactions almost instantaneously, saving businesses countless hours of manual work. Investing in such tools can reduce the likelihood of human error and boost efficiency.

Cloud-based reconciliation platforms are now the norm, offering the convenience of remote access and collaboration. These systems ensure that the financial team can work on reconciliations without being confined to the office, which is an asset in today’s increasingly mobile workforce.

Furthermore, modern reconciliation software often comes with analytical tools that provide insights into financial health. Understanding how to leverage these can empower a business to manage its cash flow more effectively, detect potential fraud, and make data-informed financial decisions.

Integration of the reconciliation software with other financial systems within the company creates a seamless flow of data. It ensures that every transaction reflects across all platforms, providing a coherent and accurate financial picture for stakeholders.

Implementing Internal Controls to Improve Reconciliation Accuracy

Companies should implement robust internal controls to improve accuracy in bank reconciliations. These include establishing clear protocols for recording transactions and conducting reconciliations. Checks and balances should be in place to ensure that no single individual has unfettered control over the financial reporting process.

Cross-verification by different departments or team members can significantly enhance the accuracy of reconciliations. It’s a method that fosters accountability and serves as a deterrent against potential financial misreporting or misappropriation.

Employee training is another cornerstone of robust internal controls. Ensuring that staff are knowledgeable about reconciliation procedures and the company’s accounting software prevents errors and enhances efficiency.

Altogether, meticulous bank reconciliation is indispensable for safeguarding a business’s financial integrity. While challenges are a given, implementing best practices and leveraging modern technology can streamline the task, turning potential obstacles into opportunities for improving financial management.

Filed Under: Personal Finance

The Truth About Cash Reward Mobile Games

January 30, 2024 by Susan Paige Leave a Comment

Have you seen those tantalizing app store games boasting you can “Play & Win Real Money”? The promise of scoring cash simply by playing casual games like solitaire, trivia, or virtual slots sounds too good to be true.

And often, it is.

Yes, some mobile games like Solitaire Cash do provide genuine chances at real-world prizes and payouts. But the actual processes for turning gameplay into cold hard currency are shrouded behind inflated marketing claims aimed to hook in players.

We’re gonna break down how real money gaming apps actually work – moving beyond hype to explain murky monetary mechanisms, risks to weigh before playing, and strategies to boost payout potential.

Mobile Game Genres With Cash Rewards

While styles range widely, these core categories comprise most real-money games:

Trivia

  • Test knowledge answering questions across topics
  • Gameshow type presentation
  • Occasional large-scale tournaments

Arcade Style

  • Fast-paced games demanding skill and reflexes
  • Racing, shooter, reaction-time variants
  • Beat high-score tables for earnings

Card Games

  • Solitaire and poker lead the pack
  • Luck-based over skill in most
  • Relaxing backdrop with financial risk looming

Casino Games

  • Slots, roulette, bingo
  • Closely mimic established gambling platforms
  • Bright, exciting, and addictive

Sports Prediction

  • Forecast real-life game and season outcomes
  • Sports junkies guess right to convert picks into cash

The most popular models employ freemium approaches, allowing free plays while attempting to upsell pricy power-ups. But how do these different games actually deliver rewards?

Payment Structures – How Winnings Get Disbursed

  1. Giveaways and Lotteries
  • Random prize drawings reward tickets/points earned through play
  • Mostly cheap swag, some cash – low real-world value
  • Easy to rack up entries via in-app purchases
  1. Tournaments With Cash Prizes
  • Scheduled competitive events award prizes to top scorers
  • Requires serious skill development for consistent placings
  • Rewards directly correlate to number of entrants
  1. Wager-Based Betting Returns
  • Place real-money bets within games based on in-app outcomes
  • Risk adjusted based on wager amount
  • Potential for big rewards along with losses
  1. Lifetime Game Achievement Thresholds
  • Cash-out accrued earnings after hitting incremental milestones
  • Typically nominal amounts relative to time investments
  • Incentive designed to drive long-term retention

Clearly, significant variance exists depending on the payout mechanism. Compared to achieving cash via skill sharpened through tournaments, randomized drawings or ongoing point accrual over months carry lower realistic value. Meanwhile, wagers pose their own risks.

Now, for key considerations if debating whether chasing mobile gaming payouts makes sense for you:

Evaluate If Cash Gaming Aligns With Your Goals

Upside Payout Potential

  • Life-changing jackpots dangle like carrots on sticks
  • Top tournaments promise five- and six-figure rewards
  • But nearly impossibly low odds means few ever score such huge payouts

Downside Risks

  • Vast majority walking away empty-handed
  • Wagers mean direct out-of-pocket losses likely

Time Commitment Required

  • Maximizing theoretical winnings requires immense grind of regular, sustained play
  • Question if gaming time well spent relative to working

Enjoyment Factor

  • Fixating on cash risks compromising inherent fun of games
  • Burnout extremely common

Spending Temptations

  • Desire for scoring advantages/power-ups adds up
  • Wins easily erased by continually plunking down payments with already poor odds

If those juicy theoretical jackpots catch your eye, sincerely assess these factors before jumping in. Don’t ignore blatant warning signs indicating you’re becoming obsessed chasing losses rather than enjoying gaming. Moderation remains absolutely key.

And while no formula or tips can magically deliver regular profits, certain approaches show positive correlation with bankable outcomes:

Tactics to Enhance Winnings

Learn Game Nuances Intimately

  • Tourney success requires expertise – study intricacies
  • Analyze scoring algorithms

Consistency + Volume = Results

  • Greater frequency of play means more prize exposure
  • Continuity drives iterative skill improvement

Apply Bonuses Wisely

  • Power-ups do optimize scoring ceilings
  • But restrain real-money purchases that erase value

Leverage Promotional Plays

  • New user bonuses and free tournament entries help
  • But don’t chase losses by continually buying plays

Have An Exit Strategy

  • Determine a threshold where you will withdraw funds rather than let them ride indefinitely
  • Cash-out winnings periodically instead of chasing bigger scores that may never come

Remember, the second gaming feels frustrating or you notice excessive spending in hopes of recouping – rather than entertainment – step back immediately.

Is It Worth It?

While supplemental income without traditional work sounds alluring, the reality is relatively few walk away consistent winners at these mobile gambling-lite style pursuits. But plenty derive enjoyment from sharpening skills and testing luck with small wagers.

Hopefully this transparent look better explains the genuine dynamics governing real-money gaming apps – cutting through ambiguous promises to outline concrete payment structures. Fantasies about effortless earnings require tempering with fact-based constraints around payout odds and volumes required.

The ultimate choice comes down to aligning gaming with your personal financial reality and carving out time responsibly. Anything won should be considered bonus over expectation! But approached appropriately, mobile skill games can pay small dividends.


Filed Under: Personal Finance

Why having a pension plan is important for your business

January 25, 2024 by Susan Paige Leave a Comment

For every business, it’s crucial to make long-term planning not only for the company but also for the employees. 

A successful business will always consider the employees as its asset, therefore it will take care of their future even when they are not working with them. One of the most highly valued offerings a business can provide for an employee is a pension plan. 

As an owner of a forward-thinking company, it’s your job to recognise the potential of your employees and reward them in a way that will eventually lead to the company’s success. And nothing compares to the value a pension plan will add to your business’s success and growth. 

Let’s unvail this secret to a happier team and a thriving business, shall we? As you dig into the contents of this article, you will learn what benefits you and your business will get by offering a pension plan to your business. 

5 Reasons Why a pension plan is important for your business

No matter what business you’re running, providing a pension plan can help both your employees and your business. Following are some of the reasons why a pension plan is crucial for your business.

Employee Retention and Recruitment

The job market is competitive these days, for both the job seekers and the recruiters. In that case, you will always want to hire someone with the right talent to ensure the proper growth of your business.

While you’re looking for the right candidates, they are also looking for a job that treats them right. Offering beneficial packages, including a pension plan will definitely attract the right candidates.

Besides, you don’t want to hire someone who might leave just after a few months. You want to hire someone who will stay here for the long run , thus making great contribution to your growth. 

But, how are you going to ensure that?

The solution is quite simple. Employees will only stay longer in a company that invests in their future. 

While every business wants to get the best person to join their team, only the one who will ensure financial security for long will get them. And what can be better than a pension plan?

Boosting Employee Morale and Productivity

Nothing can frustrate an employee more than a poor financial future and the insecurity they face during their time in a company. That leads to a decreased moral value and poor productivity.

Retirement plans like pensions can reduce workplace frustration to a great extent, allowing employees to focus on their job responsibilities.

By ensuring a pension plan, you can show your employees that you care for them and their future. Doing so will create a healthy culture of appreciation and job satisfaction. It will ensure sustaining employee morale and the productivity will increase like magic!

Tax Advantages

A pension plan can be one of the best retirement plans you can offer that will eventually help you back. 

The best part of this plan is that it’s often tax deductible. It means the more you will contribute to the employee pension plan, the more it will reduce your company’s taxable income.

And, what makes the plan more attractive is that your employees will enjoy the rewards of tax deferral on their pension contributions. A win-win situation for everyone!

Long-Term Financial Health for Employees and Employers

Let’s be honest, no employee can stay in your company forever! Even the most loyal ones have to retire at some point. The last thing you will want for them is to end up in misery.

Once a person retires, they don’t usually have access to regular income anymore. They start relying on their savings, social security, or even selling their assets in some cases. And as an employer, it’s your responsibility to secure the financial future of the person who contributed so much to your success.

A solid pension plan can come as a rescuer in that case. It will make sure your employees rely less on social security. This can help ensure that their energy is focused towards the future of your business- when they know you’re taking care of theirs!

Providing such facilities can also help them invest in something beneficial after their retirement- be it  starting their own business, applying for pension mortgages, or even planning for a long-awaited trip. 

Besides, by providing a pension plan, you are also helping them to increase their savings. This plan ensures employees and employers unite in the shared adventure of shaping a rewarding and secure retirement future.

Enhancing Company Reputation

No business can thrive only by focusing on its profit. You have some social responsibility and you need to take care of the people who are working so hard for you.

Company that only thinks about its benefits will never become a reputed one among others. And the best way you can make your business popular is by taking good care of your employees. 

Establishing a pension plan demonstrates that you’re a forward-thinking employer who values their employees’ financial security and well-being. Doing so can improve your reputation to your employees, as well as to your consumers.

It’s because a business that takes care of its employees tends to attract customers who value a responsible and ethical corporate practice. So, by taking care of your employees you are actually taking care of you!

Conclusion

Your employees are like the pillars of your business. Without their contributions, you could never thrive, let alone survive. So, it’s now your turn to return the favor by ensuring financial security when they are no longer working with you.

A pension plan isn’t just a financial decision, it’s more than that. By opting for it, you’re investing in the most valuable assets of your company, your people. 

In conclusion, establishing a pension plan is a crucial component of a sustainable and ethical business strategy. 

When your employees know you care for them, it increases their respect, and their loyalty for you, resulting in employee productivity. And a productive workforce leads to success and innovation within the company.


Filed Under: Personal Finance

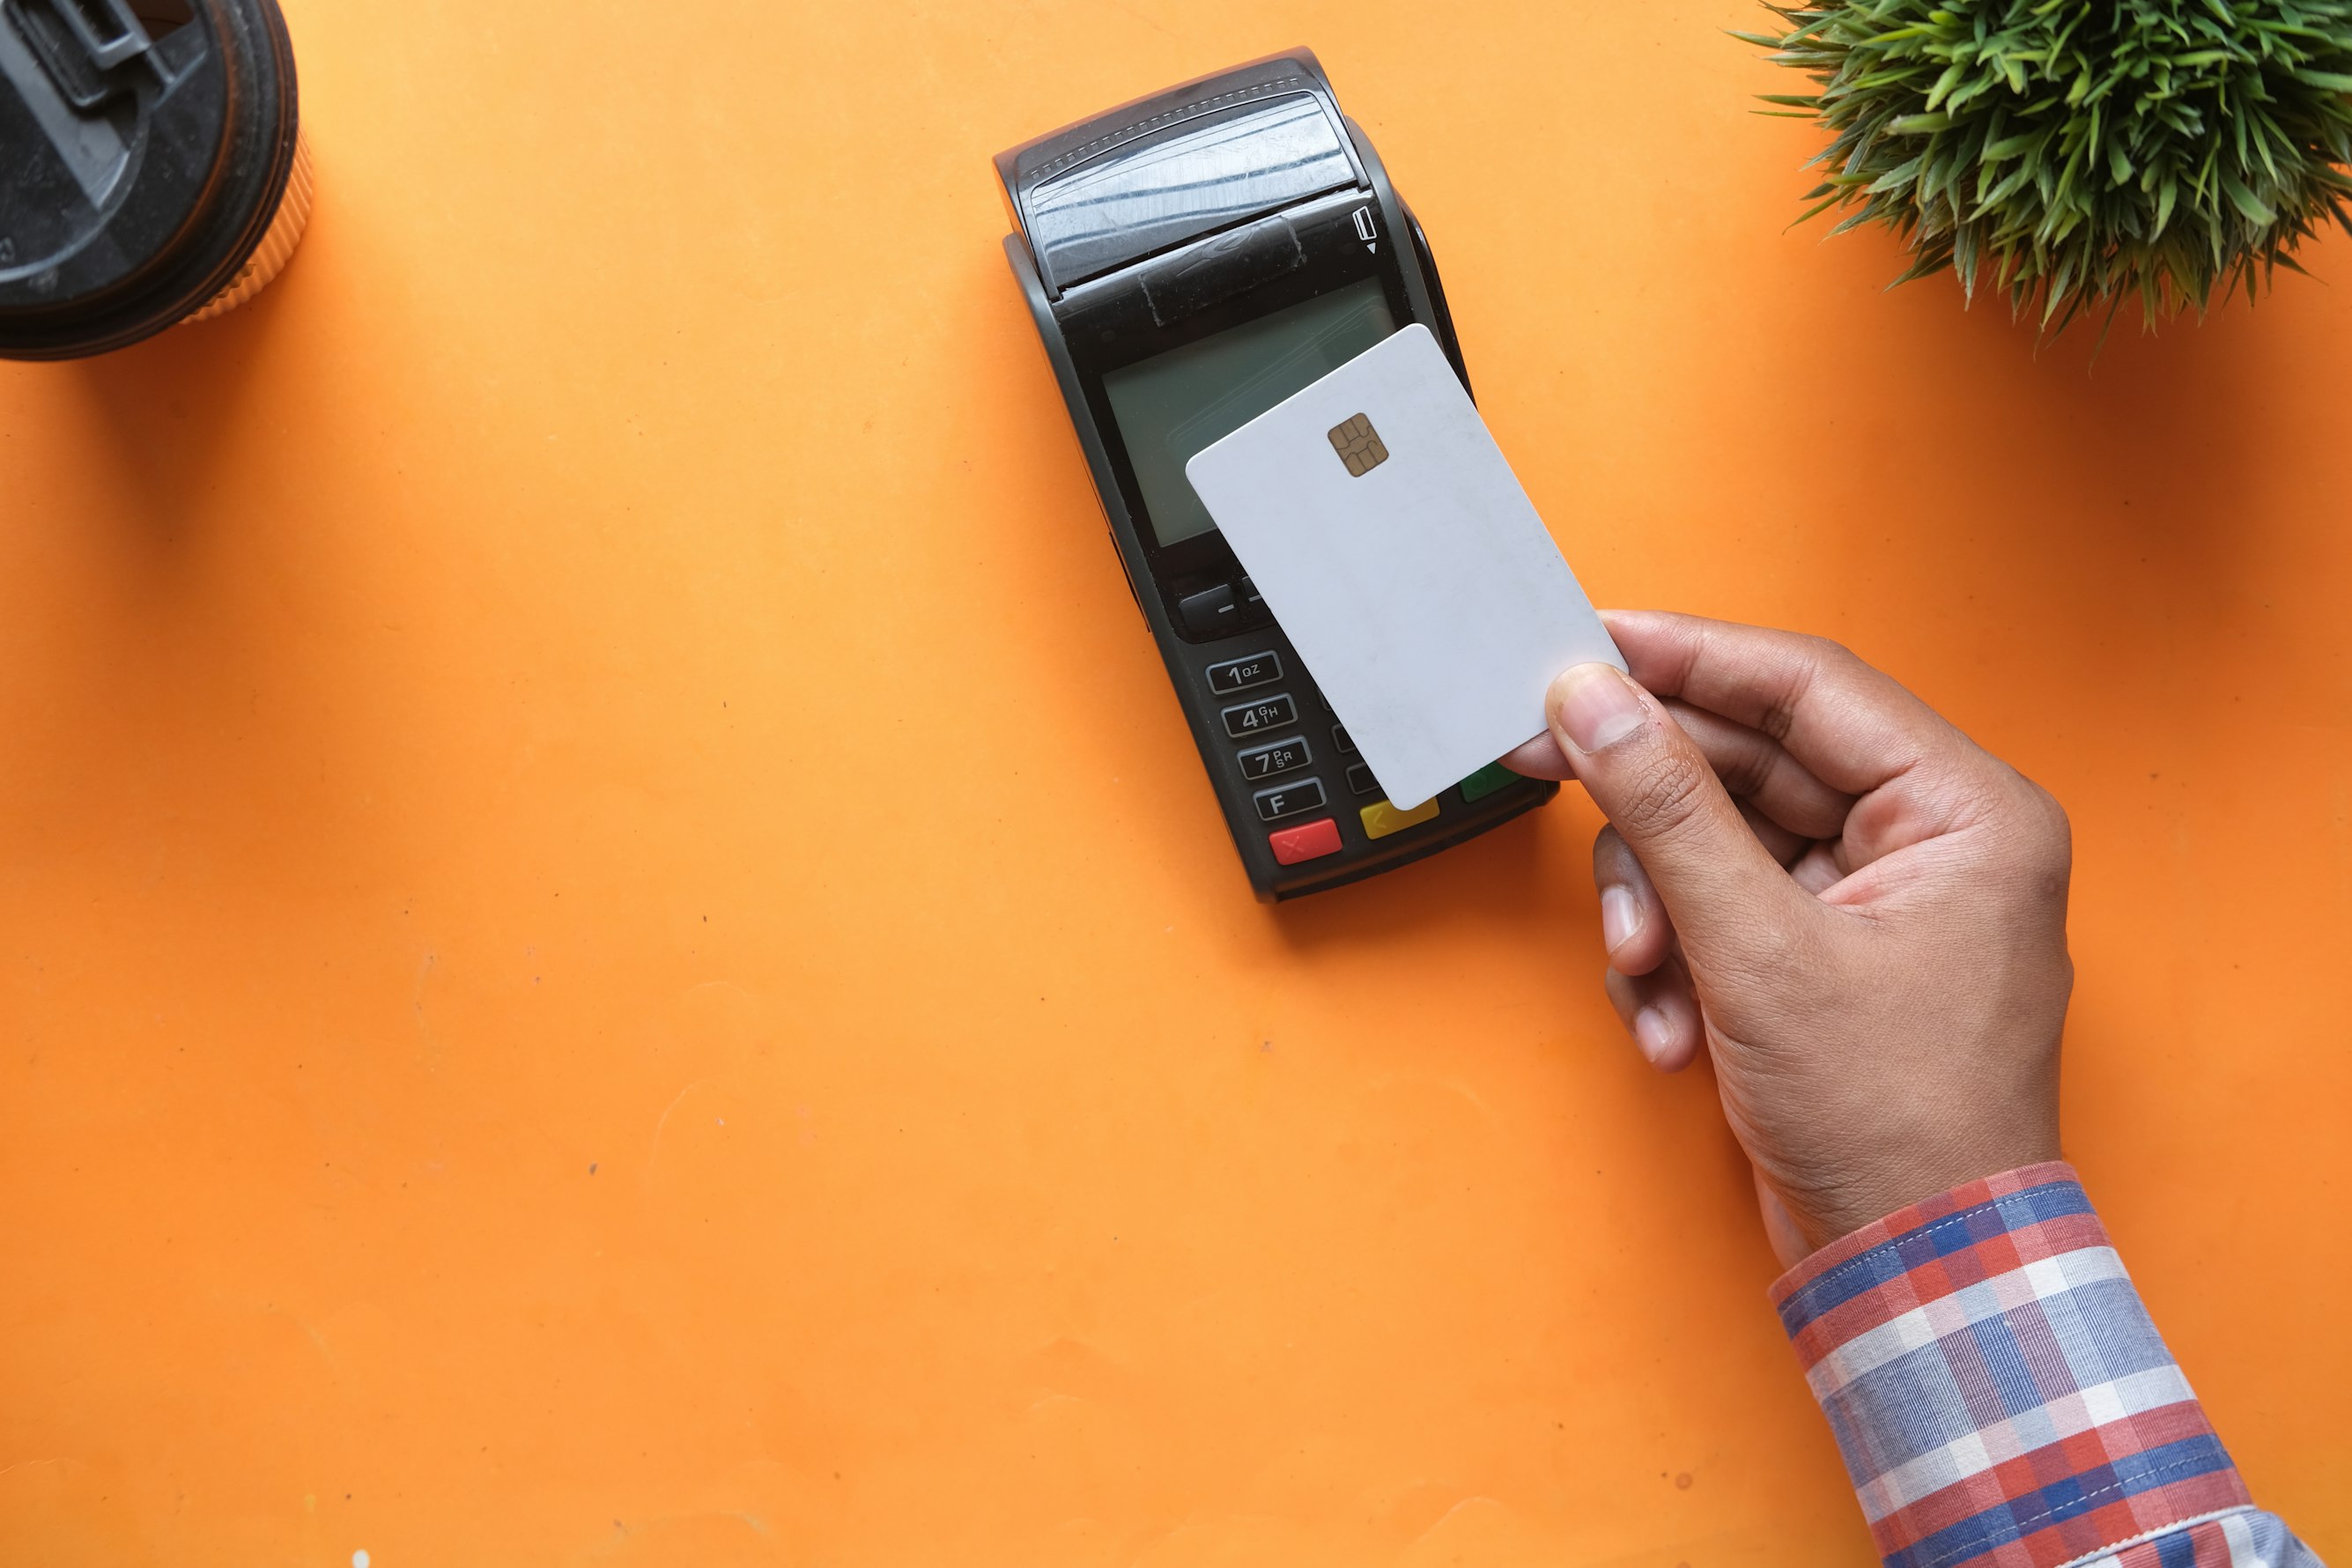
7 Important Things You Should Know About Debit Cards Before You Get One

January 24, 2024 by Susan Paige Leave a Comment

In an era where financial literacy is becoming as crucial as traditional literacy, understanding the nuances of everyday financial tools is paramount. Debit cards, omnipresent in wallets around the globe, are more than just plastic conduits to our funds. They’re gatekeepers of financial freedom and responsibility. As you contemplate adding this tool to your arsenal, it’s essential to grasp the depth of its utility, limitations, and the responsibility it entails. Let’s delve into seven key insights to equip you for a well-informed decision.

1. Direct Link to Your Bank Account 

Unlike credit cards, a debit card is your direct line to your checking account, offering a real-time reflection of your financial status. Each transaction reflects immediately, making it an excellent tool for those who prefer to monitor their spending closely. 

However, this direct link also means that any error or unauthorized transaction can have immediate financial consequences. It is essential to regularly monitor your bank statements and set up alerts for transactions to catch any discrepancies early. 

This vigilance helps keep your finances in check and instills a sense of discipline in money management. Balancing this immediacy with careful oversight is key to leveraging the benefits of a debit card while mitigating its risks.

2. Overdraft Risks and Fees

Overdraft protection is a feature that can be a lifesaver in moments of financial oversight but can also lead to a false sense of security. While it prevents the discomfort of a declined transaction, it’s crucial to be aware of the terms of your overdraft protection, as these can vary significantly between banks. 

Some may offer a grace period for repaying the overdraft, while others charge immediate fees. These fees can compound, making small purchases exorbitantly expensive. Regularly monitoring your account, setting up low balance alerts, and understanding your bank’s overdraft policy can help avoid these potentially hefty fees. Remember, overdraft protection is a tool for occasional emergencies, not a regular extension of your budget.

3. Limited Fraud Protection Compared to Credit Cards 

While convenient, debit cards do not offer the same level of fraud protection as credit cards. The key difference lies in the immediacy of transactions. 

Once a fraudulent transaction occurs, the funds are immediately withdrawn from your account, potentially leading to a ripple effect of declined transactions and financial inconvenience. It’s important to regularly review your transactions and report any suspicious activity immediately. Many banks offer temporary credits during fraud investigations, but the process can be stressful. 

Additionally, consider using your debit card only at trusted merchants and avoid using it for high-risk transactions, like online purchases from unfamiliar sites, to further minimize the risk of fraud.

4. No Credit Building Capability 

One of the most significant drawbacks of a debit card is its inability to influence your credit score. Credit scores are calculated based on your credit history, including factors like credit utilization and timely payments. Debit cards, drawing directly from your bank account, do not contribute to this history. For those looking to build or improve their credit score, a credit card, used responsibly, can be a more suitable tool. 

Regular, on-time payments and keeping a low balance relative to your credit limit can positively impact your credit score. It’s also worth exploring other credit-building tools like secured credit cards or small installment loans, which can complement your efforts to establish a solid credit history.

5. ATM Accessibility and Fees

One of the significant advantages of debit cards is the convenience of being able to withdraw cash from ATMs anytime, anywhere. However, it’s vital to be mindful of the fees associated with using ATMs, especially those not affiliated with your bank. 

These fees can vary widely and add up quickly, particularly if you’re a frequent cash user. Some banks offer reimbursement for these fees or have extensive networks of fee-free ATMs. It’s beneficial to familiarize yourself with these options. 

Moreover, planning cash withdrawals or using cash-back options at retail checkouts can minimize these costs. Always be aware of the balance in your account to avoid additional charges for insufficient funds.

6. The Convenience of Cashless Transactions

In our increasingly cashless society, debit cards offer more convenience than ever. They streamline transactions, reduce the need to carry cash and simplify online purchases. Companies like NinjaCard.com are at the forefront of this revolution, offering debit cards that not only provide the usual benefits but also come with additional perks. 

However, while enjoying the ease of cashless transactions, it’s important to stay vigilant about where and how you use your debit card to ensure security and minimize the risk of fraud.

7. Daily Spending and Withdrawal Limits 

The spending and withdrawal limits on debit cards are primarily a security feature designed to limit potential losses in case of theft or fraud. However, these limits can also be a source of frustration. For example, you might be unable to make large purchases or withdraw significant cash in an emergency. It’s essential to understand the specific limits set by your bank and how they align with your spending habits. 

Conclusion

A debit card is not just a financial tool; it’s a reflection of your financial habits and needs. Its direct connection to your bank account requires a disciplined approach to spending and vigilance in monitoring your account. While it doesn’t directly aid in credit building, its convenience and immediate impact on your finances make it an indispensable tool in the modern financial landscape. As with any financial decision, understanding these seven aspects of debit cards will empower you to use them effectively and responsibly, ensuring that this small piece of plastic becomes a significant asset in managing your financial health.


Filed Under: Personal Finance

How can smart budgeting ease financial expenses as a student?

January 23, 2024 by Susan Paige Leave a Comment

Although handling finances while in school might be complicated, it’s a vital trait that lays the groundwork for a prosperous future. The financial obstacles that students have encompassed everything from the price of textbooks and fees to regular living expenses and other extracurricular endeavors. 

There are various techniques to create a budget: you can use a digital template to create an Excel file or an application that links to your bank accounts. Whatever approach you employ to achieve your financial goals, it’s essential that you stick with it and take responsibility for it. Therefore, in this article, we’ll examine the skill of budgeting and provide helpful advice to assist students in managing their money sensibly.

  • Evaluate your net earnings and expenses

The objective of budgeting is to define financial targets. Cautious spending can be encouraged by short-term objectives like saving for an exciting new gadget or holiday getaway. Still, long-term objectives like accumulating a reserve fund or making post-graduation plans, such as trying an information management degree, help maintain a steady income. 

  • Sort your spending into sections that remain constant and adjustable

Sorting the costs you incur every month into fixed as well as variable categories is the next step after listing them. Fixed expenditures are the bills that you generally need to pay attention to and must pay, including rent, groceries, textbooks, insurance, and transportation. On the other hand, variable expenses are adaptable bills; examples are travel, gym membership, entertainment purchases, and dining out. 

The 50/30/20 guideline makes allocating funds easier. A budgeter would, for instance, set aside 50% of their earnings for necessities like groceries and rent, 30% for extra expenses on things like entertainment, and 20% for savings or debt repayment.

  • Make amendments

Verifying that the computations add up and evaluating the facts you have gathered are necessary steps in finishing the budgeting process. Compare your monthly expenses to your annual income to see if you have enough cash coming in each month to cover all of your bills. If the cost of life is out of your financial means, it’s time to make an alteration. You should look at strategies to reduce expenses in addition to measures to increase your income, such as working longer hours.

To counterbalance your costs, consider utilizing a credit card that pays rewards on all of your purchases. One percent cashback is available on qualifying purchases with the Deserve® EDU Mastercard for Students and the Petal® 2 “Cash Back, No Fees” Visa® Credit Card. 

Also, once you make 12 timely monthly payments with the Petal 2 Visa Credit Card, you can receive up to 1.5% in cash back. If a student wants to apply for their first credit card, they should consider one of these cards.


Being financially successful is mostly dependent on budgeting, especially as a student. They can make prudent financial choices that lead to a prosperous future by following the instructions provided in this blog post. Pupils should know how to manage their finances effectively. Lower your stress levels, save cash, and establish a solid monetary future by heeding the advice above! 

Filed Under: Personal Finance

Navigating Change: TPT’s Expertise in DB Scheme Consolidation

January 18, 2024 by Susan Paige Leave a Comment

For DB schemes considering consolidation, it can be challenging to establish which solution is the best fit for your scheme. Jonathan Jackaman, Head of Business Development at TPT explores the options now available, for wherever you are on your endgame journey.

Since the Department for Work and Pensions (DWP) published its white paper on ‘protecting defined benefit pension schemes’ back in 2018, a variety of new products and services have been developed across the industry – all designed to help trustees and sponsors embrace consolidation.

Outside of the public sector, the vast majority of UK employers now offer defined contribution (DC) schemes for current employees. Consolidated DC arrangements are very much ‘the norm’ for newer schemes. And over the past decade, many previously ‘unbundled’ own-trust DC schemes have also moved to a consolidated model. 

The success of consolidation in DC is likely to be a key driver in getting trustees and sponsors to consider how they can benefit from similar efficiencies and economies of scale on the DB side. And, with the plethora of options now available for DB schemes, there is likely to be a consolidation approach that could benefit your scheme, wherever you are on your journey.

Consolidating some or all elements of managing your scheme can create significant time and cost savings while improving quality and reducing (or, in some cases, removing entirely) the burden on your trustees.

Jonathan Jackaman, Head of Business Development at TPT, stated, “Each consolidation option offers different benefits. As with most things, it all comes down to finding the right approach for your scheme, sponsor and members. In many cases, you may find it beneficial to use different consolidation options as you progress through your end-game journey. For example, moving to a single provider for all services to resolve both data and illiquid asset issues, then to a master trust, before finally securing members’ benefits through buyout”.

The Significant Benefits of DB Pension Scheme Consolidation

Cost Efficiency

Service supply efficiency allows schemes to take a more basic approach to running a scheme with known and anticipated expenditures, allowing for better financial planning and cost control. 

Improved Governance

Integrating relationships with service providers allows you to connect with professionals through a single point of engagement. Consolidation enhances efficacy and transparency by reducing the amount of time spent dealing with different service providers, allowing trustees and the sponsoring organisation to focus on more important strategic issues. 

The Management of Risk

Consolidation can provide a better plan for administering a pension system and positioning it for its end game, which might be a buy-out, a superfund, a run-off, or something else, all while preserving an identifiable strategic emphasis. Reduce the danger of financial catastrophe by keeping advisor costs under control and developing a clear roadmap to the pension’s long-term objectives. 

Investment Availability

Consolidation allows you to use tactics, resources, and investment categories that are generally available to larger schemes. Programmes that are part of a larger fund may benefit from economies of scale. 


For more information on DB schemes and consolidation options, visit https://www.tpt.org.uk/news-insights/consolidation-options-for-db-pension-schemes/. 


About TPT:

TPT is a leading provider of pension services, offering innovative solutions for defined benefit pension schemes. With a commitment to helping trustees and sponsors navigate the evolving pension landscape, TPT provides expertise, support, and tailored solutions to meet their unique needs.


Filed Under: Personal Finance

The Mobile Advertising Landscape

January 17, 2024 by Susan Paige Leave a Comment

As mobile devices continue to dominate our digital lives, crafting an effective mobile ad placement strategy has become more critical than ever. In this article, we will explore the significance of mobile ad placement and introduce you to a powerful tool in the world of advertising – the bridge page. With a focus on delivering relevant and engaging content, a well-executed bridge page can amplify the impact of your mobile ad placements and contribute to a successful advertising campaign.

The Mobile Advertising Landscape

Mobile advertising has witnessed exponential growth in recent years, driven by the proliferation of smartphones and increased mobile internet usage. To harness the potential of mobile advertising, it’s essential to understand the mobile landscape:

  • Mobile User Behavior:
    • Mobile users have distinct behaviors and expectations. They often engage with content in shorter, more frequent sessions.
    • Understanding these behaviors is vital for crafting effective mobile ad placements.
  • Mobile-First Approach:
    • A mobile-first approach means designing ad creatives, landing pages, and user experiences with mobile users in mind.
    • Advertisers must optimize their strategies to cater to the mobile audience.
  • Diverse Mobile Platforms:
    • Mobile advertising encompasses various platforms, including mobile websites, apps, and social media.
    • Tailoring your ad placement strategy to each platform’s unique features and user behavior is crucial.

The Role of Mobile Ad Placement Strategy

A well-considered mobile ad placement strategy can significantly impact the success of your advertising campaigns. Here are key elements to consider:

  • Contextual Relevance:
    • Placing ads in contexts relevant to the user’s interests and needs increases the chances of engagement.
    • For example, a fitness app might strategically place ads for workout gear within exercise routines.
  • User Experience:
    • Ensure that ad placements enhance rather than disrupt the user experience. Non-intrusive and well-designed ad formats are essential.
    • Advertisements should load quickly and not slow down the mobile experience.
  • Audience Targeting:
    • Utilize precise audience targeting to reach users who are most likely to be interested in your products or services.
    • Data-driven targeting improves ad relevance and ROI.
  • Responsive Design:
    • Optimize ad creatives and landing pages for various mobile devices and screen sizes.
    • Responsive design ensures a seamless and visually appealing experience.

Maximizing Impact with Bridge Pages

Bridge page are an invaluable asset in mobile advertising, serving as intermediaries between your ad and the destination page. These pages prepare users for the next step and can significantly impact campaign performance:

  • Prequalification:
    • Bridge pages offer an opportunity to prequalify users by providing additional information about the advertised offer.
    • Users who proceed to the destination page are more likely to convert, leading to higher conversion rates.
  • Persuasive Messaging:
    • Craft persuasive copy and visuals on bridge pages to convince users to take the desired action.
    • Address user concerns, highlight benefits, and provide a clear call-to-action (CTA).
  • Seamless Transition:
    • Ensure that the transition from the bridge page to the destination page is smooth and logical.
    • Users should feel that they are continuing a seamless journey.
  • A/B Testing:
    • Employ A/B testing on bridge pages to refine messaging, design, and CTAs for optimal performance.
    • Iterative testing helps improve conversion rates over time.

Putting it All Together

To create a successful mobile advertising campaign that combines effective ad placement with bridge pages, consider the following steps:

  • Research Your Audience:
    • Understand your mobile audience’s preferences, behaviors, and pain points.
    • Tailor your ad placements and bridge pages to align with these insights.
  • Choose the Right Platforms:
    • Select mobile advertising platforms that cater to your target audience and campaign goals.
    • Each platform may require a unique approach to ad placement and bridge page design.
  • Create Engaging Content:
    • Craft compelling ad creatives and bridge page content that resonates with your audience.
    • Use visuals, storytelling, and concise messaging to capture attention.
  • Monitor and Optimize:
    • Continuously monitor the performance of your mobile ad placements and bridge pages.
    • Use data-driven insights to make informed optimizations for better results.

Conclusion:

In the fast-paced world of mobile advertising, a well-executed mobile ad placement strategy combined with the strategic use of bridge pages can be a game-changer. By focusing on contextual relevance, user experience, and audience targeting, you can maximize the impact of your mobile advertising campaigns and drive meaningful results. Stay agile, keep refining your approach, and embrace the opportunities that mobile advertising offers in reaching and engaging your target audience.

Filed Under: Personal Finance

How to Successfully Prepare and Manage Your First Lab Budget

January 12, 2024 by Susan Paige Leave a Comment

There are over 26,519 diagnostic and medical laboratory businesses, and if you want to join this competitive field, you will have to play your cards right. One of the most important tasks you’ll need to consider is your budget. A well-organized and thoughtfully prepared budget is crucial for the smooth operation of any lab.

However, preparing and managing your first lab budget can be a daunting task, especially if you’re new to the field of research or laboratory management. But don’t worry, we’ve prepared a simple guide you can follow to ensure that you start off on the right track. Here are five key points to consider when preparing and managing your first lab budget.

Understanding Your Lab’s Heart and Soul

Imagine your lab as a living entity with its own needs and desires. Just like nurturing a plant, you need to understand what’s essential for its growth. Begin by mapping out the essentials—the equipment that’s the backbone of your experiments, the supplies that are the daily bread, and the team that’s the heartbeat of your lab.

Picture your goals and align your priorities accordingly. Remember, some needs are urgent, like the pipettes you use daily, while others, like a fancy new spectrometer, might be long-term dreams. Balancing these immediate and future needs is like planning a well-rounded diet for your lab’s health.

Crafting a Masterplan for Your Lab’s Treasury

Drafting a budget is like making an elaborate plan, you need to know every piece of equipment that goes into an efficient laboratory. Start by listing everything, from microscopes and high-end single cell seeder equipment to the Petri dishes. Every item, no matter how small, counts. For instance, single-cell seeders are essential elements of any lab, easy to set up and their compact size makes them convenient for smaller labs.

Once you’ve laid out this grand plan, it’s time to allocate your resources. Ensure that you have enough budget to procure each item that is necessary for operating your lab.

Bargain When Hunting for Lab Items

Shopping for your lab shouldn’t be rushed; take your time to explore the market. Gather multiple quotes for your lab items and make a list so that you know from where you can procure the best equipment for the right price. You’ll be surprised at the variations in price for the same item. And don’t shy away from a little haggling, you will be surprised how much money you can save.

Your goal is to stretch every dollar, getting the best quality for a lesser price. Remember, every penny saved is a penny that can be used for something exciting, like that experiment you’ve been dreaming about.

Budget Tracking

Monitoring your budget is like being a detective in your own lab. Keep an eye on where every dollar goes, and track it as meticulously as you would your research data. This constant vigilance helps you spot trends; maybe you’re spending too much on one-time-use items, or there’s a way to cut down on energy costs. 

Regularly checking your budget allows you to be flexible and adaptive. Think of it as fine-tuning a complex experiment, sometimes you need to adjust your approach to get the best results.

Dreaming Big and Sustainable for Your Lab’s Future

Planning for your lab’s future is like charting a course for a grand adventure. Always be on the lookout for new funding opportunities; they’re like hidden treasures that can fuel your journey. Look for investors and network constantly, and you will find proper partners who will take your business to a new level in no time.

Embrace sustainability not just as a buzzword but as a mantra for your lab’s longevity. Invest in practices and equipment that save money in the long run, like energy-efficient freezers or reusing materials. This approach is not just about being thrifty; it’s about creating a legacy, a lab that’s not only successful today but also thrives in the future.

Conclusion

Creating and managing a lab budget requires careful planning, regular monitoring, and adaptability. By understanding your lab’s needs, meticulously planning your budget, seeking the best deals, regularly reviewing your spending, and planning for future sustainability, you can ensure the financial health and success of your lab. Remember, a well-managed budget is key to supporting your lab’s research goals and long-term growth.

Filed Under: Personal Finance

Strategic Retirement Planning: Integrating Home Care Packages Into Your Future

January 11, 2024 by Susan Paige Leave a Comment

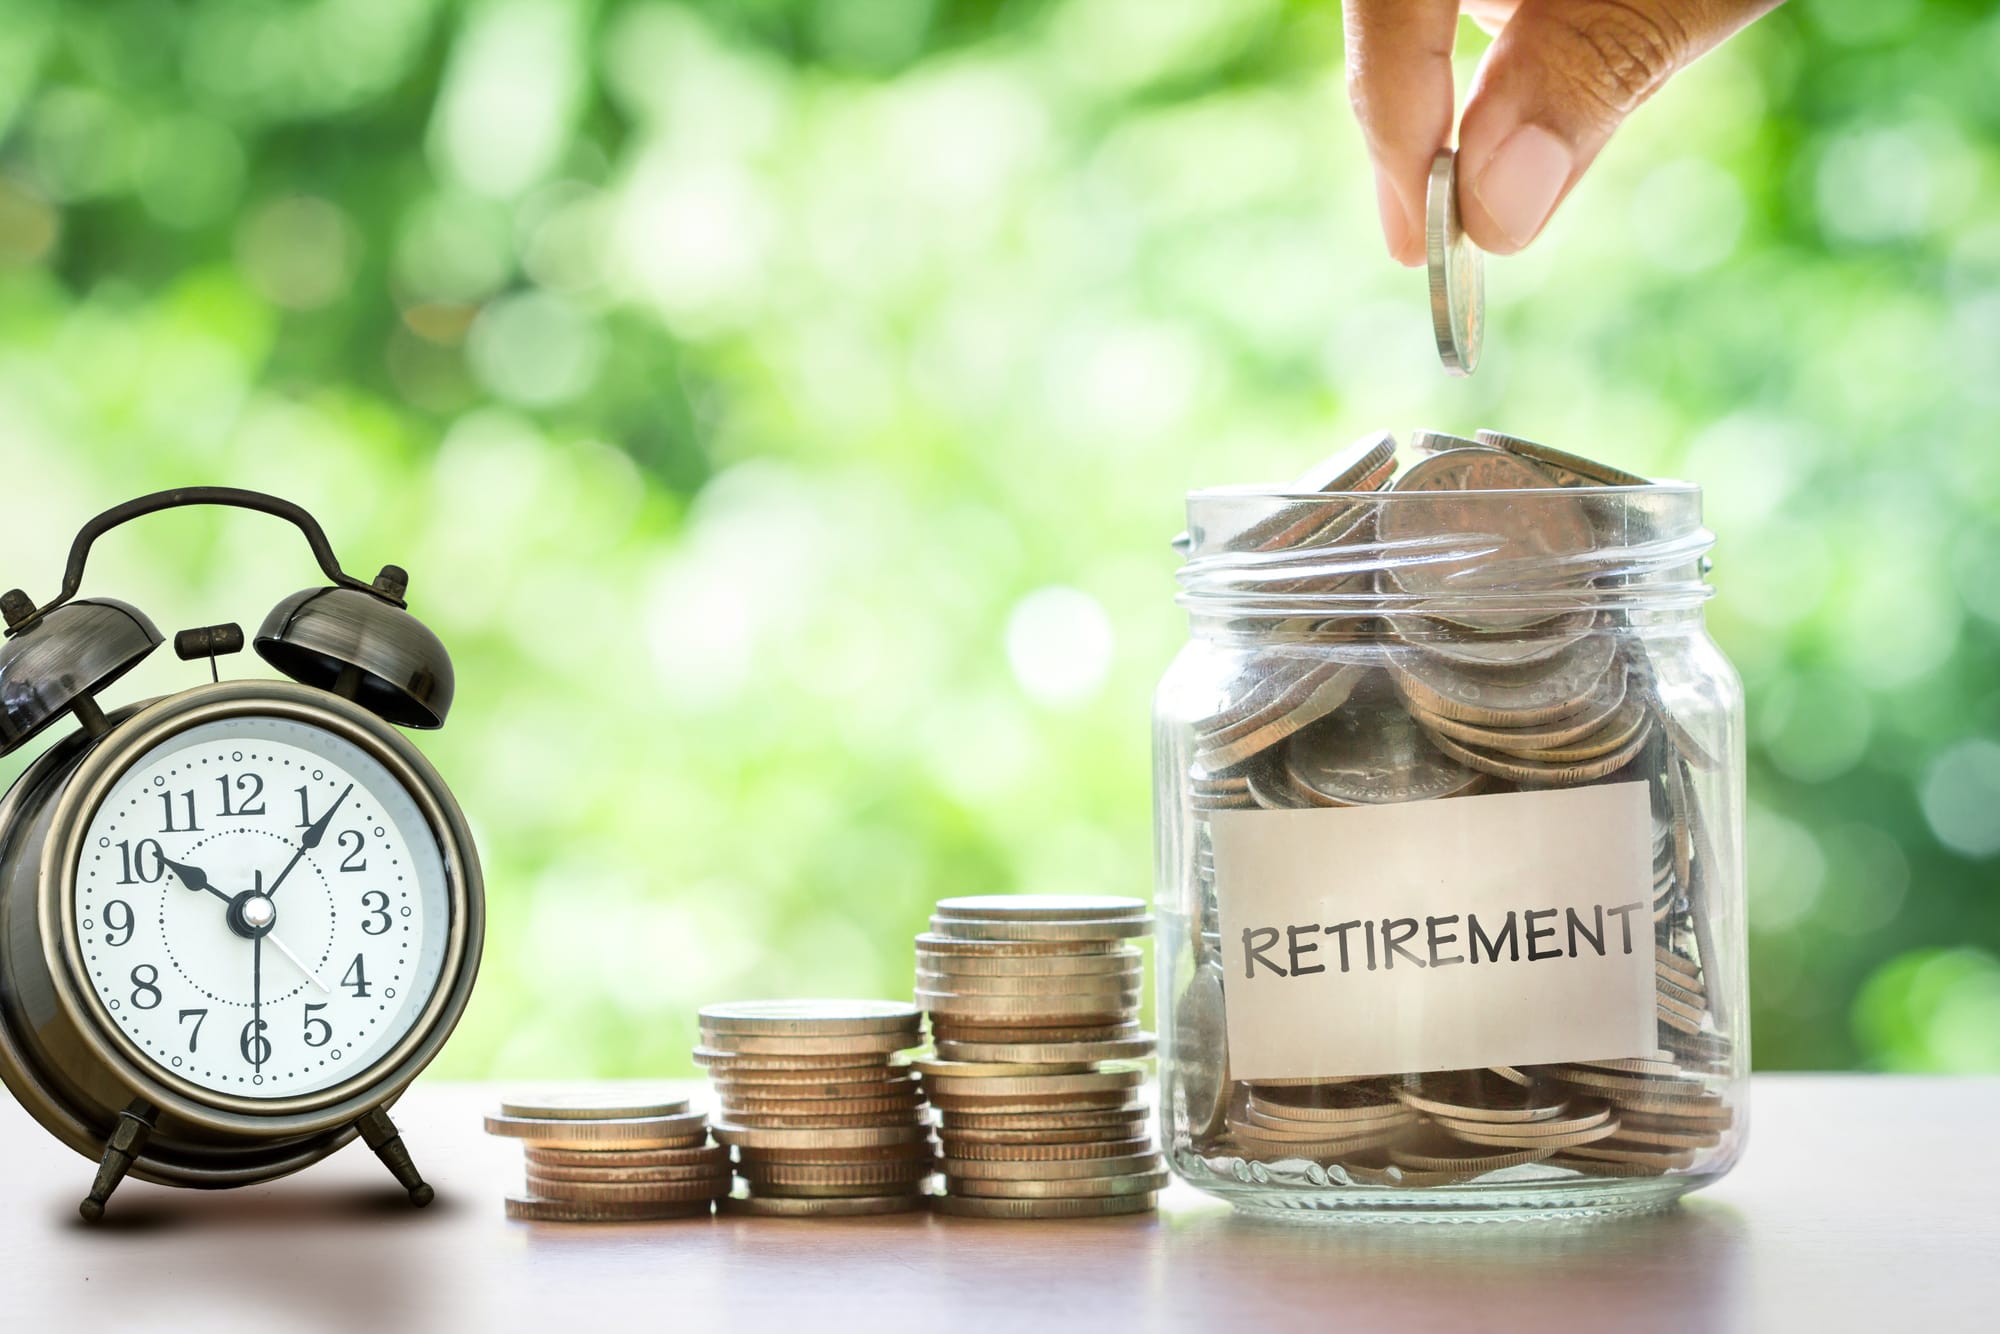
Hand putting Coins in glass jar with retro alarm clock for time to money saving for retirement concept

As you approach retirement, it’s crucial to think about your finances, future living arrangements, and health care needs. Integrating home care packages into your retirement plan is a smart move, one that ensures comfort and security in your later years. 

This article will explore the significant role of in-home services in your retirement. You’ll discover various service types, how to budget for them, and why they’re essential for a well-rounded retirement strategy. 

The Rising Need For Home Care In Retirement

As the population ages and life expectancy increases, the demand for in-home care during retirement is on the rise. In the U.S., the majority of home care recipients are over 65, with approximately 91% needing help moving in and out of bed. These figures underscore the growing necessity of factoring in this type of care when planning for retirement.

Additionally, the trend of aging in place, preferring home over institutional settings, is gaining popularity. This choice reflects a desire for a familiar and independent retirement lifestyle.

Types Of Home Care

Understanding the types of home care packages available is crucial to retirement planning. These packages support your living and health care needs at home, adapting as your requirements change.

  • Basic Care Packages: These are designed for individuals who need minimal assistance. Services might include help with housekeeping, basic meal preparation, and occasional transportation for errands or appointments.
  • Intermediate Care Packages: For those requiring regular assistance, intermediate packages offer more comprehensive services. This could include regular help with personal care, medication management, and more frequent transportation services.
  • Advanced Care Packages: Tailored for individuals with significant health care needs, these packages provide extensive assistance. Services include daily personal care, skilled nursing, physical therapy, and potentially even 24-hour care.
  • Specialized Care Packages: These are specific to certain conditions, like Alzheimer’s or other forms of dementia. Specialized care packages focus on providing tailored support, ensuring safety, and maintaining quality of life with condition-specific expertise.

Choosing the right home care package is essential for a comfortable retirement, ensuring you receive suitable support and can budget effectively for future care.

Financial Planning For Home Care

Effective financial planning for in-home support is vital in ensuring your retirement years are both comfortable and financially manageable. Here are the important considerations:

  • Assessing Costs

Start by getting a clear understanding of the costs associated with different levels of home care. Basic care packages are generally less expensive, while advanced or specialized care can significantly increase costs. 

For example, a basic care package might cost a few hundred dollars a month, whereas specialized care for conditions like Alzheimer’s can run into thousands.

  • Budgeting For Home Care

Incorporate home care expenses into your retirement budget. Consider factors like inflation, potential increases in healthcare costs, and the possibility of needing more intensive care in the future. 

For instance, setting aside an additional 10% to 20% of your estimated healthcare budget can help cushion against unforeseen increases in costs.

Healthcare, elderly woman with nurse with breakfast at her home and at the table in living room. Support or communication, caregiver and conversation with medical person with senior or old female
  • Exploring Insurance And Government Aid

Investigate long-term care insurance, which can cover some costs of in-home care services. Additionally, look into government programs like Medicare and Medicaid, which may offer financial assistance for certain services. 

Medicare often covers short-term home health care, while Medicaid may assist with long-term care for eligible individuals.

  • Planning For The Long Term

Consider the potential for long-term needs. This might involve setting aside a portion of savings specifically for home care or looking into financial products like annuities that can provide a steady income stream for future care expenses. 

For example, some retirees choose deferred annuities that begin payouts at a later age when in-home care services are more likely needed.

Incorporating these financial strategies into your retirement planning will help ensure you can afford the care you need without compromising your financial security.

Legal And Health Considerations In Home Care

When planning for home care in retirement, it’s important to understand legal agreements and anticipate health changes. Clear contracts with providers ensure your care aligns with expectations and needs. A flexible care plan, adaptable to evolving health conditions, is crucial for long-term comfort and security.

Involving family in decision-making can also provide support and peace of mind. Open discussions about personal wishes and practical healthcare needs are essential. This collaborative approach ensures that your home care solutions are both effective and respectful of your preferences.

By proactively addressing legal and health considerations, you can facilitate a smoother transition into a home care setup, making it an integral part of your retirement plan.

Final Thoughts

As you plan for retirement, including home care packages is a practical step towards ensuring a comfortable and secure future. By understanding the different types of care available, assessing costs, budgeting effectively, and being aware of insurance and legal considerations, you’re setting yourself up for a retirement that’s not only manageable but also dignified and fulfilling. 

Remember, advance planning can make all the difference in enjoying your retirement years with peace of mind and independence. It’s never too early to start building a retirement plan that truly meets your future needs.


Filed Under: Personal Finance

Understanding Life Insurance: Key Facts and Insights

January 9, 2024 by Susan Paige Leave a Comment

Life insurance is a vital financial tool that offers a safety net for individuals and their families, providing financial security and peace of mind in times of uncertainty. To make well-informed decisions about life insurance, it is essential to comprehend its various aspects fully. In this comprehensive guide, we will delve into the key facts and insights about life insurance, helping you gain a deeper understanding of this critical component of financial planning. Life insurance is a contractual agreement between an individual (the policyholder) and an insurance company. In exchange for regular premium payments, the insurance company pledges to provide a death benefit to the policyholder’s beneficiaries upon their passing. This financial protection ensures that loved ones are taken care of in the event of the policyholder’s death.

Types of Life Insurance

Term Life Insurance

Term life insurance offers coverage for a specific period, typically 10, 20, or 30 years. It provides a death benefit but does not accumulate cash value. Term policies are affordable and ideal for individuals seeking temporary coverage, such as to protect their family during their working years.

Whole Life Insurance

Whole life insurance, often referred to as permanent insurance, is a comprehensive financial tool that offers lifelong protection to policyholders. It stands out from term life insurance in that it combines a death benefit with a unique cash value component that has the potential to grow over time. One notable aspect of whole life policies is their ability to provide not only a safety net for your loved ones in the event of your passing but also an opportunity to accumulate wealth gradually.

When exploring insurance options, it’s crucial to consider local providers, such as a Scottsdale Insurance agency, or those in other cities, to guarantee a policy that’s perfectly adapted to the regional nuances and your personal needs.

Universal Life Insurance

Universal life insurance is a flexible policy that allows policyholders to adjust their premium payments and death benefits within certain limits. It also accumulates cash value and provides greater control over the policy’s terms. This flexibility makes it suitable for those who anticipate changes in their financial situation.

Benefits of Life Insurance

Life insurance offers several key benefits:

Financial Security for Loved Ones

The primary purpose of life insurance is to provide financial security to your loved ones in the event of your passing. The death benefit can help cover living expenses, pay off debts, and ensure your family’s well-being.

Debt and Mortgage Protection

Life insurance can be used to pay off outstanding debts, including mortgages, car loans, and credit card balances, relieving your family of these financial burdens.

Estate Planning

Life insurance plays a vital role in estate planning, helping to preserve and transfer wealth to heirs efficiently. It can cover estate taxes, ensuring that your assets are passed down as intended.

Tax Advantages

Life insurance proceeds are generally tax-free to beneficiaries. Additionally, certain policies offer tax-deferred growth on the cash value component, making them attractive for long-term financial planning.

Peace of Mind

Knowing that you have life insurance coverage in place provides peace of mind, knowing that your loved ones will be financially protected no matter what the future holds.

How Does Life Insurance Work?

Life insurance operates on a straightforward premise: you pay regular premiums, and in return, your beneficiaries receive a tax-free death benefit when you pass away. The coverage amount and premiums depend on the type of policy and your individual circumstances. It’s essential to select a coverage amount that adequately meets your family’s financial needs.

Determining Your Coverage Needs

Calculating the right amount of coverage is essential. Factors like your age, income, debts, and family’s financial needs should be considered. An insurance agent or online calculators can help determine your coverage needs accurately. Remember that your needs may change over time, so it’s crucial to review your policy periodically.

Factors Affecting Premiums

Several factors influence your life insurance premiums, including:

  • Age: Younger individuals typically pay lower premiums than older individuals.
  • Health: Your health status and medical history play a significant role in determining your premiums. Those with pre-existing conditions may face higher costs.
  • Lifestyle: Risky behaviors, such as smoking or engaging in hazardous activities, can lead to higher premiums.
  • Type of Policy: The type of life insurance policy you choose will impact your premiums. Term policies are generally more affordable than whole or universal life policies.

Cash Value in Life Insurance

Whole and universal life insurance policies accumulate cash value over time, which can be accessed through loans or withdrawals. This feature can be a valuable source of funds in emergencies or supplement your retirement income. Keep in mind that any loans or withdrawals may affect the death benefit.

Tax Implications of Life Insurance

Life insurance proceeds are generally tax-free to beneficiaries. However, there are exceptions, such as when the policy is considered part of your estate for estate tax purposes. Consulting with a tax advisor or financial planner can help you navigate the tax implications effectively.

Choosing the Right Life Insurance Company

Selecting a reputable insurance company is a critical step in obtaining the right life insurance policy. Consider the following factors when choosing a company:

  • Financial Stability: Ensure that the company is financially stable and capable of fulfilling its obligations to policyholders.
  • Customer Reviews: Research customer reviews and ratings to gauge the company’s reputation and customer service.
  • Types of Policies: Look at the types of life insurance policies offered by the company and choose one that aligns with your needs and goals.

Common Myths About Life Insurance

Dispelling myths about life insurance is essential. Some misconceptions include it being too expensive or unnecessary for young individuals. In reality, life insurance can be affordable and beneficial for all age groups. It’s essential to base your decisions on accurate information rather than misconceptions.

Who Needs Life Insurance?

Anyone with financial dependents or obligations should consider life insurance. It provides financial protection and ensures your loved ones are taken care of in your absence. Whether you’re a young parent, a homeowner, or a retiree, life insurance can play a crucial role in your financial planning.

Life Insurance as an Investment

Some types of life insurance, such as whole life, can serve as an investment vehicle. They offer a combination of protection and a way to build cash value over time. While they may not provide the same returns as traditional investments, they offer stability and tax advantages that can be appealing.

Reviewing and Updating Your Policy

Life changes, and so should your insurance policy. Regularly reviewing and updating your coverage to reflect your evolving financial needs and circumstances is crucial. Life events such as marriage, the birth of a child, or changes in income should trigger a review of your life insurance coverage.

Conclusion

Understanding life insurance is crucial for making informed financial decisions. It offers financial security, peace of mind, and a way to protect your loved ones. By considering the factors discussed in this guide, you can choose the right life insurance policy that suits your needs and provides a solid foundation for your family’s future financial well-being. Life insurance is not just a financial product; it’s a promise to provide for your loved ones when they need it most.

Filed Under: Personal Finance

  • « Previous Page
  • 1
  • …
  • 16
  • 17
  • 18
  • 19
  • 20
  • …
  • 63
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework