• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Wealth Building

5 Business You Could Start Today To Make 6 Figures By The End Of The Year

May 9, 2025 by Travis Campbell Leave a Comment

starting business
Image Source: pexels.com

The dream of financial independence drives many aspiring entrepreneurs, but the path to a six-figure income often seems distant and complex. However, several business models exist today that combine low startup costs and high earning potential. With dedication, strategic planning, and consistent execution, these ventures could generate six figures within months, not years. Whether you’re looking to escape the 9-to-5 grind or build additional income streams, these opportunities offer viable paths to significant earnings before year’s end.

1. High-Ticket Digital Marketing Agency

Digital marketing remains one of the most accessible yet lucrative businesses to launch. Companies desperately need experts to navigate the ever-changing digital landscape and are willing to pay premium rates for results.

Start by specializing in one high-demand area, such as paid advertising, SEO, or social media management. Focus on serving specific industries where you have knowledge or connections. For example, a digital marketing agency specializing in dental practices can charge $3,000-$10,000 monthly per client because it understands the unique challenges and opportunities in that niche.

The math is compelling: securing just 10 clients at $5,000 monthly creates a $50,000 monthly revenue stream. With proper systems and a small team of contractors, you can maintain 30-40% profit margins while scaling.

According to Xola, businesses spend an average of 13.2% of their revenue on marketing, with digital channels taking an increasingly larger share.

2. E-commerce Product Arbitrage

E-commerce arbitrage—buying products at lower prices and reselling them at a markup—offers a straightforward path to significant profits with minimal startup costs.

Begin by identifying trending products with high margins on platforms like Amazon, eBay, or Shopify. Tools like Jungle Scout or Helium 10 can help identify profitable niches. Many successful arbitrage entrepreneurs start with retail arbitrage (buying discounted items from physical stores) before graduating to online arbitrage or wholesale relationships.

The key to six-figure success lies in volume and systems. You can scale rapidly by reinvesting profits into inventory expansion and eventually hiring virtual assistants to handle sourcing and listing. Many successful arbitrage businesses generate a $20,000-$30,000 monthly profit after just 6-8 months of consistent effort.

Develop relationships with suppliers and optimize your product selection based on data, not hunches. Focus on items with at least 30% profit margins after all fees and shipping costs.

3. High-End Freelance Consulting

Freelancing isn’t just about gig work—positioned correctly, it becomes high-end consulting that commands premium rates. The difference between making $50 per hour and $250+ per hour often comes down to positioning, specialization, and confidence.

Identify a specialized skill where you have experience and businesses have urgent needs. This could be fractional CFO services, compliance consulting, conversion rate optimization, or executive coaching. Package your services into comprehensive solutions rather than hourly work.

Research by Upwork shows that 59% of hiring managers are using freelancers to fill skill gaps in their organizations, with specialized expertise commanding the highest rates.

To reach six figures quickly, focus on securing 3-5 retainer clients rather than constant project hunting. A monthly retainer of $5,000-$10,000 per client is achievable when you demonstrate clear ROI. With just four clients at $8,000 monthly, you’ll exceed six figures within months.

4. Property Management and Short-Term Rental Optimization

The short-term rental market continues to boom, but many property owners lack the time or expertise to maximize their returns. This creates an opportunity for a property management business specializing in optimizing vacation rentals and Airbnb properties.

You don’t need to own properties yourself. Instead, offer comprehensive management services including listing optimization, pricing strategy, guest communication, cleaning coordination, and maintenance management. Standard rates range from 20-30% of rental income.

With strategic marketing to property owners in high-demand vacation areas, you could manage 15-20 properties within months. At an average monthly revenue of $3,000 per property and a 25% management fee, managing just 20 properties would generate $15,000 monthly ($180,000 annually).

The key differentiator is using data analytics and dynamic pricing tools to maximize occupancy rates and nightly prices, delivering measurable ROI to property owners.

5. Online Education and Course Creation

According to Research and Markets, the global e-learning market is projected to reach $325 billion by 2025, making course creation one of the most scalable business models available.

Success in this space requires identifying a specific knowledge gap where you have expertise and people actively seek solutions. Rather than competing in oversaturated markets like “how to make money online,” focus on specialized knowledge like “tax strategies for e-commerce sellers” or “advanced Facebook ads for local service businesses.”

A well-structured course priced between $997 and $2,997 can generate significant revenue with proper marketing. With a conversion-optimized sales funnel and targeted advertising, reaching six figures requires selling just 34-100 courses, depending on your price point.

The most successful course creators combine their digital products with high-touch components like group coaching calls or communities, justifying premium pricing while building a loyal customer base that purchases additional offerings.

Turning Opportunity into Reality: The Implementation Roadmap

The difference between entrepreneurs who achieve six figures quickly and those who struggle isn’t just the business model—it’s execution. Each business mentioned requires a methodical approach: market research, minimum viable product development, systematic marketing, and relentless optimization.

Start by selecting the model that best aligns with your skills and resources. Then, create a 90-day sprint plan with specific revenue targets and daily action steps. Focus on revenue-generating activities first, build systems, and delegate only after establishing consistent cash flow.

Remember that reaching six figures requires both strategy and psychology. Many entrepreneurs sabotage their success through perfectionism or inconsistency. Commit to imperfect action daily, measure results objectively, and adjust course as needed.

Have you considered starting any of these businesses, or are you already running one? Share your experiences or questions in the comments below!

Read More

5 Money Management Tips You Should Know as a New Entrepreneur

How to Fund a Startup When You Don’t Have Any of Your Own Money

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Wealth Building Tagged With: business startup, digital marketing agency, e-commerce arbitrage, entrepreneurship, freelance consulting, online courses, property management, six-figure business

What Makes Rich People Cheap (And Why It Works)

May 8, 2025 by Travis Campbell Leave a Comment

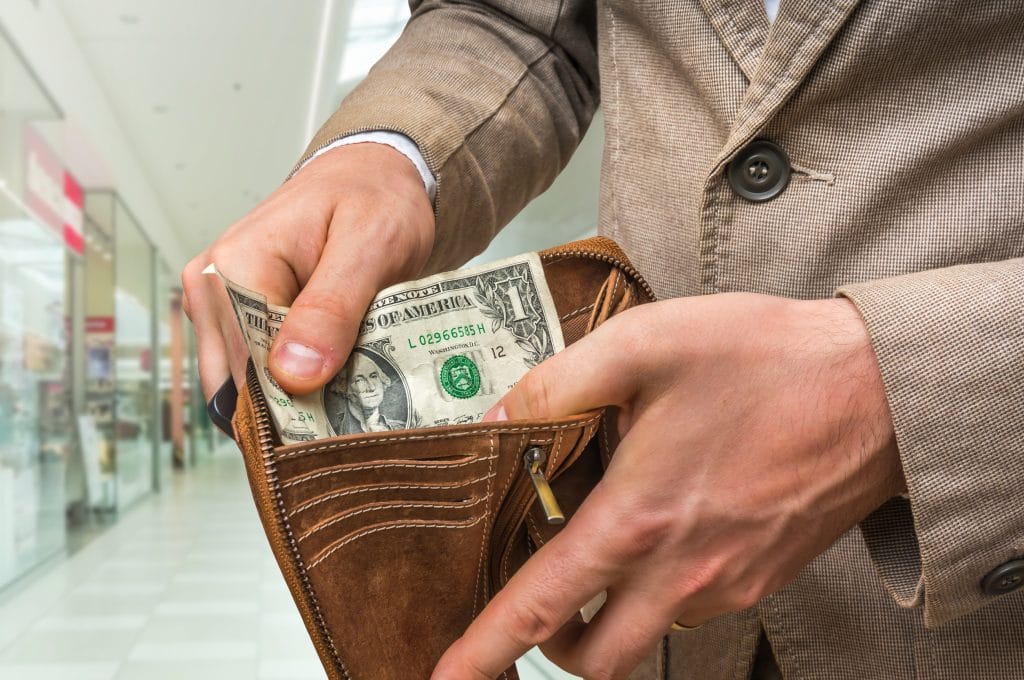
Man holding leather wallet with only one dollar inside
Image Source: 123rf.com

Wealthy individuals often display surprisingly frugal behaviors that contradict their financial status. While they could easily afford luxury, many choose thriftiness instead. This phenomenon isn’t merely quirky behavior—it’s a fundamental mindset that helped create their wealth in the first place. Understanding these frugal habits offers valuable insights for anyone looking to build financial security. The principles guiding wealthy individuals’ spending decisions can transform how you manage your finances, regardless of your current income level.

1. They Understand the True Value of Money

Rich people recognize that money represents stored time and energy. They calculate exactly how many hours of work each purchase requires and weigh this against the value received. This isn’t about being stingy—it’s about respecting what money represents.

When wealthy individuals avoid $6 coffee drinks or clip coupons, they’re demonstrating a deep understanding that small expenses compound dramatically over time. According to research from The Millionaire Next Door, most millionaires live well below their means and are far more likely to use coupons than the average consumer.

This value-based approach to spending creates a psychological framework where each purchase must justify itself. The wealthy person asks: “Is this worth the hours of my life it represents?” rather than “Can I afford this?” This subtle shift in perspective drives consistently better financial decisions.

2. They Prioritize Assets Over Appearances

Wealthy individuals often direct their resources toward appreciating assets rather than depreciating status symbols. While they might drive modest cars or live in reasonable homes, they’re simultaneously investing in businesses, real estate, and other wealth-building vehicles.

This prioritization reflects a fundamental understanding that appearances drain resources while assets generate them. Self-made ultra-high-net-worth individuals are significantly more likely to drive mid-range vehicles than their inherited-wealth counterparts.

The wealthy recognize that every dollar spent on status is a dollar that can’t compound through investment. They’re playing a different game focused on long-term wealth accumulation rather than short-term social signaling. This doesn’t mean they never indulge, but rather that they’re strategic about where they display wealth and where they practice restraint.

3. They’ve Mastered Delayed Gratification

The ability to postpone immediate pleasure for future benefit is perhaps the most powerful psychological trait among the wealthy. Research consistently shows that delayed gratification correlates strongly with financial success.

Wealthy individuals have trained themselves to evaluate purchases based on immediate satisfaction and long-term impact. They ask: “Will this purchase matter to me in five years?” This temporal perspective shifts spending away from impulse and toward intention.

The famous Stanford Marshmallow Experiment demonstrated that children who could delay gratification achieved better life outcomes. The wealthy have internalized this principle, creating spending habits that reflect patience and long-term thinking.

This doesn’t mean never enjoying life—instead, it means being selective about which pleasures are worth the cost, both financial and opportunity-related.

4. They Recognize the Hidden Cost of Lifestyle Inflation

As income rises, most people automatically increase their spending—a phenomenon known as lifestyle inflation. The wealthy often resist this urge, maintaining modest lifestyles even as their wealth grows substantially.

This resistance to lifestyle inflation creates an expanding gap between income and expenses—the foundation of wealth building. While their peers upgrade to larger homes, newer cars, and more expensive vacations with each income increase, the wealthy often maintain a consistent, comfortable lifestyle.

Warren Buffett exemplifies this principle by living in the same modest home he purchased in 1958 despite becoming one of the world’s richest individuals. This isn’t deprivation—it’s strategic allocation of resources toward what truly matters to them.

5. They View Frugality as a Game, not a Burden

Many wealthy individuals approach saving money as an engaging challenge rather than a restrictive chore. They derive satisfaction from finding deals, negotiating better terms, and optimizing their spending.

This gamification of frugality transforms what could be seen as deprivation into a rewarding activity. They might compare notes with other wealthy friends about deals found or unnecessary expenses eliminated, creating social reinforcement for thrifty behavior.

The psychological reward comes not from the money saved itself, but from the skill demonstrated in optimizing resources. This positive association with frugality makes it sustainable long-term, unlike deprivation-based budgeting that often fails.

The Wealth Paradox: Why Being “Cheap” Actually Creates Freedom

The ultimate irony is that these seemingly restrictive habits actually create unprecedented freedom. By controlling spending impulses and directing resources strategically, wealthy individuals build financial independence to choose how they spend their time and energy.

This freedom represents the real luxury that money can provide—not designer labels or luxury cars, but the ability to make life choices without financial constraint. The wealthy person who appears “cheap” in daily transactions often enjoys a level of life autonomy that their free-spending peers can only imagine.

The principles that guide wealthy individuals’ spending aren’t about deprivation—they’re about optimization. By understanding the true value of money, prioritizing assets, mastering delayed gratification, avoiding lifestyle inflation, and finding joy in frugality, they build sustainable wealth that serves their deeper life goals.

Have you noticed any “cheap” habits in successful people you know? What frugal practices have you adopted that have improved your own financial situation?

Read More

Millionaire Secrets: 7 Weird Money Habits That Actually Work

These Are the 6 Things That Rich People Invest In That Most Know Nothing About

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Wealth Building Tagged With: delayed gratification, financial freedom, frugality, millionaire mindset, money psychology, Wealth Building

Listen Well: The Advice That May Make You Rich If You Would Only Listen To Your Elders

April 25, 2025 by Travis Campbell Leave a Comment

old man holding money
Image Source: pexels.com

Financial wisdom often comes with age and experience. While younger generations chase the latest investment trends and quick-money schemes, there’s profound value in the time-tested financial principles our elders have learned through decades of economic cycles. Their advice—born from living through recessions, market crashes, and periods of growth—offers a roadmap that many of us ignore at our financial peril. By listening to these seasoned perspectives, you might discover the wealth-building strategies that have consistently worked across generations, potentially saving yourself years of costly financial mistakes.

1. Live Below Your Means

The cornerstone of all financial success begins with a simple principle that older generations mastered out of necessity: spend less than you earn. This isn’t just about cutting coupons or skipping lattes. It’s about adopting a lifestyle that creates margin in your finances.

Many elders who lived through economic hardships like the Great Depression developed habits of resourcefulness that served them well even in prosperous times. They understood that wealth accumulation isn’t about how much you make, but how much you keep. Research from the Employee Benefit Research Institute shows that households that consistently save at least 15% of their income are significantly more likely to achieve financial independence, regardless of income level.

This principle requires an honest assessment of needs versus wants. As Warren Buffett famously said, “If you buy things you don’t need, soon you will have to sell things you need.” The wisdom of restraint may seem old-fashioned in our consumer culture, but it remains the foundation upon which all other financial success is built.

2. Avoid Debt Like the Plague

“Neither a borrower nor a lender be” isn’t just Shakespeare—it’s the mantra many of our grandparents lived by. While some debt may be strategic (like mortgages or education loans), older generations typically view debt with healthy skepticism.

They understood something many have forgotten: debt represents future income already spent. Every dollar of interest paid is a dollar that can’t build wealth. A Federal Reserve study found that nearly 40% of Americans couldn’t cover a $400 emergency without borrowing—a situation most elders would find unthinkable.

The wisdom here isn’t avoiding all debt forever, but rather approaching it cautiously, understanding its true cost, and prioritizing its elimination. As financial advisor Dave Ramsey often says, channeling the wisdom of previous generations: “Debt is not a tool; it is a method to make banks wealthy, not you.”

3. Invest Early and Consistently

“The best time to plant a tree was 20 years ago. The second best time is now.” This proverb captures the essence of investment wisdom passed down through generations. Over the decades, elders who built wealth often did so through consistent, patient investing.

They understood the power of compound interest—what Einstein allegedly called “the eighth wonder of the world.” Starting early, even with small amounts, creates a snowball effect that time amplifies dramatically. According to Vanguard research, an investor who saves $10,000 per year from ages 25 to 35 and then stops will have more money at retirement than someone who saves the same amount every year from 35 to 65.

The patience to let investments grow, the discipline to continue during market downturns, and the wisdom to avoid chasing trends—these qualities define successful investors across generations.

4. Build Multiple Income Streams

“Don’t put all your eggs in one basket” isn’t just about investment diversification—it’s about income sources too. Many elders who achieved financial security created multiple ways to generate income beyond their primary job.

Whether through rental properties, side businesses, investing dividends, or developing marketable skills, they understood that relying solely on a paycheck creates vulnerability. Economic downturns, industry disruptions, and health challenges can quickly eliminate a single income source.

This diversification strategy provides both security and opportunity. Each additional income stream reduces risk and potentially accelerates wealth building when the proceeds are reinvested rather than spent.

5. Prioritize Relationships Over Possessions

Perhaps older generations’ most profound financial wisdom isn’t directly about money. Many elders who’ve experienced both wealth and hardship will tell you that relationships—not possessions—ultimately determine life satisfaction.

This perspective powerfully influences financial decisions. It might mean choosing a less prestigious job that allows more family time, living in a modest home to reduce financial stress, or spending on experiences that strengthen relationships rather than status symbols that depreciate.

Research consistently shows that additional consumption provides diminishing returns on happiness beyond meeting basic needs. Meanwhile, strong social connections correlate strongly with both financial resilience and life satisfaction.

The Wisdom That Compounds Over Time

Financial advice from elders isn’t just about specific strategies—it’s about adopting principles that have withstood the test of time. Their perspective comes from seeing full economic cycles, experiencing both mistakes and successes, and understanding what truly matters in the long run.

By listening to these voices of experience, we gain something more valuable than specific investment tips or budgeting techniques. We gain wisdom—the ability to make decisions aligned with enduring values rather than fleeting trends. This wisdom, like compound interest, grows more valuable over time as it shapes countless financial decisions throughout life.

Have you received financial advice from parents, grandparents, or mentors that proved especially valuable? What generational wisdom has shaped your approach to money, and how has it impacted your financial journey?

Read More

10 Genius Wealth Transfer Hacks That’ll Make Your Heirs Thank You Forever

12 Crucial Money Lessons Baby Boomers Passed Down to Their Millennial Kids

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Wealth Building Tagged With: financial independence, financial wisdom, generational advice, investment strategy, money management, retirement planning, Wealth Building

  • « Previous Page
  • 1
  • …
  • 6
  • 7
  • 8

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework